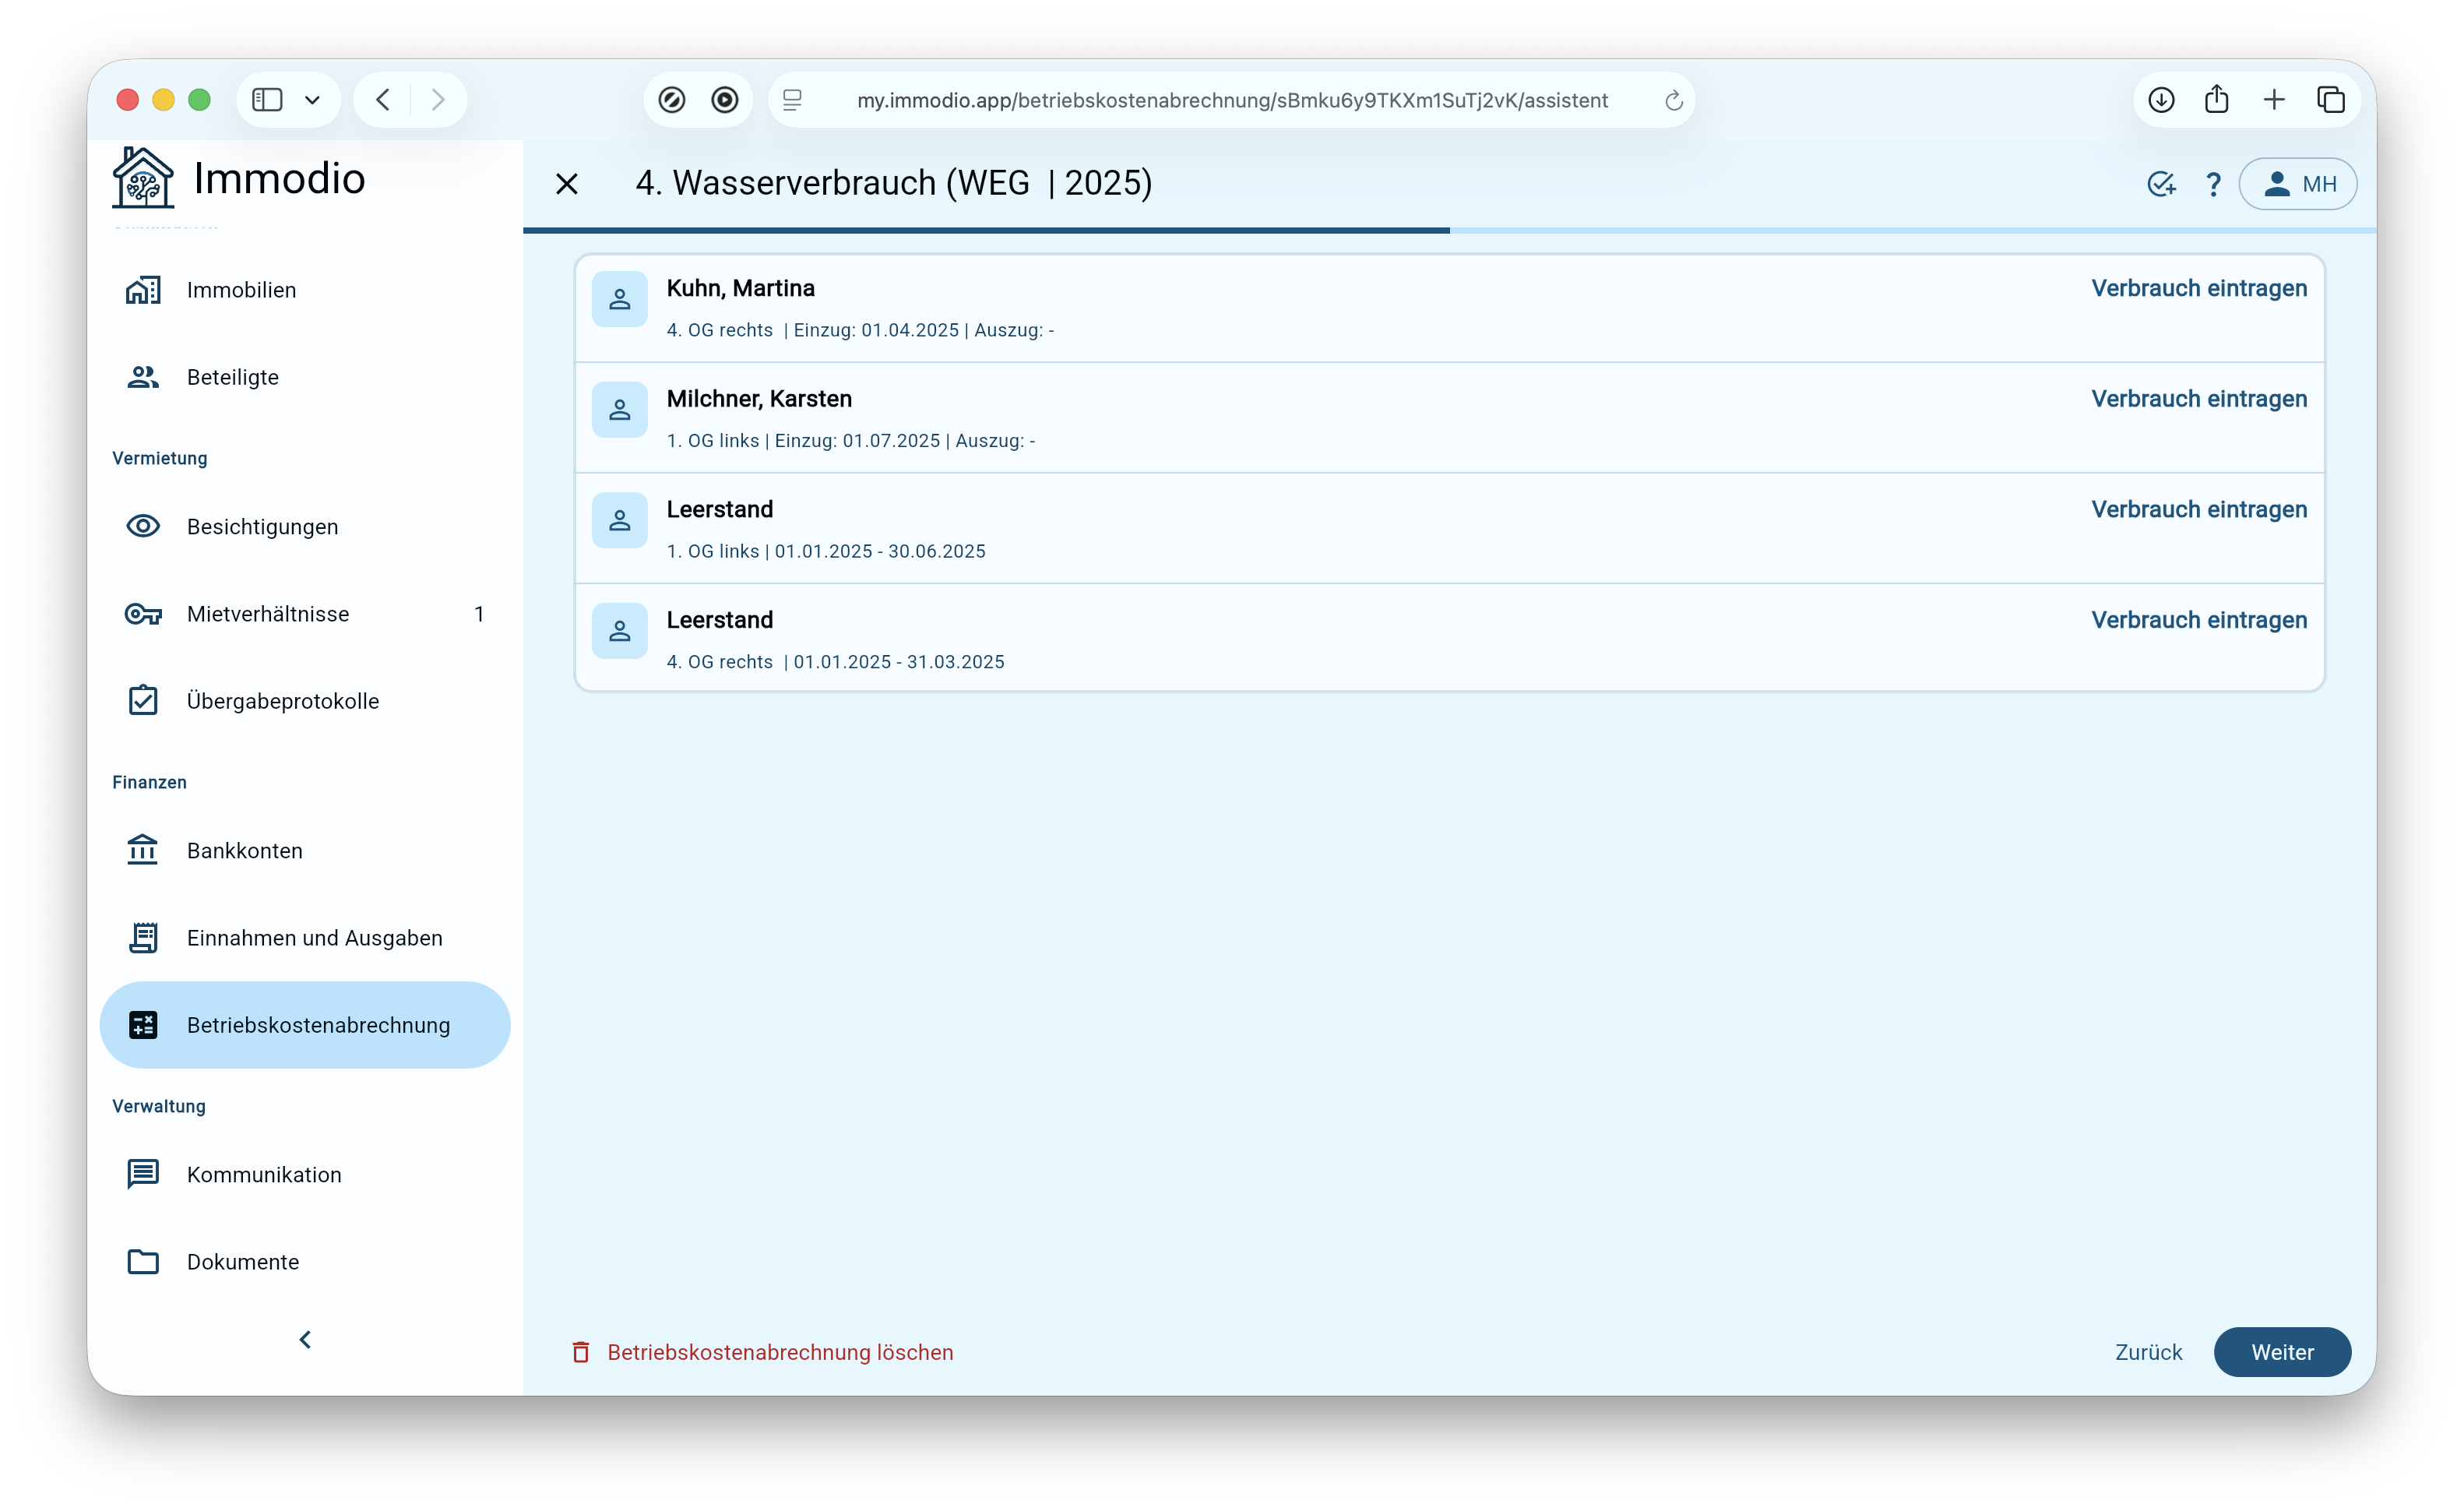
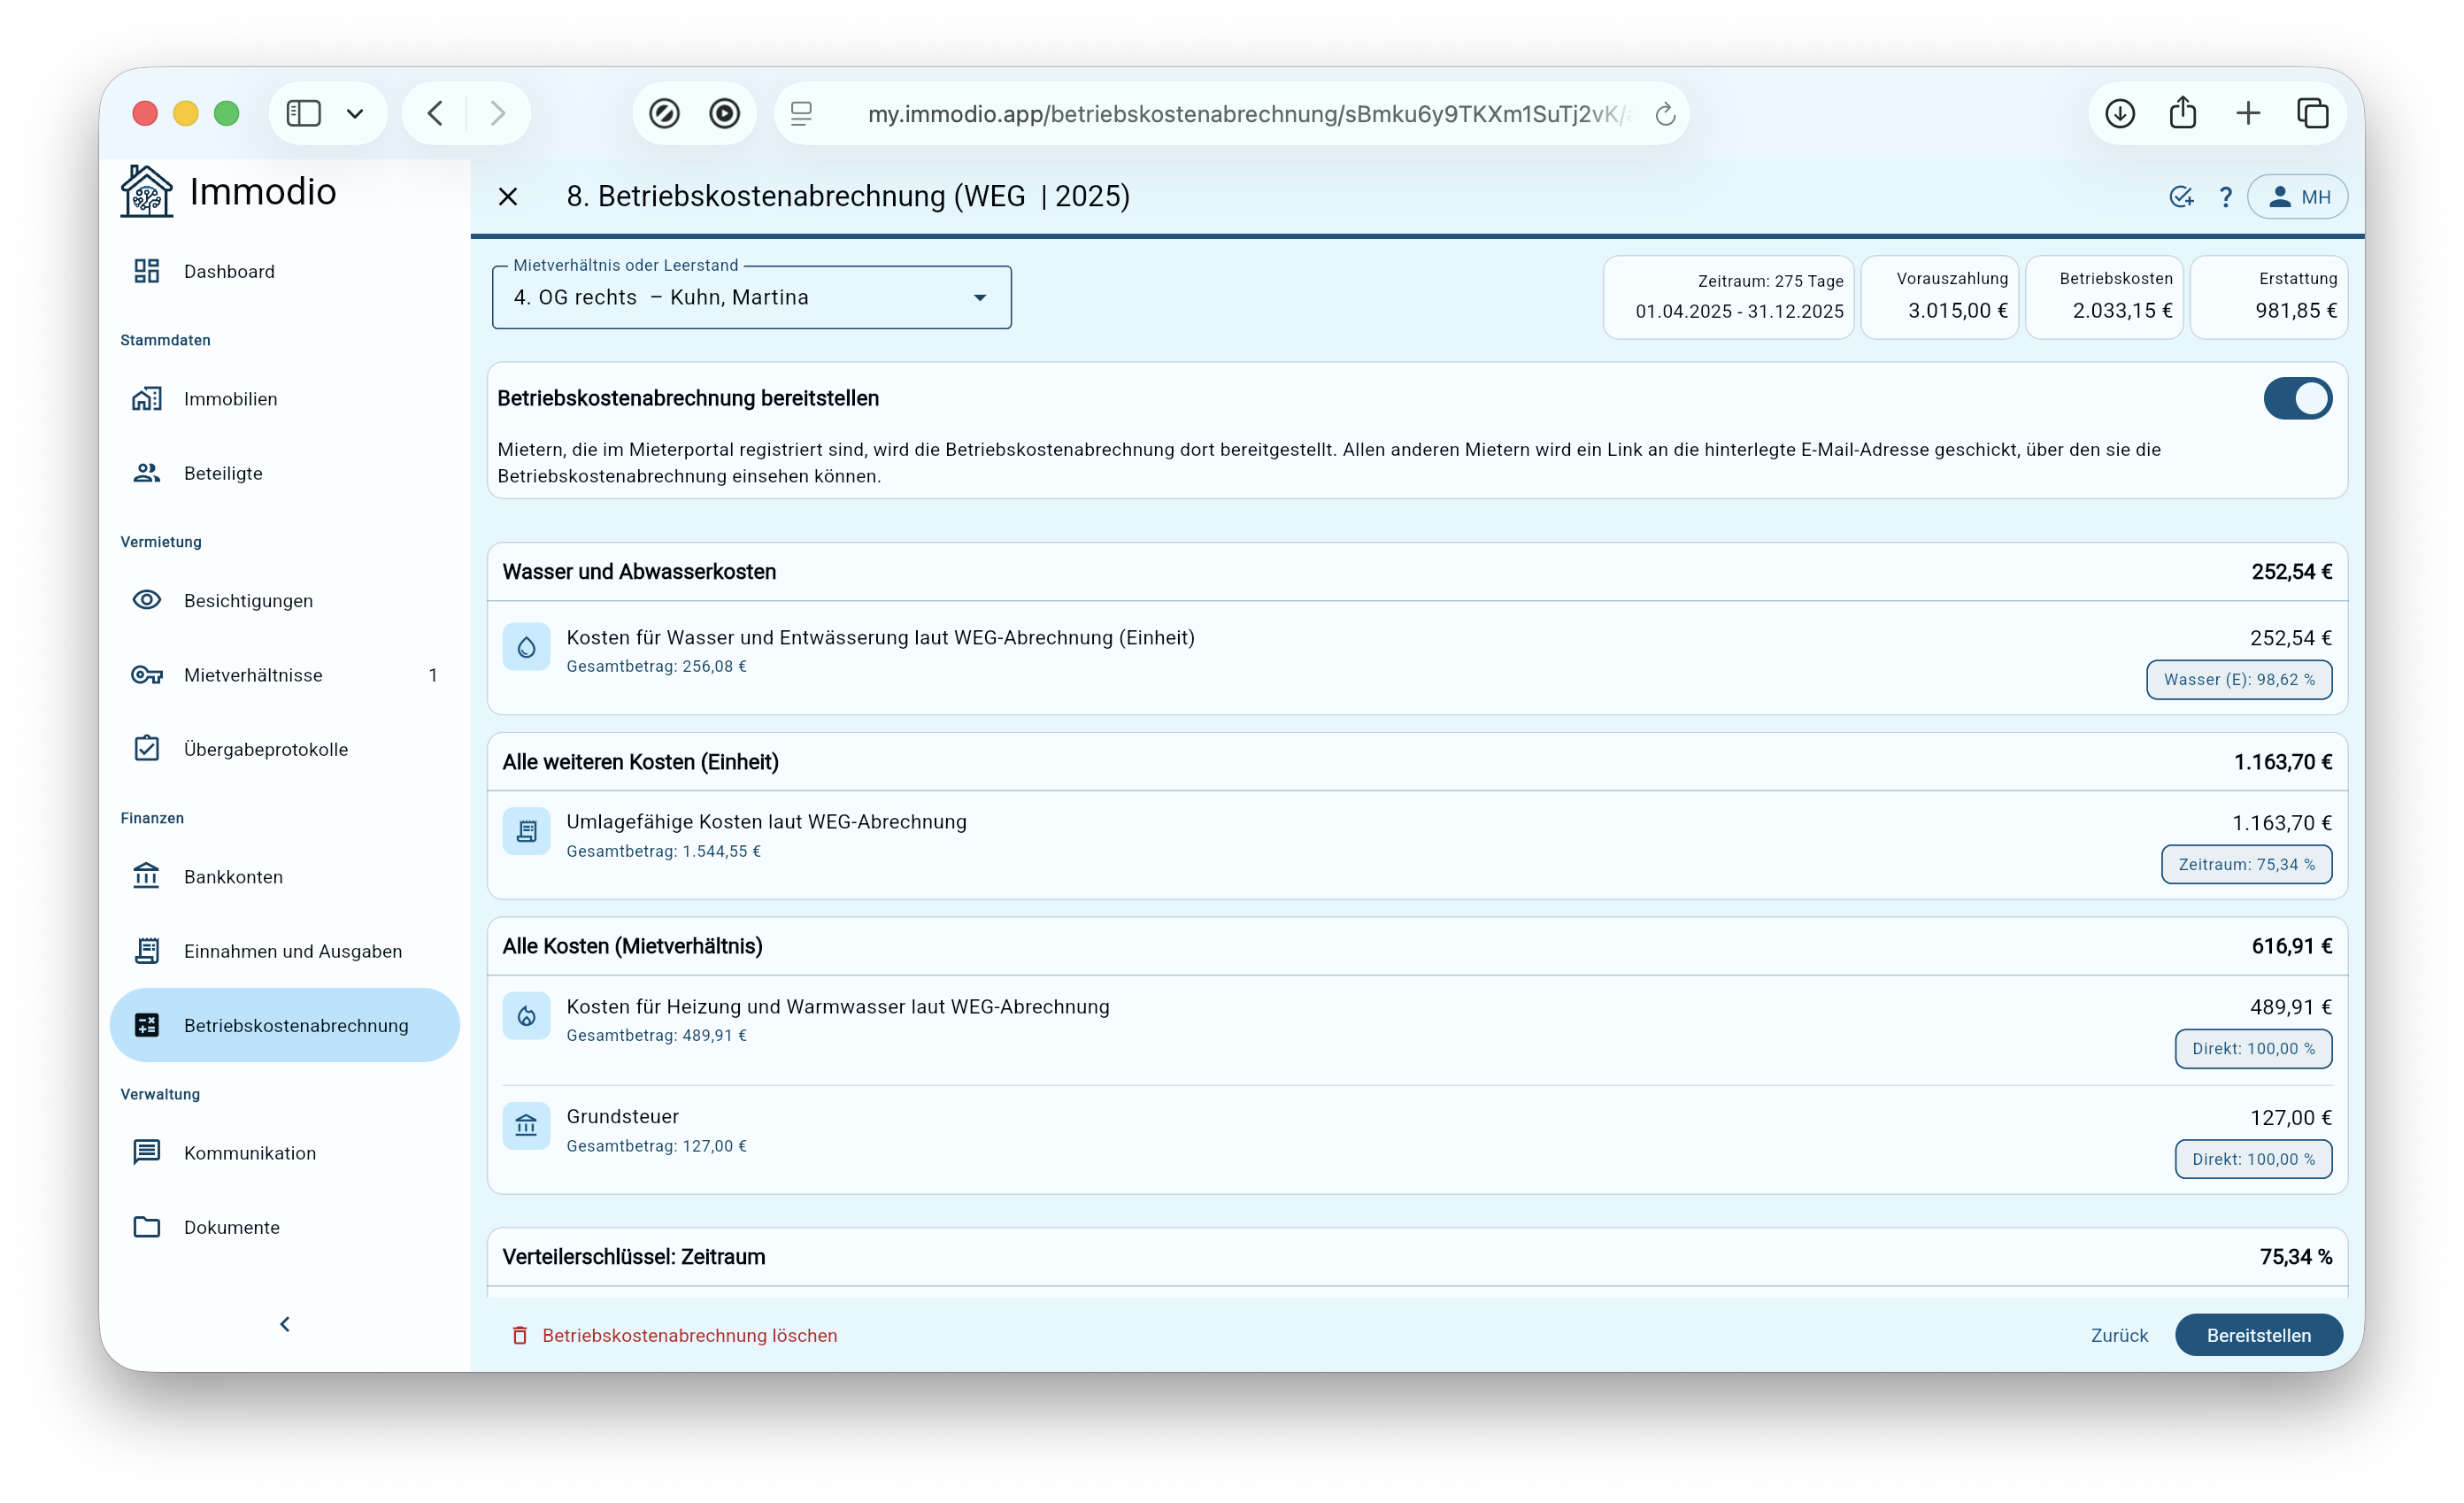
> For the complete documentation index, see [llms.txt](https://help.immodio.app/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://help.immodio.app/en/anleitung/betriebskostenabrechnungen/betriebskostenabrechnung-fur-einheiten-in-einer-weg-erstellen.md).
# Creating an operating cost statement for units in a WEG
This is how you create an operating cost statement for one or more units let in a WEG.
If you let a freehold apartment or another unit within an **owners' association** **(WEG)**, the operating cost statement in Immodio works a little differently than with a classic apartment building. The most important basis is not the overall statement for the whole building but the individual WEG statement for the specific unit or units that you have.
With an ordinary operating cost statement you generally record costs at property level and Immodio then allocates those costs to all units or tenancies. With a WEG the allocation of the costs to the owners and individual tenancies is generally already contained in the finished WEG statement.
For your operating cost statement this means:
* what matters is the **individual WEG statement for your unit**
* WEG costs are recorded in Immodio through separate "**WEG categories**".
* items such as heating, hot water, water and drainage costs from the WEG statement are entered directly against the tenancy or the unit.
* non-recoverable items such as maintenance, refurbishment, reserves or administrative costs do not belong in the operating cost statement to the tenant, but they can still be entered for your [DATEV export](/en/anleitung/einnahmen-und-ausgaben/datev-export.md) to your tax adviser.
Immodio recognises a WEG by the property being marked as a **WEG** in the [property's basic data](/en/anleitung/immobilien/objekt/grunddaten-objekt.md).
{% hint style="info" %}
This help page sets out the basic process of the operating cost statement for a unit in a WEG. You can find comprehensive help on the individual steps of the operating cost statement on the respective help pages, for example [**here**](/en/anleitung/betriebskostenabrechnungen/jahr-und-objekt.md).
{% endhint %}
***
## The allocation key with a WEG
With a freehold apartment that is let, special rules apply to the allocation of the operating costs. What matters is generally not automatically the **living space** but the **allocation key set within the WEG for the type of cost concerned**.
This means that where the WEG uses co-ownership shares or another allocation key it has resolved on, that key generally also has to be adopted for the operating cost statement to the tenant. The statutory basis for this is Section 556a (3) BGB.
{% hint style="info" %}
You can find further information on creating individual allocation keys [**here**](/en/anleitung/immobilien/objekt/abrechnung-objekt.md#individual-allocation-keys).
{% endhint %}
Explanations of allocation keys in a WEG
#### The statutory starting point for allocating operating costs (not a WEG)
**Section 556a (1) BGB:** "Unless the parties have agreed otherwise, the operating costs are to be allocated according to the share of the living space, subject to other provisions."
#### Allocating operating costs with a WEG
**Section 556a (3) BGB:** "Where freehold apartment property is let and the parties have not agreed otherwise, the operating costs are, by way of derogation from subsection 1, to be allocated by the measure applicable to the allocation between the apartment owners. Where that measure is contrary to equitable discretion, allocation is to be made under subsection 1."
The WEG reform brings tenancy law and WEG law into line. The landlord can in principle rely on the WEG statement and adopt its allocation key.
Under the previous law the owner was obliged to allocate the operating costs by living space. Problems arose where differing cost allocations were set in the declaration of division or by resolution.
The new version of Section 556a (3) BGB removes these problems. Since 1 December 2020 what matters for the allocation of the operating costs is therefore the allocation measure agreed between the apartment owners, provided it is not contrary to equitable discretion.
Section 556a (3) BGB transfers the WEG's allocation key to the tenancy in principle. The following measures in particular may therefore be used:
* co-ownership shares
* other allocation keys resolved on in the WEG
***
## A step-by-step guide
In Immodio an operating cost statement for a unit in a WEG consists conceptually of two parts: first you record the relevant items from the WEG statement, and then the entries for the costs you incurred additionally, specifically for your freehold apartment.
{% hint style="info" %}
At the end the finished WEG statement is additionally attached digitally as a document to the respective tenancies before the statement is provided, which is why it is **not** necessary to enter every item individually.
{% endhint %}
#### Assigning the entries
Depending on whether there was a change of tenant during the settlement period and whether it was already taken into account in the WEG statement you have, you have to assign the entries differently when creating them:
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
Below you will find a guide to all the relevant steps you go through for an operating cost statement in a WEG:
{% stepper %}
{% step %}
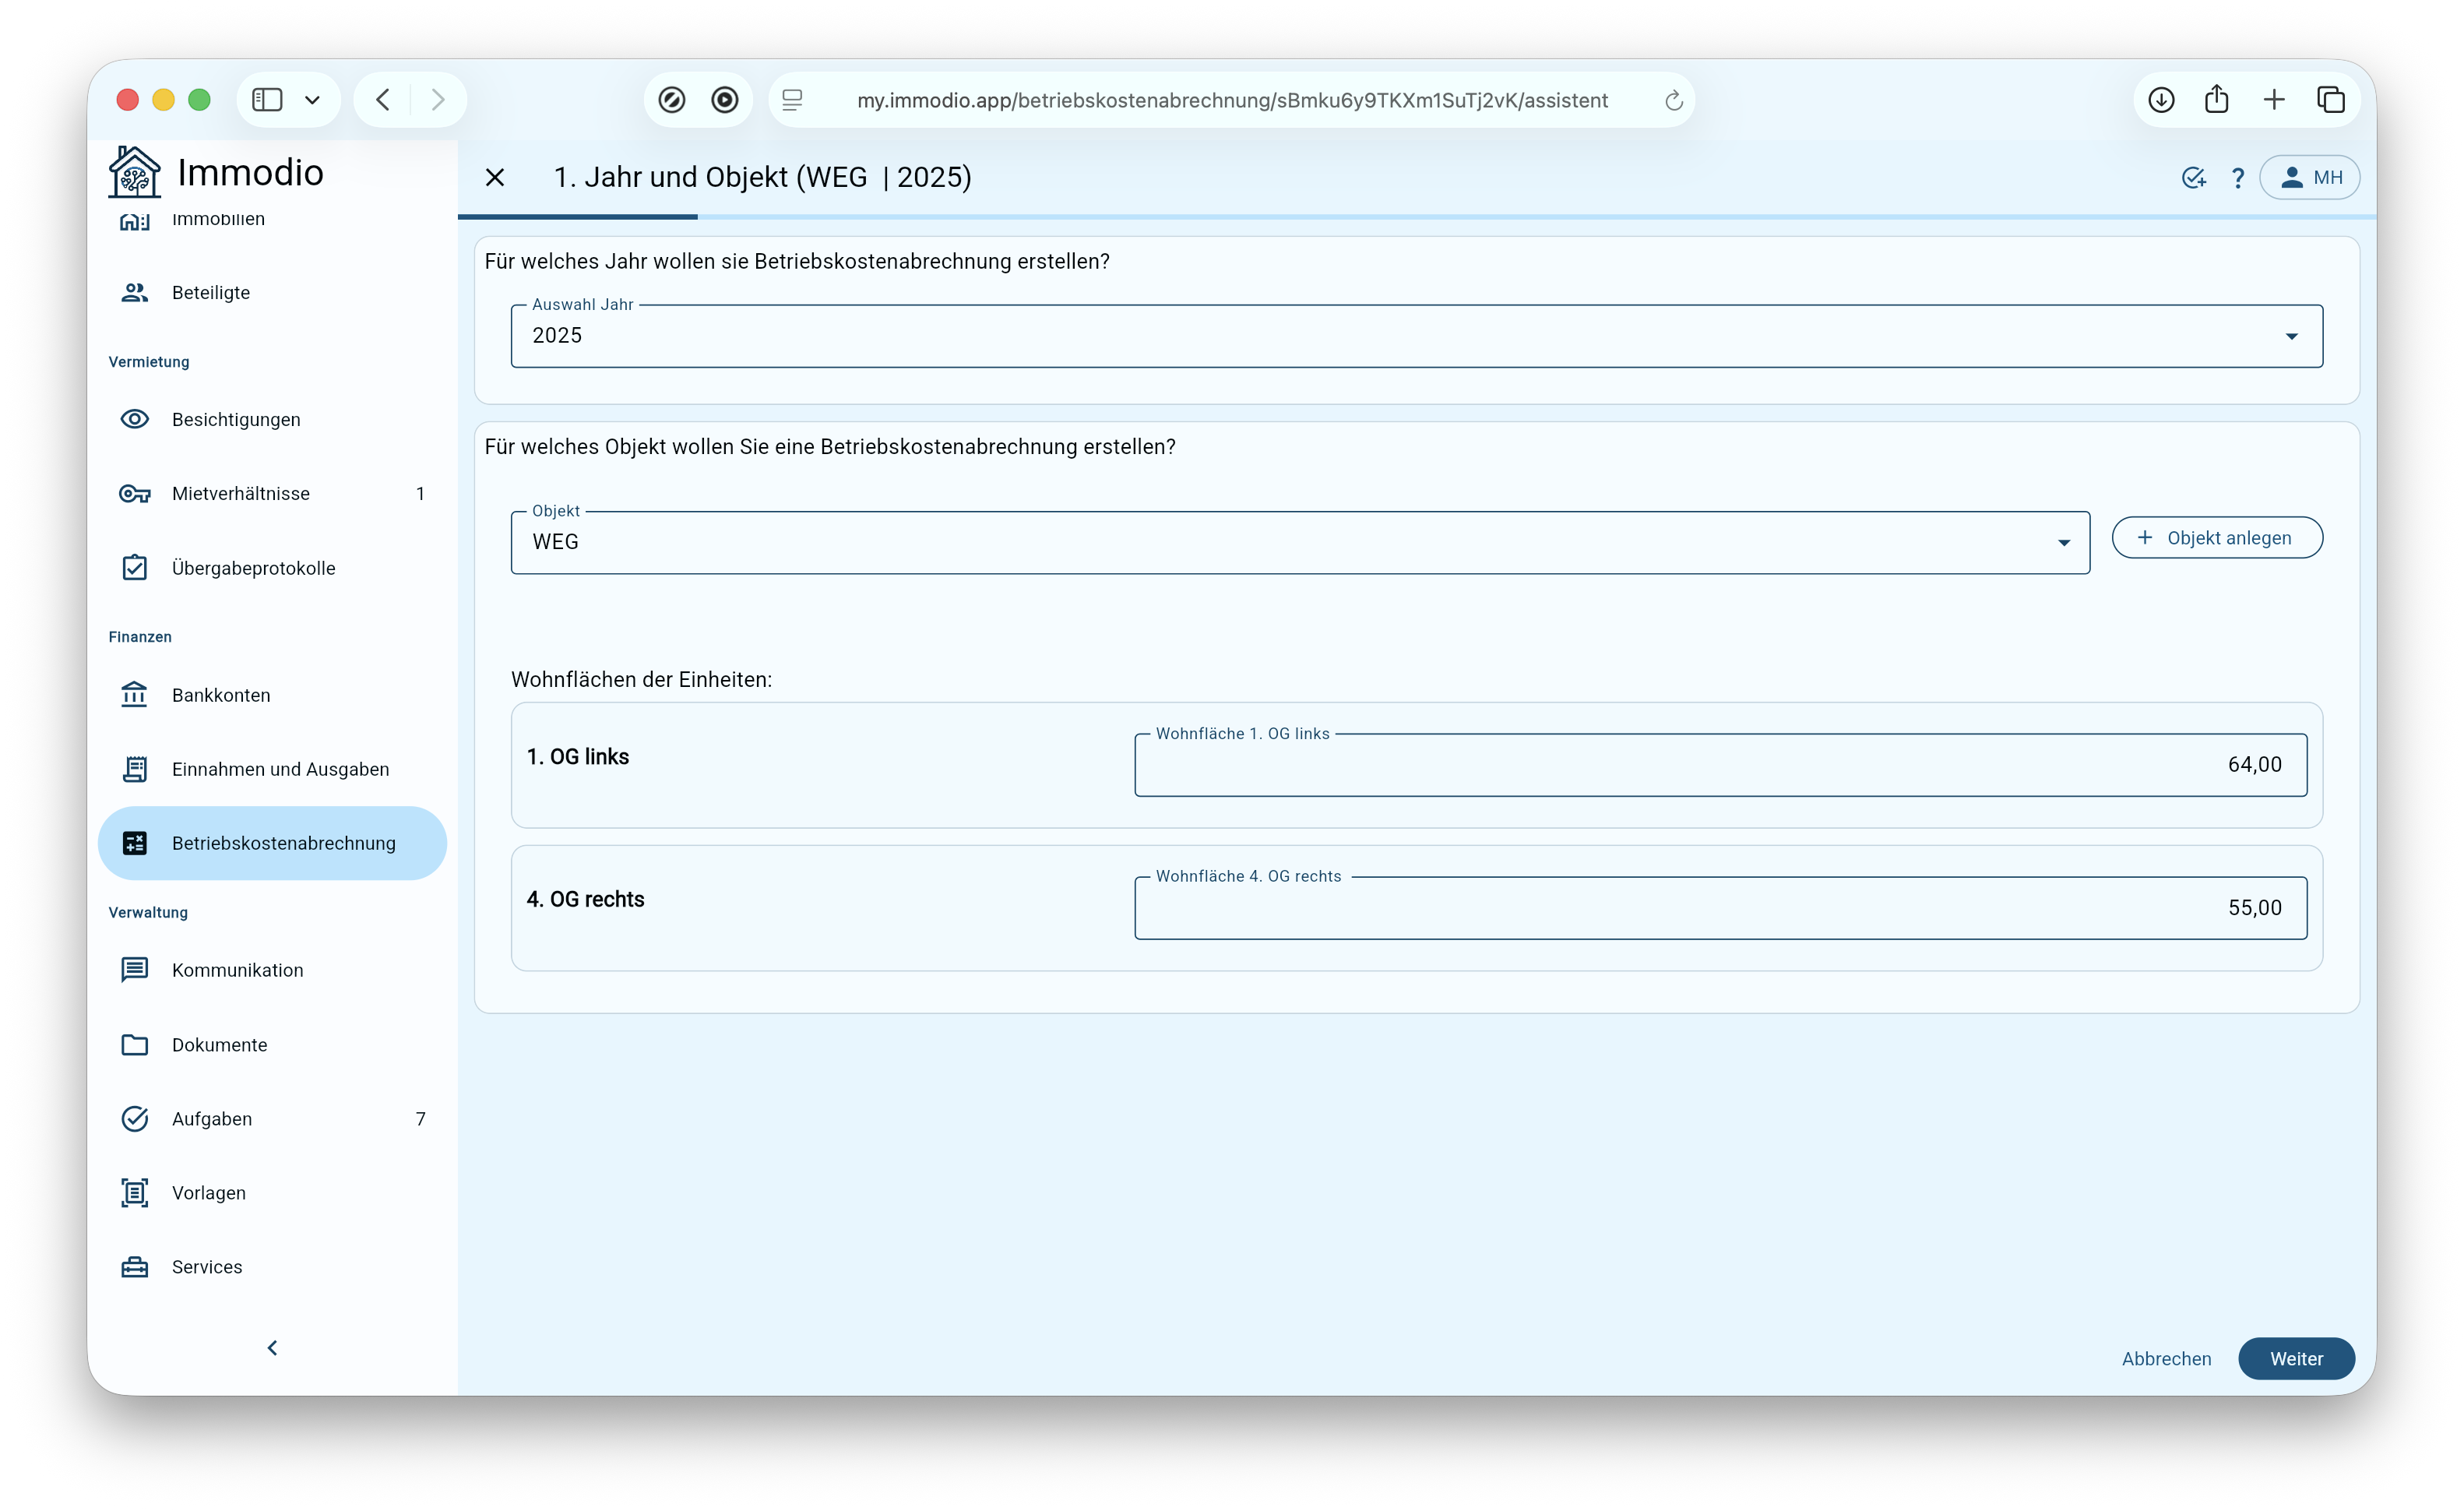
### Selecting the year and the property
Create a new operating cost statement and select the billing year and the WEG property. Immodio shows you the property's units. Check that the unit concerned is stored correctly and that the living space is right.
{% endstep %}
{% step %}
### The settings of the operating cost statement
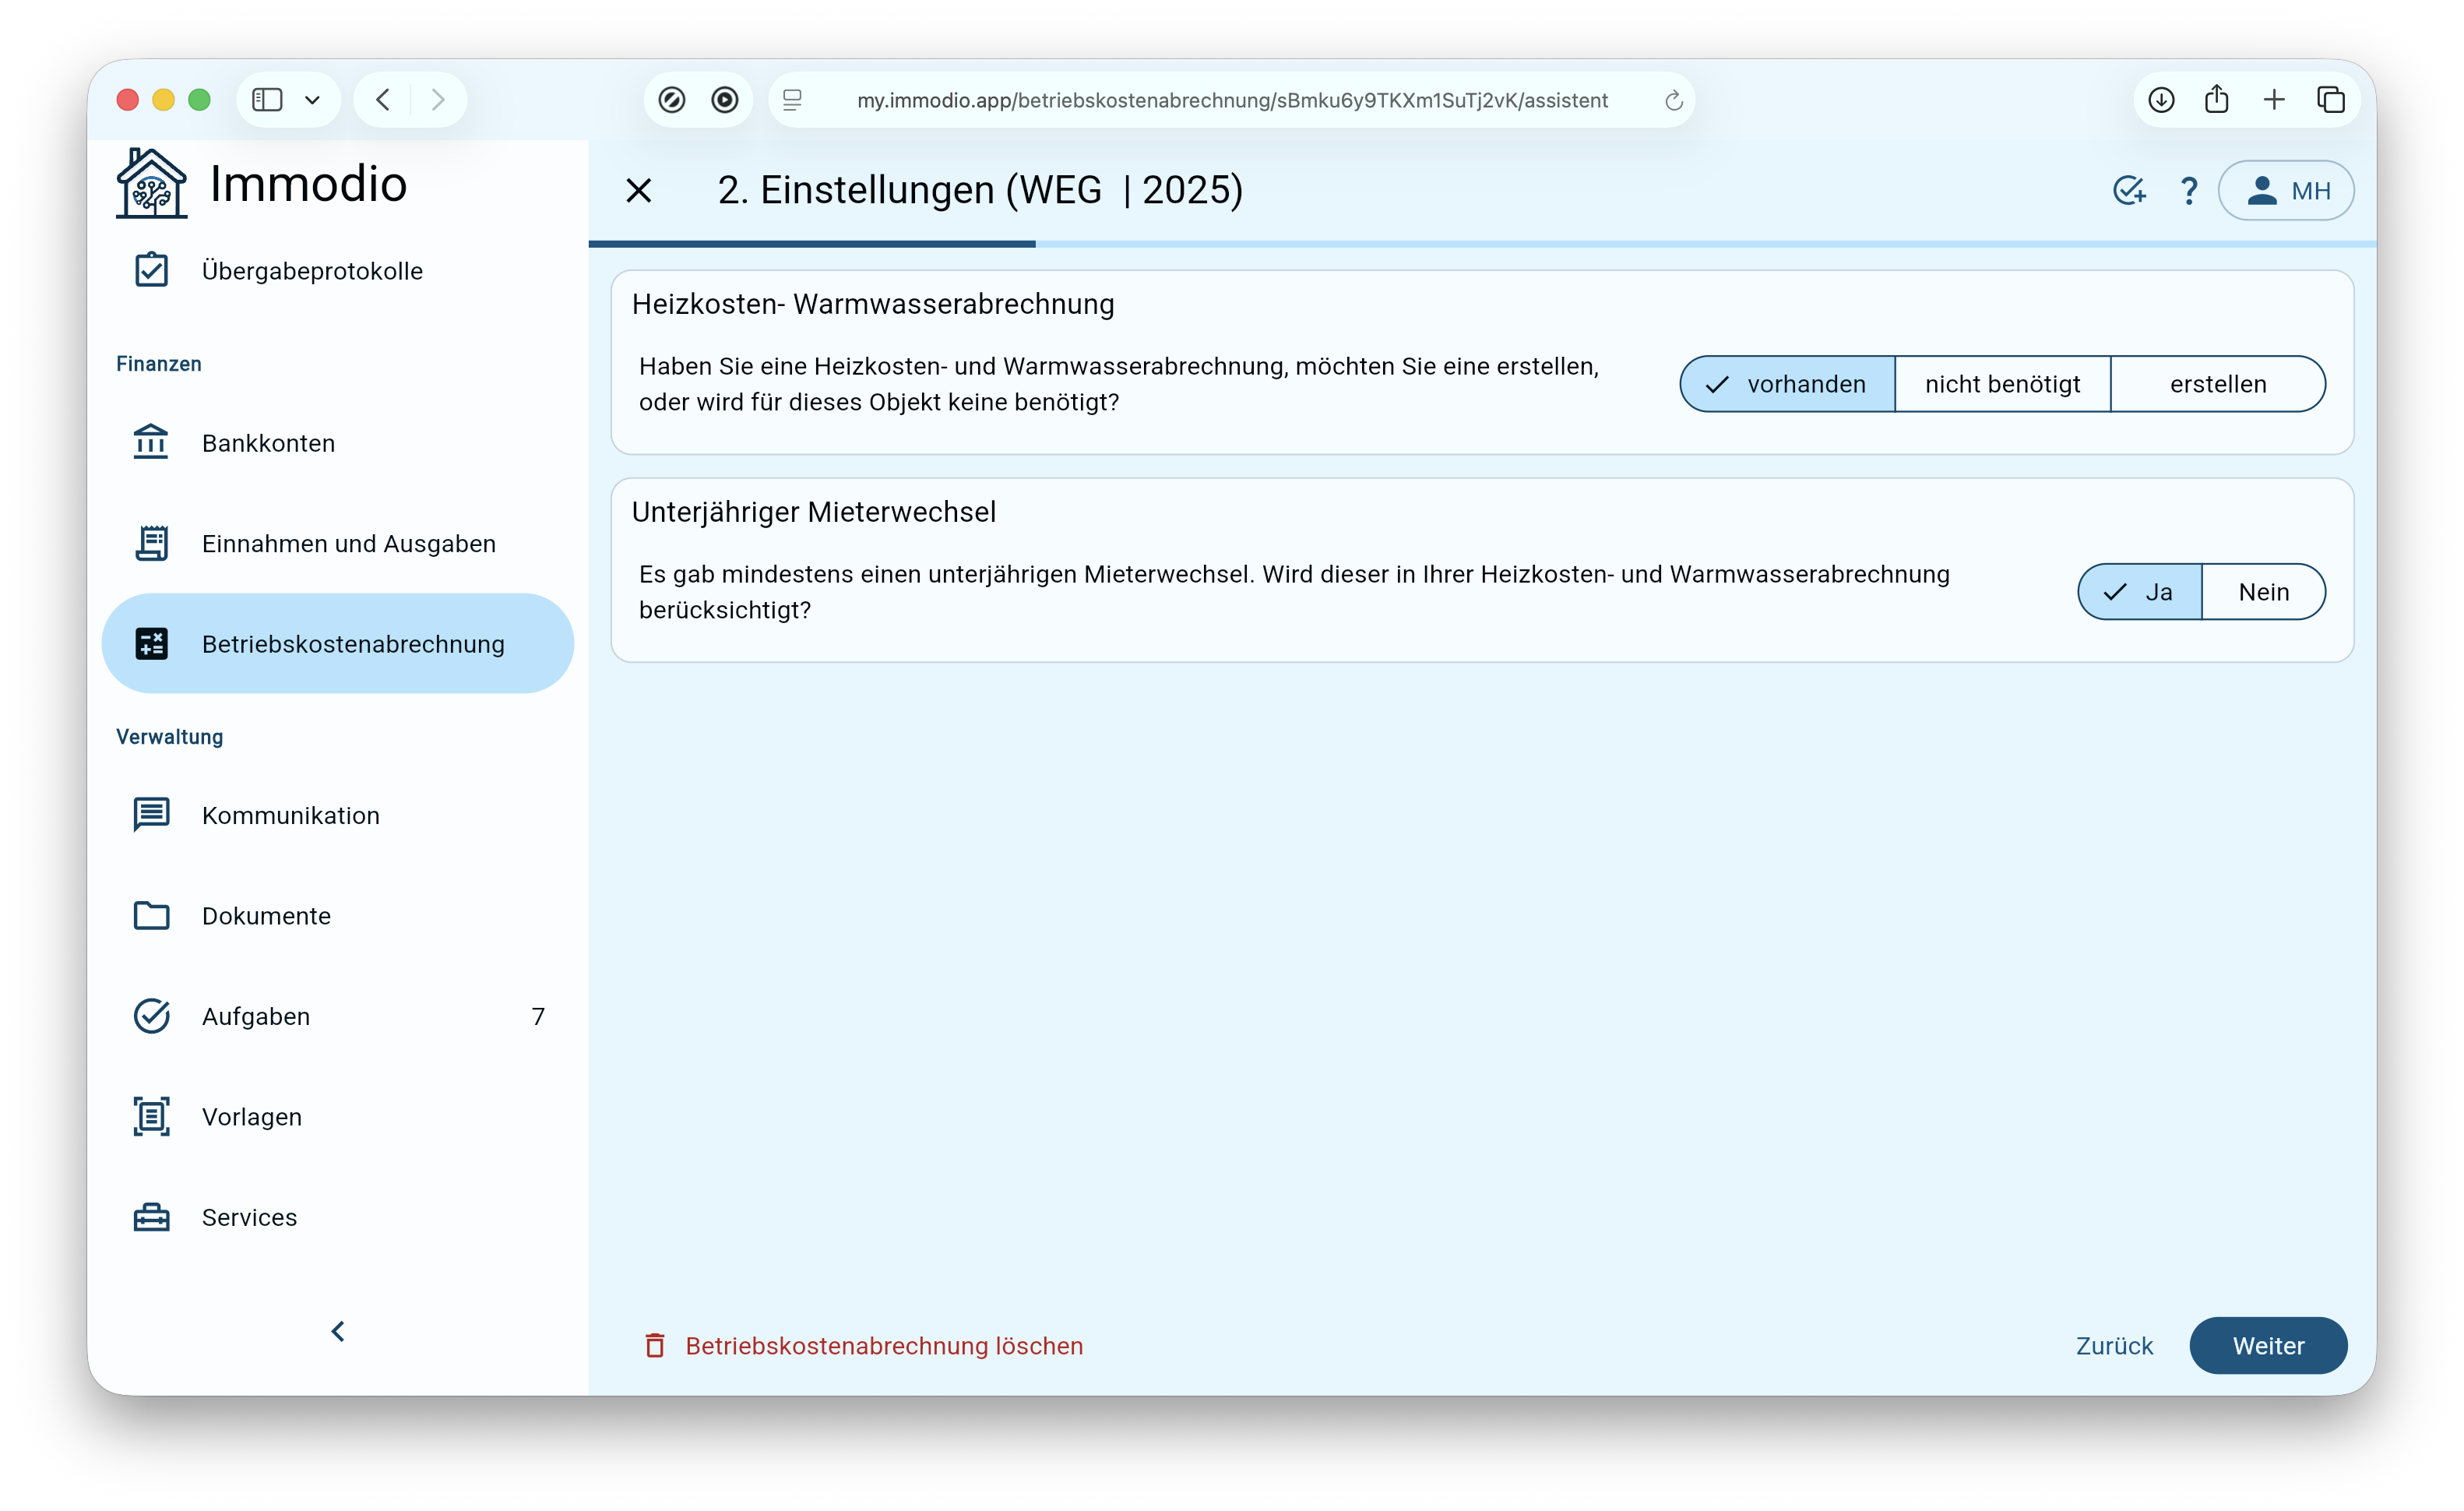
With a WEG a heating and hot water statement is usually prepared by the WEG management. Where that is the case, in step 2 "[**Settings**](/en/anleitung/betriebskostenabrechnungen/einstellungen-fur-die-bka.md)" of the operating cost statement you can select that a heating and hot water statement is already available.
Where you state that an external heating and hot water statement is already available, Immodio automatically checks whether there was a **change of tenant** during the selected settlement period. Note whether your change of tenant was already taken into account in the WEG's heating and hot water statement (this is usually the case).
{% hint style="info" %}
If a change of tenant was not taken into account, you have to prepare the heating and hot water statement yourself in Immodio. You can find further information on this [**here**](/en/anleitung/betriebskostenabrechnungen/heiz-und-warmwasserverbrauch.md).
{% endhint %}
{% endstep %}
{% step %}
### Recording entries for the heating costs from the WEG statement
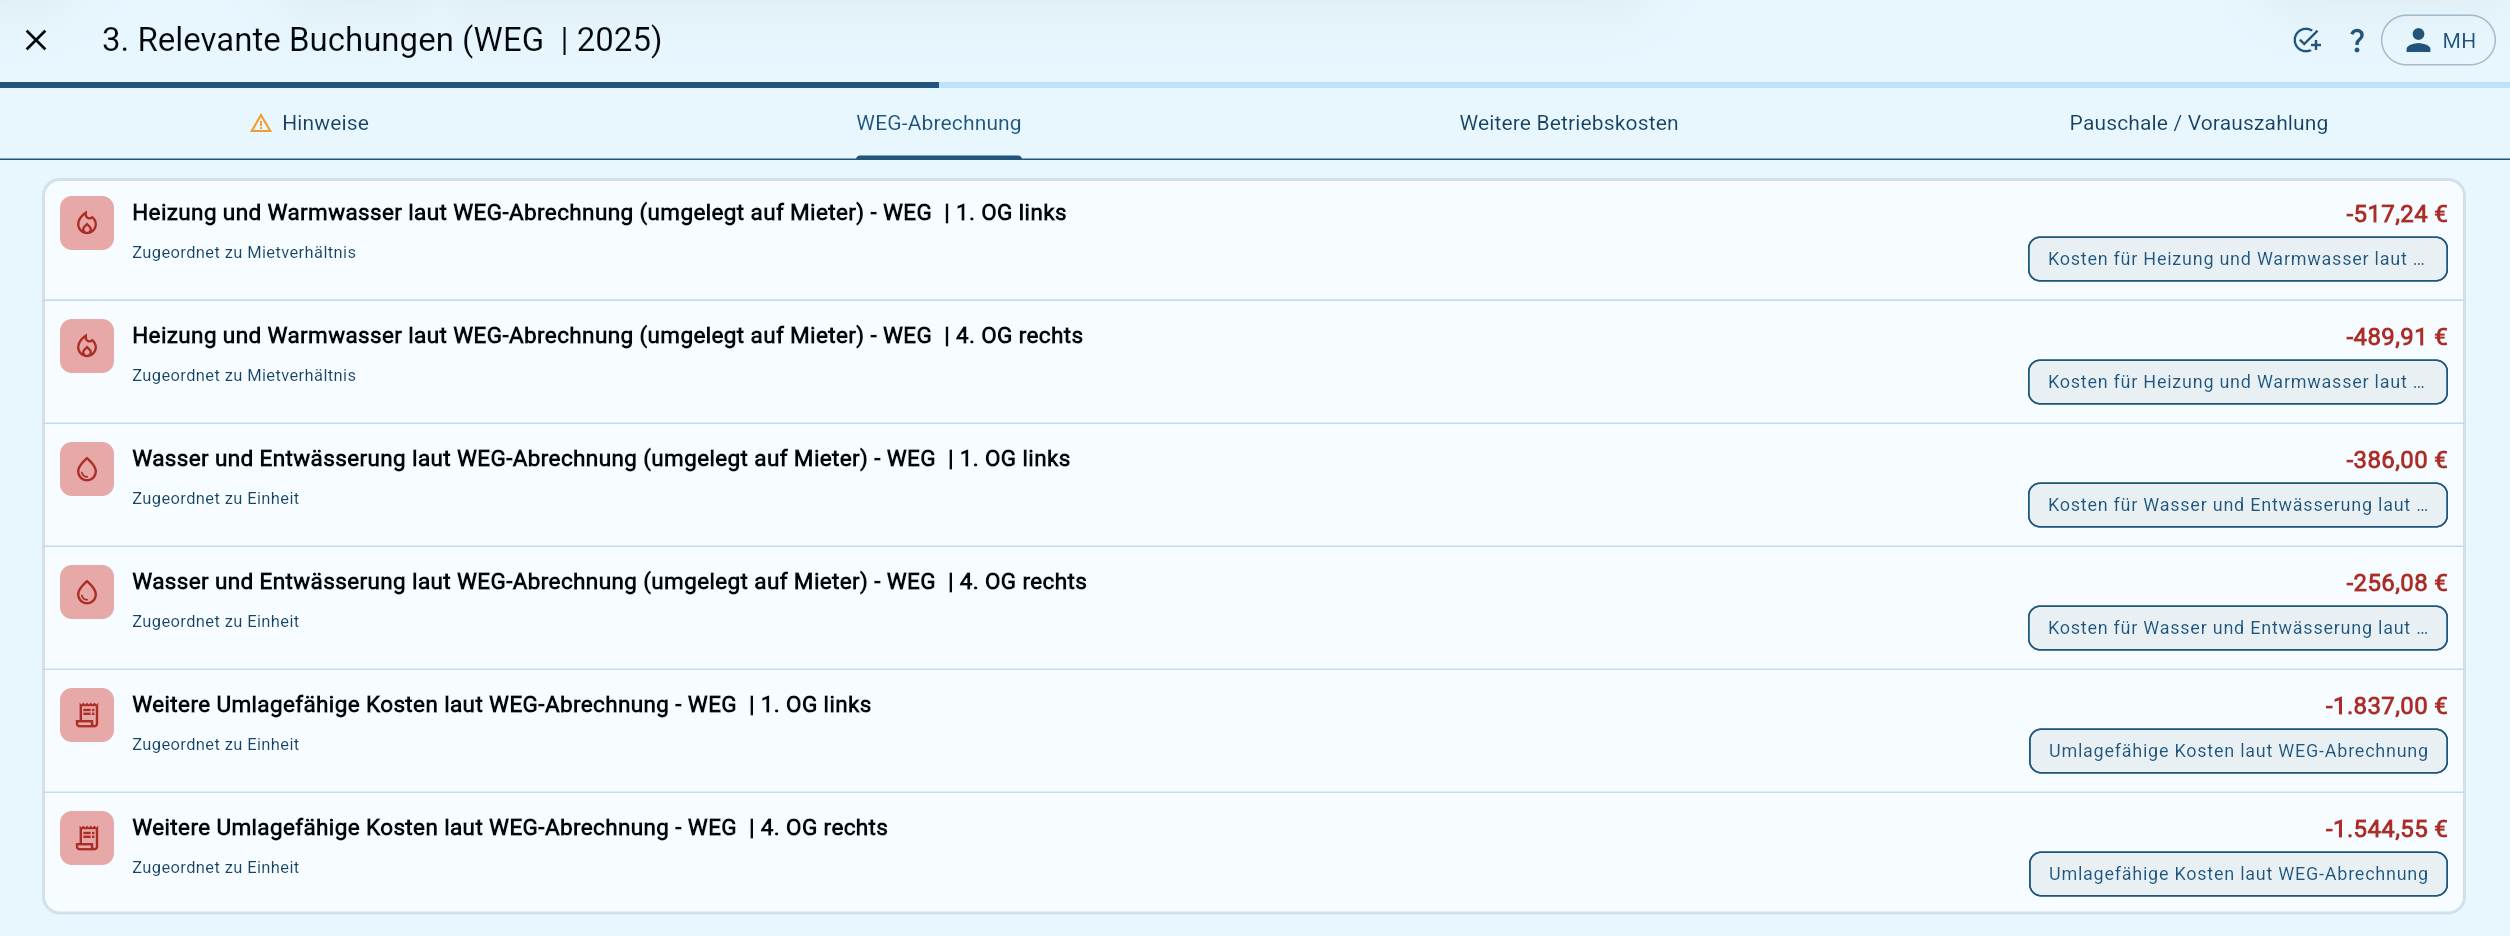
In the step "**3. Relevant entries**" now record the heating and hot water costs listed in the individual WEG statement as expenses. Use the following categories in Immodio for this:
#### **a) Where the WEG property has central heating**
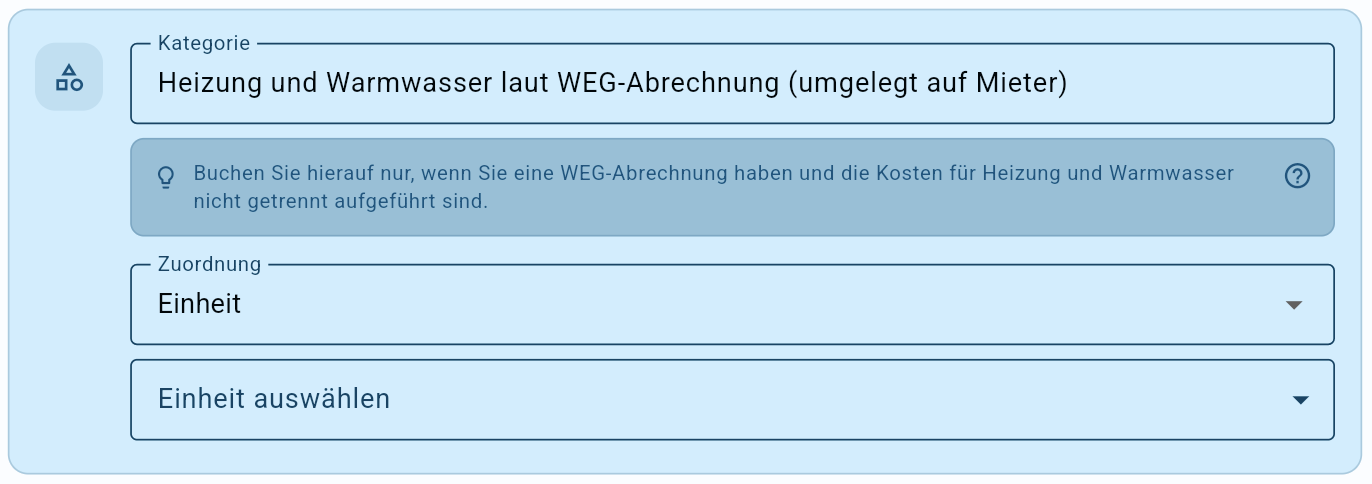
Heating and hot water according to the WEG statement
Use this category where the unit let is part of an **owners' association (WEG)** and you already have a finished **WEG statement** or service charge statement.
Enter the costs for **heating and hot water** here where the property has central heating and the costs for **heating and hot water** are therefore shown **together** in the WEG statement.
#### What can be entered here?
Only enter the share that, according to the WEG statement, is **attributable to your unit let** and relates to **heating and hot water**.
This can include, for example:
* heating costs
* hot water costs
* fuel or energy costs
* maintenance and cleaning of the heating system
* the costs of recording consumption, billing or metering services
* other running costs of the central heating and hot water supply
#### Assignment
For the assignment select **"Unit"** where **no** change of tenant took place in the unit during the settlement period, or **"Tenancy"** where a change of tenant took place during the settlement period.
#### When this category should not be used
Do not use this category where the WEG statement shows heating costs and hot water costs separately.
In that case enter the amounts separately in the appropriate categories:
* **Heating according to the WEG statement**
* **Hot water according to the WEG statement**
#### **b) Where the WEG property has separate systems for heating and hot water**
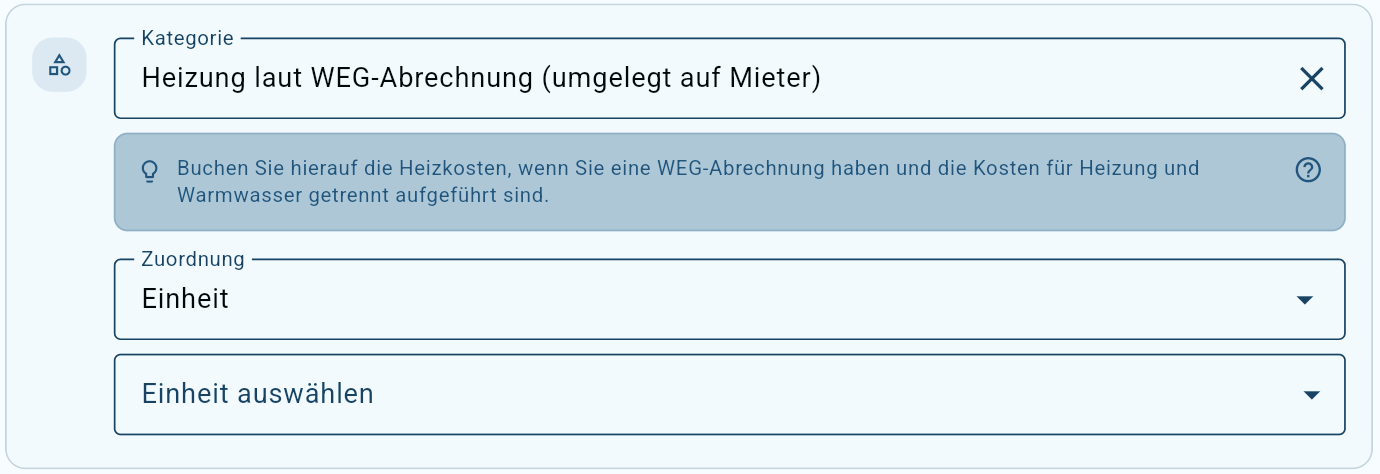
Heating according to the WEG statement
Use this category where the unit let is part of an **owners' association (WEG)** and you already have a finished **WEG statement** or service charge statement.
Enter only the **heating costs** here where they are shown in the WEG statement **separately from the hot water costs**. That is typically the case where the property has separate systems for heating and hot water production, the WEG management has already allocated the costs for heating and hot water to your unit and a separate amount for the heating is stated in the statement.
#### What can be entered here?
Only enter the share that, according to the WEG statement, is attributable to your unit let and relates to the **heating**.
This can include, for example:
* heating costs according to the WEG statement
* fuel or energy costs for the heating
* maintenance, cleaning or operation of the heating system
* the costs of metering services, recording consumption or heating cost statements
* other running costs of the heat supply
#### Assignment
For the assignment select **"Unit"** where **no** change of tenant took place in the unit during the settlement period, or **"Tenancy"** where a change of tenant took place during the settlement period.
#### When this category should not be used
Do not use this category where heating and hot water are **not shown separately** in the WEG statement. In that case enter the combined amount in the category **"Heating and hot water according to the WEG statement"**.
Where a separate amount for hot water is shown in addition to the costs of the heating, do not enter it here but in the category **"Hot water according to the WEG statement"**.
Hot water according to the WEG statement
Use this category where the unit let is part of an **owners' association (WEG)** and you already have a finished **WEG statement** or service charge statement.
Enter only the **hot water costs** here where they are shown in the WEG statement **separately from the heating costs**. That is typically the case where the property has separate systems for heating and hot water production, the WEG management has already allocated the costs for heating and hot water to your unit and a separate amount for the hot water is stated in the statement.
Where the hot water costs are shown **together with the heating costs** in the WEG statement, use the category "[Heating and hot water according to the WEG statement (recoverable from tenant)](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10076000-heizung-und-warmwasser-laut-weg-abrechnung-umgelegt-auf-mieter.md)".
#### What can be entered here?
Only enter the share that, according to the WEG statement, is attributable to your unit let and relates to the **hot water supply**.
This can include, for example:
* hot water costs according to the WEG statement
* the costs of heating the water
* the pro rata energy costs for producing the hot water
* maintenance, cleaning or operation of the hot water supply system
* the costs of metering services, recording consumption or statements
* other running costs of the central hot water supply
#### Assignment
For the assignment select **"Unit"** where **no** change of tenant took place in the unit during the settlement period, or **"Tenancy"** where a change of tenant took place during the settlement period.
#### When this category should not be used
Do not use this category where heating and hot water are shown **together** in the WEG statement and there is no separate amount for hot water.
In that case enter the combined amount in the category **"Heating and hot water according to the WEG statement"**.
Where a separate amount for heating is shown in addition to the costs of the hot water, do not enter it here but in the category **"Heating according to the WEG statement"**.
{% endstep %}
{% step %}
### The costs of water and drainage according to the WEG statement
In the next step you enter the costs listed in the WEG statement that were recorded as part of the statement for **water and waste water/drainage**.
Use the following category in Immodio for this:
Water and drainage according to the WEG statement
Use this category where the unit let is part of an **owners' association (WEG)** and you already have a finished **WEG annual statement** or service charge statement.
Enter here the costs for **water and drainage** shown in the WEG statement for the unit let which are to be recovered from the tenant as part of the operating cost statement.
This can include, for example:
* fresh water / cold water
* foul water / waste water
* drainage
* sewer charges
* precipitation water, where it is shown in the WEG statement together with water and drainage
#### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
{% endstep %}
{% step %}
### Entering the remaining recoverable costs according to the WEG statement
Having entered the costs for heating and hot water and the costs for water and drainage, in the next step enter the sum of all the remaining costs listed as recoverable costs in the WEG statement in the category "**Other recoverable costs according to the WEG statement**".
{% hint style="info" %}
It is **not** necessary to list the items individually, because at the end, when providing the operating cost statement, you can attach the WEG statement digitally as a document to your tenancies.
{% endhint %}
To enter the remaining recoverable costs according to the WEG statement, use the following category in Immodio:
Other recoverable costs according to the WEG statement
Use this category where your unit let is part of an owners' association (WEG) and you want to record the **other recoverable operating costs from the WEG statement** in Immodio.
Only the costs that can be recovered from the tenant according to the WEG statement are taken into account here.
#### What can be entered here?
Enter here the sum of the other recoverable costs shown in the WEG statement for the respective unit.
This can include, for example:
* caretaker costs
* building cleaning
* garden maintenance
* communal electricity
* refuse collection and street cleaning
* lift costs
* building and liability insurance
* other recoverable operating costs according to the WEG statement
**Do not record heating and hot water costs or water and waste water costs in this category**, as there are separate categories for costs according to the WEG statement for them.
#### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
#### When this category should not be used
Only enter **recoverable operating costs from the WEG statement** here.
The following in particular do not belong in this category:
* contributions to the maintenance reserve
* maintenance and refurbishment costs
* repair costs
* administrative costs
* other non-recoverable costs of the WEG
* costs you incurred additionally, independently of the WEG statement
Record additional recoverable operating costs that are **not part of the WEG statement** separately through the appropriate entry category.
{% endstep %}
{% step %}
### Entering all non-recoverable costs according to the WEG statement
In the next step enter the sum of all the costs listed as **not** **recoverable** in the WEG statement in the category "**Non-recoverable costs according to the WEG statement**". You can also enter the non-recoverable items of the WEG statement in Immodio for the [**DATEV export**](/en/anleitung/einnahmen-und-ausgaben/datev-export.md) to your tax adviser. You may **not**, however, recover them through the operating costs, so the "**Recoverable in the operating cost statement**" button has to be **disabled**.
Here too, similarly to the previous step for the recoverable entries, not all items have to be entered individually. It is sufficient to enter the sum of all items in the following category:
Non-recoverable costs according to the WEG statement
### Non-recoverable costs according to the WEG statement
Use this category where your unit let is part of an owners' association (WEG) and you want to record the **costs from the WEG statement that are not recoverable from the tenant** in Immodio.
These costs remain with the owner and are not passed on to the tenant as recoverable operating costs, but they can be entered in Immodio for the [**DATEV export**](/en/anleitung/einnahmen-und-ausgaben/datev-export.md) to your tax adviser.
#### What can be entered here?
Enter here the amount shown in your WEG statement for the unit concerned as **non-recoverable costs**.
This can include, for example:
* the manager's costs or the remuneration of the WEG management
* account management and other administrative costs
* the costs of the owners' meeting
* maintenance and refurbishment costs
* repair costs to the communal property
* non-recoverable shares of caretaking, maintenance or other service provider costs
* other costs expressly shown as non-recoverable in your WEG statement
Take the **share attributable to your unit** from the WEG statement.
#### Enter the maintenance reserve separately
**Do not enter contributions to the maintenance reserve in this category.**
Use the separate category **"Contribution to the maintenance reserve according to the WEG statement"** for that.
#### Assignment
These costs are assigned in Immodio either to the property or to the **owner**. Under **"Assignment"**, therefore, select either the property for which the WEG statement was prepared or the owner to whom the WEG statement relates.
**Then enter the service charge you pay monthly in the following category:**
The WEG's service charge
Use this category for the **monthly service charge payments to your owners' association.**
#### What can be entered here?
Enter here the **full advance service charge payment** you make to the WEG for the respective freehold apartment. This is usually the monthly advance payment set by the WEG on the basis of the business plan.
{% hint style="warning" %}
**Enter the total amount actually paid and do not deduct any individual components from it.** That also applies to the share of the service charge payment that goes to the maintenance reserve.
{% endhint %}
Example: where your monthly service charge is **€350**, enter **€350** per month in this category. The later split into recoverable costs, non-recoverable costs and the maintenance reserve is made separately on the basis of the WEG annual statement.
#### Why should the service charge be maintained on a running basis?
The running service charge payments reflect the **advance payments actually made to the WEG**.
After the end of the billing year these advance payments are compared with the WEG annual statement. Where the statement gives a higher or lower amount, this can result in an **additional payment or a credit balance** with the WEG.
So that this comparison and the [**DATEV export**](/en/anleitung/einnahmen-und-ausgaben/datev-export.md) to your tax adviser can be made correctly, the service charge payments should be maintained in full in Immodio.
#### Assignment
For the assignment select **"Unit"** and then the freehold apartment for which the service charge was paid.
Where you own several freehold apartments within a WEG, record the service charge payments separately for each unit accordingly.
#### When this category should not be used
Do not enter here:
* additional payments or credit balances from the WEG annual statement,
* individual recoverable costs according to the WEG statement,
* non-recoverable costs according to the WEG statement,
* the separate contribution to the maintenance reserve according to the WEG statement,
* the WEG's use of the maintenance reserve,
* special payments for which a more suitable category is provided in Immodio.
{% hint style="info" %}
**Info:** Entries you create in these two categories are not shown in the operating cost statement, because they are not relevant to operating costs. You will find these entries under "[**Income and expenditure**](/en/anleitung/einnahmen-und-ausgaben.md)" accordingly.
{% endhint %}
{% endstep %}
{% step %}
### Entering other operating costs
Where, in addition to the items already contained in the WEG statement, you personally incurred further recoverable operating costs, you can also record these in Immodio and take them into account in the operating cost statement.
{% hint style="warning" %}
Make sure you only record costs that were **not already taken into account through the WEG statement**, so that they are not billed twice.
{% endhint %}
Typical costs that can arise in addition to the WEG statement are, for example:
Property tax (recoverable from tenant)
Use this category for the **property tax paid** which was incurred for the individual freehold apartment.
Property tax is a recoverable operating cost. Section 2 no. 1 BetrKV expressly names it as part of the "running public charges on the land". Recovering it from the tenant requires the allocation of operating costs to have been agreed in the rental agreement.
#### What can be entered here?
Enter the property tax here in accordance with the property tax assessment from the municipality or city.
That can be, for example:
* a quarterly payment of the property tax
* the property tax for a single freehold apartment
* the property tax for a unit let within a WEG
{% hint style="info" %}
Since 2025 property tax has been levied under new rules and new municipal multipliers. For settlement periods from 2025 onwards, therefore, use the current property tax assessment.
{% endhint %}
#### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
#### Important
Only enter the property tax here. The following, for example, do **not** belong in this category:
* real estate transfer tax
* reminder fees, late payment penalties or surcharges for late filing
* the costs of appeals, tax advice or legal advice
Maintenance, tradesmen, repairs to technical systems and machinery (recoverable from tenant)
Use this category exclusively for the **costs of a small repair** which the tenant concerned has to bear on the basis of an effective small repairs clause in the rental agreement.
In principle the landlord is obliged to keep the rented property in a condition suitable for use in accordance with the contract during the tenancy. Repair and maintenance costs are also **not** operating costs and may therefore not be allocated through the ordinary annual operating cost statement. The tenant assuming the costs only comes into consideration on the basis of a separate and effective small repairs provision in the rental agreement, which is governed by Section 13 of the Immodio rental agreement.
### What can be entered here?
Only enter the actual costs of a smaller repair to an item here where that item
* is part of the apartment let,
* is subject to the tenant's frequent and direct access,
* has repair costs that lie entirely within the contractual maximum amount per repair,
* and where the contractual annual maximum has not yet been exhausted.
Depending on the rental agreement and the specific case, repairs to the following items, for example, can be recorded:
* taps and mixer taps,
* the controls of a toilet flush,
* light switches and sockets,
* door handles, door locks and closing devices,
* window handles and window catches,
* the controls of roller shutters or blinds,
* radiator thermostats and heating valves operated by the tenant,
* the controls of a cooker let with the apartment or of other cooking equipment let with it.
{% hint style="info" %}
The Federal Court of Justice allows small repairs clauses only for items that the tenant frequently operates themselves or whose wear they can influence through regular use. The underlying case law names as examples installation items for electricity, water and gas, heating and cooking equipment and window and door catches.
{% endhint %}
### What does "frequent and direct access" mean?
It is not sufficient that an item is merely located within the apartment. The tenant has to touch, operate or use the component concerned regularly.
A radiator thermostat, for example, is operated directly by the tenant. The pipes running inside the radiator or in the wall, on the other hand, are not subject to their direct access. The same applies to a light switch as opposed to the electrical wiring behind it.
With technical devices a distinction therefore has to be made between the accessible control element and the internal technical components. The control knob of a cooker let with the apartment can in principle come into consideration; the internal electronics, the heating element or the device control, on the other hand, may not in the individual case.
### The conditions for an effective small repairs clause
A standard form small repairs provision has to meet several conditions at the same time:
1. **A limitation as to the items covered**\
The clause may only cover items subject to the tenant's frequent direct access.
2. **A maximum amount per individual repair**\
The rental agreement has to state clearly up to what amount an individual small repair is borne by the tenant.
3. **A maximum burden within a particular period**\
The contract also has to limit the total burden that may arise for the tenant within a calendar year, for example.
4. **Only assumption of costs, no obligation to repair**\
A standard form rental agreement may in principle only impose the bearing of costs on the tenant. They may not be obliged to carry out the repair themselves or to engage a tradesman on their own.
{% hint style="info" %}
Where one of these conditions is missing, the whole small repairs clause can be invalid. Standard form clauses that are unclear or unreasonably disadvantageous do not withstand the review of content under Section 307 BGB.
{% endhint %}
### Exceeding the maximum amount per repair
Where the actual costs of a repair exceed the contractual maximum amount per repair, in principle a partial amount up to the agreed limit may not simply be charged to the tenant.
The Federal Court of Justice has held a standard form provision invalid under which a tenant was to contribute to larger repairs as well, merely up to the small repairs maximum amount. The specific repair itself has to remain a small repair and be below the agreed limit overall.
**Example:**
The rental agreement provides for a maximum amount per repair of 120 euros.
* Total repair costs: 95 euros → the tenant assuming the costs can be possible where all the other conditions are met.
* Total repair costs: 580 euros → 120 euros may not simply be applied as the tenant's share.
The complete specific repair invoice should be considered for the assessment.
### Monitoring the annual maximum
Even where several individual repairs are each below the maximum amount per repair, the annual total burden set out in the contract may **not** be exceeded.
For each tenancy, therefore, keep a comprehensible overview with:
* the date of the repair,
* the item concerned,
* the full invoice amount,
* the amount charged to the tenant,
* small repairs already charged within the year,
* the remaining annual maximum.
{% hint style="info" %}
For this you can use the comment function in the tenancy directly, for example, or record comments through the [comment function in the defect identified and to be repaired](/en/anleitung/immobilien/mangel/mangel-anlegen.md#working-with-defects).
{% endhint %}
### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
Small repair costs generally do not concern several tenancies. The entry is therefore to be assigned exclusively to the tenant whose rental agreement contains an effective small repairs clause and whose rented rooms or accessible facilities are affected.
Before making the assignment, check:
* whether the rental agreement (not created by Immodio) contains a small repairs clause and whether that clause is effectively worded,
* whether the item concerned is covered by the clause,
* whether the maximum amount per repair is observed,
* whether the annual maximum has not yet been exceeded.
{% hint style="info" %}
The entries made here are listed separately under the "Very small repairs" category in the finished operating cost statement.
{% endhint %}
### When this category should not be used
The following repairs in particular do not belong in this category, repairs to:
* central heating and hot water systems,
* boilers, burners and heat pumps,
* pumps, motors or central control units,
* water, gas and heating pipes,
* electrical wiring under the plaster,
* fuse boxes and sub-distribution boards,
* central ventilation or air conditioning systems,
* building services in communal areas,
* roofs, facades or load-bearing components,
* communal doors and gate systems,
* technical facilities the tenant cannot operate directly.
The following also do not belong here:
* new purchases,
* modernisation,
* repairs above the maximum amount per repair,
* repairs after the annual maximum has been exceeded,
* costs arising from an invalid or missing small repairs clause.
{% hint style="info" %}
The tenant contributing to new purchases or larger repairs cannot become permissible by limiting the amount to the small repairs maximum.
{% endhint %}
### Do not mix maintenance and repairs
Regular maintenance and remedying a specific defect are different services:
* **Maintenance** serves to preserve operational readiness.
* **A repair** restores a function that is already impaired or has failed.
Where an invoice contains both maintenance and repair services, have them shown separately if possible.
### Damage caused by the tenant
Where the tenant damaged an item culpably, this is not an ordinary small repair. An individual claim for damages then comes into consideration.
Normal changes and deterioration as a result of **use in accordance with the contract**, on the other hand, are not the tenant's responsibility. Damages generally require a breach of duty for which the tenant is responsible.
Examples of possible damages cases are:
* a door damaged by force,
* a switch destroyed by improper use,
* a window handle broken off as a result of gross misuse,
* a device damaged by a foreign object introduced by the tenant.
{% hint style="info" %}
Such claims should **not** be entered as a blanket small repair. Instead, document the damage, the cause, responsibility, the age of the item, the invoice and, where applicable, a deduction for wear already present, and check your right to an individual claim for damages.
{% endhint %}
### Documents for the statement
Keep in particular:
* the tradesman's invoice and proof of payment,
* a description of the defect,
* details of the item concerned,
* photos, where applicable,
* evidence of the full repair amount,
* the check of the maximum amount per repair,
* an overview of the annual burden so far,
* the calculation of the amount assigned to the tenant,
* correspondence about the defect report.
Internet (recoverable from tenant)
Use this category where the landlord provides internet access for one or more tenants and the costs are borne by the participating tenants on the basis of a **separate contractual agreement**.
#### An important legal note
Since **1 July 2024** the running monthly charges for broadband, cable or internet connections may in principle **no longer be allocated to all tenants through the operating cost statement**. The former ancillary cost privilege has ended. The tenant pays for their internet connection either directly to a provider of their own choice or to the landlord on the basis of their own contract. This generally requires a **separate and transparent agreement on the internet supply**.
#### What can be entered here?
Costs arising from an agreed internet supply for the tenants in particular can be recorded here, for example:
* the running fees of an internet provider,
* a tenant's contractually agreed share of a shared internet connection,
* agreed charges for internet access provided by the landlord,
* contractually agreed rental costs for routers or other access technology,
* other running charges that clearly belong to the agreed internet supply for the tenants.
#### The conditions for passing the costs on
The internet supply and the charge to be paid for it should be agreed clearly. The agreement should show at least:
* which internet service is provided,
* how high the charge is,
* which tenants take part in the supply,
* which contract term and notice period apply,
* whether additional costs arise, for a router for example.
{% hint style="info" %}
Where the landlord provides internet or other telecommunications services themselves in connection with the tenancy and charges the tenants for them, they generally have to observe the consumer protection provisions of the German Telecommunications Act. These include requirements on contract information, contract terms, termination, service failures and changing provider.
{% endhint %}
#### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
#### When this category should not be used
Do not use this category for:
* the landlord's private or business internet connection,
* internet costs for the office or the property management,
* the landlord's telephone or mobile contracts,
* internet costs of a vacant unit that cannot be effectively passed on to a tenant,
* repairs or the purchase of new routers, cables and other network technology, as far as these costs are not expressly part of a permissible separate service agreement.
{% hint style="info" %}
The landlord's own internet costs are recorded in the category **"Internet (not recoverable from tenant)"**.
{% endhint %}
Chimney cleaning, chimney sweep, cleaning the flue system (recoverable from tenant)
Use this category with a **freehold apartment** where you incurred chimney sweep or flue system costs that are specifically attributable to your unit and are **not** already contained in the WEG statement or an existing heating cost statement.
That is relevant in particular for apartments with **their own fireplace or heating system**.
Typical cases are, for example:
* gas floor heating or a gas boiler within the apartment,
* an individual gas fireplace,
* a fireplace or wood-burning stove,
* a tiled or masonry stove,
* a pellet or other solid fuel stove,
* a gas-fired hot water device with a flue connection serving the apartment exclusively.
Even where the building generally has **central heating**, this category can be necessary. That is the case, for example, where there is also a wood-burning stove of its own in the apartment and the chimney sweep costs arising for it are charged to the owner separately.
#### What can be entered here?
Record here **running or regularly recurring chimney sweep costs** that concern exclusively the unit in question or a fireplace present there.
These can include in particular:
* sweeping and cleaning a chimney or flue assigned to the fireplace,
* cleaning flue pipes and connecting pieces,
* flue route inspections,
* checking the combustion air supply and the flue draught,
* carbon monoxide measurements as part of the prescribed inspection,
* measurements prescribed under German federal immission control law,
* running inspections of a gas boiler or individual gas fireplace by the chimney sweep,
* running fireplace inspections and the related charges, as far as these can be assigned to the unit concerned and are recoverable,
* labour and travel costs, as far as they belong directly to the recoverable chimney sweep work.
The exact type and frequency of the work depends on the fireplace present, the fuel used and the technical design of the system.
#### When is this category typically necessary with a freehold apartment?
A frequent case of application is **gas floor heating**.
Whereas with central heating the heating and chimney sweep costs are usually recorded through the association or the heating cost statement, the running costs of a gas boiler or fireplace belonging to the apartment can be incurred directly by the individual owner.
Where, in addition to your WEG statement, you receive a chimney sweep invoice from your chimney sweep for your apartment's gas boiler, for example, the recoverable chimney sweep costs it contains can be recorded here.
The same applies to a fireplace attributable exclusively to the apartment, for example a wood-burning stove. It does not matter whether the apartment is also heated by the building's central heating in addition.
#### Do not enter costs from the WEG statement twice
Before making the entry, check whether the costs are already part of your **WEG statement** or of a **separate heating cost statement**.
Where the chimney sweep costs are already contained in the recoverable costs of the WEG statement, you may **not record them additionally in this category**. Only use this category for costs **invoiced to you separately for the unit concerned outside the WEG statement**.
With a central heating system belonging to the WEG, chimney sweep, flue, cleaning and measurement costs are generally part of the heating costs. These costs may not be entered additionally at unit level either.
#### Maintaining the gas boiler
Distinguish between the chimney sweep invoice itself and a separate maintenance invoice from a specialist heating company.
Where the regular maintenance of the gas boiler was carried out by a heating installer, for example, use the corresponding category for **heating and maintenance costs**.
This category is intended in particular for chimney sweep, sweeping, flue and measurement work.
{% hint style="info" %}
Repairs to the gas boiler or fireplace, on the other hand, are **not** recoverable operating costs.
{% endhint %}
#### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
#### When this category should not be used
Do not use this category for:
* chimney sweep costs of a central heating system that are already taken into account through the WEG or heating cost statement,
* chimney sweep costs that are already part of the recoverable costs entered according to the WEG statement,
* the regular maintenance of a gas boiler by a specialist heating company, where a more suitable heating or maintenance category is available for it,
* repairs to gas boilers, stoves or other fireplaces,
* repairs or refurbishment of chimneys and flue pipes,
* installing or replacing a fireplace,
* the initial acceptance of a newly installed or substantially altered system,
* the costs of remedying defects found,
* re-inspections that became necessary solely because of a defect or a repair.
### Documents for the operating cost statement
Keep in particular:
* chimney sweep invoices,
* the fireplace notice,
* certificates of sweeping and inspections,
* measurement records under the First Federal Immission Control Ordinance,
* evidence of the fireplaces concerned,
* the split where there are several buildings or chimney flues,
* evidence of the assignment to heating or operating costs,
* invoices for any repairs deducted,
* proof of payment.
Advance payments of operating costs have to be billed annually in compliance with the requirement of economic efficiency. The tenant can ask to inspect the underlying receipts.
Other levies and costs (recoverable from tenant)
Use this category only for **costs arising on a running basis** that were incurred specifically for your freehold apartment and may in principle be recovered from the tenants as operating costs but for which there is no more suitable entry category.
{% hint style="warning" %}
The category is **not a general catch-all account for any expenditure by the landlord**. Other operating costs have to meet the conditions of Section 1 BetrKV and may not already be covered by one of the specific types of operating cost in Section 2 nos. 1 to 16 BetrKV. Administrative costs, repairs, refurbishment and acquisition costs remain excluded.
{% endhint %}
### The conditions for allocation
An expense can be recorded in this category where it in principle meets **all** the following conditions:
* It arises from the ownership of the land or the intended use of the building, its systems or its facilities.
* It arises on a running basis or at recurring intervals.
* It serves the proper operation, checking, upkeep or safety of the building.
* It is not a repair, refurbishment, administration or acquisition.
* There is no more suitable category in Immodio for the expense.
* The specific type of cost may be recovered from the tenant under the rental agreement (it was recorded under the [**individual additional agreements**](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/zusatzvereinbarungen.md#individual-agreements), for example).
With **other operating costs under Section 2 no. 17 BetrKV**, the wording "other operating costs" alone is generally not sufficient in a residential rental agreement. The type of cost concerned has to be named as specifically as possible, for example as "the costs of the regular electrical inspection" or "the costs of cleaning the gutters".
### What can be entered here?
Depending on the building's features and the specific provisions of the rental agreement, the following items, for example, might come into consideration in certain circumstances:
#### Regular technical inspections
* recurring inspections of the electrical systems,
* recurring function and safety checks of technical facilities,
* the regular inspection of emergency or safety lighting systems.
The Federal Court of Justice has held that regularly recurring costs for checking the operational safety of an electrical system can be other operating costs. The inspection may not, however, be confused with remedying defects found: the check can be recoverable, the subsequent repair generally not.
#### Fire protection and safety equipment
Depending on the rental agreement and the building, the running inspection and maintenance costs of the following facilities might come into consideration in certain circumstances:
* fire extinguishers,
* smoke and heat extraction systems,
* automatic fire dampers,
* sprinkler or extinguishing systems,
* fire detection and alarm equipment,
* escape route and emergency lighting,
* other safety equipment subject to regular inspection.
Only the running checks, maintenance, cleaning and function tests may be recorded. Buying, initially installing, replacing, repairing or renewing the equipment does **not** belong in this category.
{% hint style="warning" %}
Whether these costs are actually recoverable always has to be checked against the specific content of the service and the rental agreement. As a rule, other costs can only be recorded where they are comparable to running operating costs.
{% endhint %}
### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
Alternatively, in the property's [**"Billing"**](/en/anleitung/immobilien/objekt/abrechnung-objekt.md#individual-allocation-keys) area you can create individual allocation keys.
### When this category should not be used
The following in particular do not belong here:
* property management and bookkeeping costs,
* the costs of preparing the general operating cost statement,
* tax advice and legal advice costs,
* postage, bank and account management fees,
* loan interest and financing costs,
* rent loss or vacancy costs,
* reminder, late payment and enforcement costs,
* fines and contractual penalties,
* repairs and remedying faults,
* spare parts,
* maintenance and refurbishment measures,
* initial purchases and installations,
* modernisation and renewals,
* device rentals that economically replace a purchase,
* one-off expert reports because of damage or a defect,
* the costs of remedying a defect found,
* one-off connection, expansion or development contributions,
* costs serving exclusively the landlord's personal or economic interest.
Administrative, maintenance and repair costs are expressly excluded from operating costs by law. Acquisition and financing costs cannot be shifted to the tenants through the catch-all category "other operating costs" either.
Maintenance of your rental properties (recoverable from tenant)
Use this category for the **regularly arising maintenance, inspection, monitoring, cleaning and care costs of technical systems**, provided the costs are in principle recoverable as operating costs and there is no more suitable entry category in Immodio.
The category may not be used as a general catch-all account for all maintenance and tradesmen's invoices. Only costs that **arise on a running basis** from the ownership or the intended use of the freehold apartment are operating costs. Administrative, maintenance and repair costs are expressly excluded.
### The legal classification
The term **"maintenance"** alone does not yet determine whether an invoice may be recovered from the tenants. What matters is which specific service was provided:
* A regular inspection, cleaning, adjustment or function check can be part of the operating costs.
* Remedying a defect that already exists is generally a repair or refurbishment and therefore **not** recoverable.
* The initial purchase, installation or fundamental renewal of a system is likewise **not** part of the operating costs.
The Federal Court of Justice has expressly held that recurring checks of the functionality and operational safety of a technical system can be operating costs. In the case decided, an inspection of an electrical system carried out on a four-year cycle was recoverable. What was decisive was that the inspection did not serve to remedy a defect that already existed.
### What can be entered here?
This general category comes into consideration in particular for maintenance and inspection costs that **cannot** be assigned to a category already existing in Immodio.
#### Maintaining fire protection and safety equipment
Depending on the building's features and the provisions of the rental agreement, the following, for example, might come into consideration in certain circumstances:
* maintaining and inspecting fire extinguishers,
* maintaining smoke and heat extraction systems,
* checking fire dampers,
* maintaining sprinkler or extinguishing systems,
* checking hold-open devices on fire doors,
* maintaining escape route and emergency lighting,
* checking other communal fire and safety equipment.
{% hint style="info" %}
Only enter the regularly arising inspection, cleaning, adjustment and function check. Purchase, initial installation, repair, replacement and renewal are in principle **not** to be applied as operating costs.
{% endhint %}
Where a separate category already exists, such as **"Maintenance of smoke alarms, no repair or purchase (recoverable from tenant)"**, that category takes precedence.
#### Ventilation and extract air systems
The following might come into consideration in certain circumstances:
* the regular cleaning and function testing of a ventilation system,
* checking and adjusting the system,
* cleaning accessible operational components,
* the regular inspection of fans and controls,
* documenting the maintenance.
Where the system is part of the central heating or hot water supply, its costs may have to be assigned to the **"heating or hot water costs"**. Repairs, replacing motors and fans and renewing ducts or controls are **not** to be allocated through this general maintenance category.
### Specific categories take precedence
Do not use this general category where Immodio already offers a more suitable type of cost, for example for:
* "Heating and hot water (recoverable from tenant)",
* Maintenance of smoke alarms, no repair or purchase (recoverable from tenant),
* Caretaker, winter services, snow clearing (recoverable from tenant),
### Naming the operating costs in the rental agreement
For costs already expressly falling under Section 2 nos. 1 to 16 BetrKV, an effective agreement on the allocation of operating costs in accordance with the Operating Costs Ordinance is generally sufficient in a residential rental agreement.
The position is different with particular maintenance and inspection costs that only fall under **"other operating costs" under Section 2 no. 17 BetrKV**. These have to be **named specifically** in the rental agreement. A blanket reference to "other operating costs", "general maintenance costs" or "maintenance of the rental property" is generally not sufficient.
#### Newly arising maintenance costs
Where a new technical facility is installed during an ongoing tenancy, its later maintenance costs cannot be recovered from the tenant simply because they will arise regularly in future.
It has to be checked whether:
* the costs are operating costs by their nature at all,
* they are covered by a type of operating cost already agreed,
* there is an effective provision on operating costs newly arising in future,
* and whether a prior declaration to the tenant is necessary.
### What does "running" mean?
Maintenance does **not** have to take place every year. It is sufficient that it recurs according to plan and at comprehensible intervals.
The Federal Court of Justice regarded a four-year cycle for the inspection of an electrical system as sufficient.
Document therefore:
* the maintenance cycle provided for,
* the maintenance dates so far,
* the basis of the inspection,
* the building or system concerned.
### Distinguishing maintenance, inspection and repair
**Recoverable maintenance components might be, in certain circumstances**
* checking functionality,
* checking operational safety,
* visual checks,
* measurements,
* cleaning,
* lubrication,
* adjustment and calibration,
* documenting the inspection,
* the labour and travel costs directly necessary.
**Non-recoverable repair components are in particular**
* fault finding because of a specific malfunction,
* remedying a defect,
* replacing damaged or worn components,
* restoring a function that has failed,
* remedying damage caused by age or the weather,
* replacing a system that is technically worn out.
Maintenance and repair costs serve to remedy defects caused by wear, ageing or the weather. Under Section 1 (2) BetrKV they are expressly not operating costs.
#### Regularly replacing small parts
With prescribed regular replacement work, the distinction can be more difficult. The Federal Court of Justice left open whether the regular replacement of small electronic components of an existing system prescribed by a technical standard can exceptionally be treated as running maintenance expenditure.
Such material costs should therefore not be allocated automatically. Check in particular:
* whether the replacement is prescribed on a regular cycle independently of a defect,
* whether it really is only a low-value consumable or maintenance part,
* whether the costs are covered by the rental agreement,
* whether the invoice shows maintenance and spare parts separately.
With larger components or a replacement because of wear, non-recoverable refurbishment is regularly to be assumed.
### General emergency service flat rates
General standby availability for reports of burst water pipes, power failures, heating failures or other building faults is **not** recoverable maintenance. The Federal Court of Justice classifies receiving such fault reports and organising subsequent repairs as administrative costs.
This has to be distinguished from emergency call services necessary by law or technically for a particular installation, for example the lift emergency call standby. That is to be recorded in the specific category for the installation concerned.
### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
### Special features with commercial tenancies
With commercial premises the parties can agree a more extensive assumption of costs than with residential space. The agreement must, however, be specific or at least ascertainable.
Very broadly worded standard form clauses are problematic in commercial tenancy law too. The Federal Court of Justice objected to a clause imposing on a commercial tenant, without an appropriate limit, the maintenance and upkeep of all technical facilities and communal installations. Such a provision can burden the tenant with incalculable maintenance costs.
With commercial premises it therefore also has to be checked:
* which systems are specifically covered,
* whether only maintenance or also repair was transferred,
* whether communal installations are affected,
* whether a limit on the amount is necessary,
* whether it is an individually negotiated agreement or a standard form clause.
### The landlord's own work
Where the landlord carries out a recoverable maintenance or inspection service themselves, in principle the amount a suitable third party would charge for an equivalent service may be applied. Merely notional VAT may **not** be charged.
The following should be documented:
* the date and duration of the service,
* the specific system inspected or maintained,
* the scope of the work,
* the qualification or professional suitability,
* the comparison price used,
* the source of the comparison price,
* material costs, where applicable.
{% hint style="warning" %}
Inspections prescribed by law that are reserved to an approved or specially qualified specialist body generally **cannot** be replaced by own work.
{% endhint %}
### Economic efficiency and documents
Advance payments of operating costs have to be billed annually. The landlord has to observe the requirement of economic efficiency and, on request, allow the tenant to inspect the underlying receipts.
Keep in particular:
* the maintenance or inspection contract,
* a precise description of the service,
* the invoice and proof of payment,
* the maintenance and inspection record,
* the designation of the system concerned,
* evidence of the maintenance cycle,
* the split between maintenance and repair,
* the allocation where there are several buildings,
* the rental agreement with the type of cost agreed.
Maintenance of smoke alarms, no repair or purchase (recoverable from tenant)
Use this category exclusively for the **regularly arising costs of function testing and maintaining smoke alarms already installed**. These include services that check and ensure that the devices are properly fitted, undamaged and operational.
The Federal Court of Justice classifies the regular testing and ensuring of the operational readiness of smoke alarms as **other operating costs under Section 2 no. 17 BetrKV**. Such maintenance costs can therefore in principle be recovered from residential tenants, unlike the costs of buying, renting or replacing the devices.
{% hint style="warning" %}
The Federal Court of Justice has expressly held that the **rental costs of smoke alarms are not recoverable operating costs**. Economically, renting the devices takes the place of the purchase, which is likewise not recoverable, and may **not** become an operating cost simply because the landlord rents the devices instead of buying them. For renting or buying smoke alarms you can use the category **"Rental for smoke alarms"** for your own bookkeeping.
{% endhint %}
#### What can be entered here?
The costs of the following in particular can be entered:
* the regular visual and function testing of the smoke alarms,
* checking operational readiness and the alarm function,
* checking the intended mounting position,
* checking that the smoke inlet openings are clear and not painted over or covered,
* checking for identifiable damage or soiling,
* cleaning the alarm, as far as it is part of the regular maintenance,
* documenting the inspection carried out,
* the maintenance company's travel and labour costs,
* the costs of a permissible technical or radio-based inspection, as far as it actually checks operational readiness,
* running service costs, as far as they are clearly attributable to the maintenance and not to providing or renting the devices.
{% hint style="info" %}
The currently published **DIN 14676-1:2025-05** contains minimum requirements for the planning, installation, operation and upkeep of smoke alarms. The manufacturer's specifications and the applicable state law requirements should also be taken into account for the maintenance.
{% endhint %}
### The condition for recovering the costs from tenants
As maintaining smoke alarms is not expressly listed in numbers 1 to 16 of the Operating Costs Ordinance, these are **other operating costs**. The type of cost should therefore be agreed with sufficient specificity in the rental agreement, which is the case in the Immodio rental agreement.
### Who is responsible for the maintenance?
Responsibility under public law for ensuring operational readiness is governed differently in the building regulations of the federal states. Depending on the state, it can be assigned to the owner or the direct possessor (generally the tenant).
A state law provision under which the tenant is responsible for operational readiness does not, however, automatically prevent the landlord from organising uniform maintenance. This is often sensible for landlords, because it lets inspection intervals, the stock of devices and defects found be documented centrally. The specific responsibility should nevertheless be checked against the building regulations of the state concerned.
### Assignment
* Where there was **no change of tenant during the billing year**, assign the entry to the unit or the tenancy concerned.
* Where there was a **change of tenant during the year** and the **costs concern only one particular tenancy**, enter them against that tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **already allocated to the individual tenancies in the WEG statement**, enter them against the respective tenancy.
* Where there was a **change of tenant during the year**, the **costs concern several tenancies pro rata** and the costs are **not** already allocated to the individual tenancies in the WEG statement, enter them against the unit concerned.
### Purchase and device rental are not recoverable
The following do not belong in this category:
* the initial purchase of the smoke alarms,
* the costs of the initial equipment,
* renting or leasing the smoke alarms,
* provision charges for the devices,
* the complete replacement of old or defective smoke alarms,
* buying additional devices,
* the installation costs of the initial fitting.
{% hint style="warning" %}
The Federal Court of Justice has expressly held that the **rental costs of smoke alarms are not recoverable operating costs**. Economically, renting the devices takes the place of the purchase, which is likewise not recoverable, and may **not** become an operating cost simply because the landlord rents the devices instead of buying them. For renting or buying smoke alarms you can use the category **"Rental for smoke alarms"** for your own bookkeeping.
{% endhint %}
### Distinguishing repairs and spare parts
The following in particular likewise do not belong in this category:
* repairs to damaged smoke alarms,
* remedying technical defects,
* replacing defective devices,
* replacement because the service life has expired,
* replacing or newly installing mounting plates,
* costs resulting from damage or loss,
* work on a central fire alarm system, unless these are ordinary smoke alarms for apartments.
By law, maintenance and repair costs to remedy defects are **not** operating costs.
{% hint style="info" %}
A regular battery change can be part of a maintenance service, depending on the type of device, the contractual arrangement and the breakdown of the invoice. Where the complete device is replaced in the case of a smoke alarm with a permanently installed long-life battery, however, this is generally no longer mere maintenance.
{% endhint %}
### Mixed maintenance and rental contracts
Many service providers bill smoke alarms in an overall package, for example as:
* "rental and maintenance",
* "device service",
* "full-service flat rate",
* "provision, remote inspection and replacement".
Such overall invoices may not be entered in this category in full without being checked. Have the following shown separately if possible:
1. pure maintenance and inspection costs,
2. device rental or leasing,
3. new purchases and device replacement,
4. repairs,
5. additional administrative or portal fees.
Only the share comprehensibly attributable to the regular testing and ensuring of operational readiness should be recorded as recoverable maintenance. The separation is particularly important because maintenance costs can in principle be recoverable, whereas device rental costs are not under the case law of the Federal Court of Justice.
### Freehold apartments that are let
With a freehold apartment that is let, the owners' association can resolve on uniform installation, checking and maintenance by a specialist company. Under the case law of the Federal Court of Justice, such a resolution can also include apartments in which smoke alarms of their own are already present.
For the operating cost statement to the tenant it nevertheless has to be checked:
* which amount is attributable to the unit according to the WEG statement,
* whether maintenance and purchase were shown separately,
* whether device rental is included,
* whether the maintenance costs are agreed in the rental agreement,
* which allocation key is to be applied in the tenancy.
Allocation within the WEG does not automatically mean that every component charged there may also be recovered from the apartment's tenant.
### Documentation and receipts
Keep in particular the following documents:
* the maintenance contract,
* the invoice with the services shown separately,
* a list of the devices and apartments inspected,
* the date and result of each inspection,
* notes on defects found,
* evidence of the maintenance cycle,
* the allocation where there are several buildings,
* the calculation of the individual tenants' shares,
* the rental agreement with the type of operating cost agreed.
Advance payments of operating costs have to be billed annually. The tenant can also ask to inspect the underlying receipts.
{% endstep %}
{% step %}
### Entering the maintenance reserve
In the next step you record your WEG's **maintenance reserve**. In older statements it is often still called the **repair reserve**.
Two different processes have to be entered separately here: the **contribution to the maintenance reserve** and the **WEG's actual use of the maintenance reserve**.
The distinction is important in particular for freehold apartments that are let. For tax purposes a contribution to the maintenance reserve is not yet deductible income-related expenditure. Only when the WEG actually uses the accumulated reserves for a measure can the amount attributable to your unit become relevant for tax. As the contribution and the later use of the reserve frequently take place in different years, they are treated differently for tax purposes in Immodio's [**DATEV export**](/en/anleitung/einnahmen-und-ausgaben/datev-export.md).
{% hint style="warning" %}
The maintenance reserve and maintenance or refurbishment measures financed from it are **not recovered from the tenant**.
{% endhint %}
Enter both processes separately, therefore, in accordance with your WEG statement:
Contribution to the maintenance reserve according to the WEG statement
Use this category for the amount you as an apartment owner **paid into your WEG's maintenance reserve** in the billing year.
The reserve is accumulated by the owners' association so that future maintenance and refurbishment measures on the communal property can be financed.
In older WEG statements the maintenance reserve is often still called the **repair reserve**.
{% hint style="warning" %}
Contributions to the maintenance reserve are not recoverable operating costs. They may therefore **not be recovered from the tenant through the operating cost statement**.
{% endhint %}
#### What can be entered here?
Enter here the **amount attributable to your freehold apartment** that was paid into the maintenance reserve in the billing year.
This can include, for example:
* regular contributions to the maintenance reserve as part of the service charge,
* a contribution to the maintenance reserve resolved on annually,
* additional contributions to the reserve,
* a special payment or special levy where it was expressly paid into the maintenance reserve.
#### Where do I find the amount?
Depending on the WEG management, the amount can be described differently.
Look in particular for details such as:
* contribution to the maintenance reserve,
* contribution to the repair reserve,
* payment towards the maintenance reserve,
* reserve contribution,
* repair reserve,
* development of the maintenance reserve.
The details can be in your individual statement, in a separate statement of the reserve's development or in other annexes to the WEG statement.
{% hint style="info" %}
Take only the **contribution amount attributable to your freehold apartment**.
{% endhint %}
#### Do not enter the balance of the reserve
The **balance of the maintenance reserve at the end of the year** is not the same as your contribution in the billing year.
Do not enter, therefore:
* the WEG's entire reserve balance,
* your notional share of the existing reserve balance,
* the opening or closing balance of the maintenance reserve.
Only the **contribution for the respective billing year** is relevant for this entry.
#### Why does the contribution have to be entered separately?
The contribution to the maintenance reserve has to be separated from the other costs in your WEG statement.
With a freehold apartment that is let, the contribution to the maintenance reserve is **not yet an immediately deductible item of income-related expenditure**.
It is generally only taken into account for tax when the WEG actually uses the accumulated funds for corresponding measures.
#### The contribution and the use can fall in different years
The contribution to the reserve and its later use are two separate processes.
Example:
* In 2026 you pay a share of **€900** into the maintenance reserve. The WEG does not use these funds at first.
* The **€900 is recorded as a contribution to the maintenance reserve for 2026**, but at that point it is not yet corresponding maintenance expenditure for tax purposes.
Where the WEG uses funds from the reserve for a roof repair in a later year, your share attributable to that measure is recorded separately in the year of the actual use through **"Use of the maintenance reserve by the WEG"**.
{% hint style="info" %}
The amount of the later use of the reserve does **not** have to match the amount of your contribution in the same year.
{% endhint %}
#### Distinguishing special levies correctly
With a special levy too, what matters is **what the WEG uses the payment for**.
Where a special levy is first paid into the maintenance reserve, the corresponding payment can be recorded here.
Where a special levy is instead used directly to finance a specific repair or other measure and is not paid into the maintenance reserve at all, it is **not** a contribution to the maintenance reserve. In that case use the entry category appropriate to the specific expense.
#### Assignment
This entry concerns the amount attributable to your freehold apartment that was paid into the maintenance reserve in the billing year. For the assignment, therefore, select the **unit** to which the WEG statement relates.
#### When this category should not be used
Do not enter here:
* the entire balance of the maintenance reserve,
* your notional share of the reserve balance,
* a use of or withdrawal from the maintenance reserve,
* repair or maintenance measures financed from the reserve,
* other non-recoverable costs from the WEG statement,
* the WEG's administrative costs,
* the WEG's recoverable operating costs,
* special levies used directly for a specific measure and not paid into the reserve,
* repairs or maintenance to your separate property that you paid for directly yourself.
Where the WEG already used funds from the reserve for a specific measure in the billing year, also record your corresponding share through the category **"Use of the maintenance reserve by the WEG"**.
#### Documents for the bookkeeping and the tax return
Keep in particular:
* the WEG annual statement,
* the individual statement for your freehold apartment,
* the development of the reserve,
* the asset report,
* the business plan,
* resolutions on additional contributions to the reserve or special levies, where applicable.
This makes it possible to see later **which amounts were merely paid into the reserve and which amounts were actually used by the WEG**.
Use of the maintenance reserve by the WEG
Use this category where your WEG **actually used funds from the maintenance reserve for a maintenance or refurbishment measure** in the billing year.
Unlike the contribution to the maintenance reserve, the actual use of the accumulated funds can be relevant for tax with a freehold apartment that is let.
It does not matter that you did not pay the amount again from your own bank account in the year of use. What is decisive is that the WEG used reserves accumulated earlier for a specific measure on the communal property.
#### What can be entered here?
Enter here the **share attributable to your unit of the maintenance reserve actually used**, as far as the reserve was used for measures to be treated as maintenance expenditure for tax purposes.
Typical examples can be:
* repairs to the roof,
* refurbishment of the facade,
* repairs to communal pipes and cables,
* repairs to the central heating system,
* refurbishment of the stairwell,
* repairs to the lift,
* refurbishment of balconies or other parts of the communal property,
* repairs to the underground car park, cellar or communal outdoor facilities,
* other maintenance and refurbishment measures on the communal property.
What matters is not the amount of your earlier contributions to the reserve but the **share attributable to your freehold apartment of the reserve actually used in the respective year**.
#### Where do I find the amount?
The use of the reserve can be described and presented differently depending on the WEG management.
Look in particular for descriptions such as:
* use of the maintenance reserve,
* withdrawal from the maintenance reserve,
* reserve withdrawal,
* use of the repair reserve,
* measures financed from the reserve,
* development of the maintenance reserve.
The corresponding details can be in the WEG statement, the individual statement, a statement of the reserve's development or in additional annexes from the property management.
{% hint style="info" %}
Do **not** take the entire amount used by the WEG, but only the share attributable to your freehold apartment.
{% endhint %}
#### Note the difference between use and withdrawal
What is decisive is the **actual use of the reserve for a specific measure**. A mere transfer of money between different accounts of the WEG is not yet a maintenance measure relevant for tax.
Check in particular, therefore, whether the reserve withdrawal shown was actually used or merely transferred to another account of the WEG.
#### The tax treatment
With a freehold apartment that is let, contributions to the maintenance reserve cannot yet be taken into account as income-related expenditure.
Only when the WEG actually uses the accumulated funds can the corresponding share be taken into account for tax.
**Not every use of the reserve is automatically immediately deductible as income-related expenditure**, however.
Ordinary repair and maintenance measures are generally maintenance expenditure. Extensive building work can, however, be classified for tax as acquisition or production costs or as production costs close to acquisition, for example, and may then not simply be applied in full as running maintenance expenditure.
That can be relevant in particular with larger extensions, fundamental redesigns or extensive modernisation measures.
{% hint style="info" %}
Where the tax classification of a larger measure is unclear, you should check it before making the entry or discuss it with your tax adviser.
{% endhint %}
#### Assignment
For the assignment select the **property** to which the freehold apartment belongs. Enter only the share of the use of the reserve actually assigned to your freehold apartment or your co-ownership share.
#### Do not recover from the tenant
The use of the maintenance reserve typically serves to finance maintenance and refurbishment measures. The entry serves in particular to present the landlord's expenditure correctly and to assign it for tax in the [**DATEV export**](/en/anleitung/einnahmen-und-ausgaben/datev-export.md) to your tax adviser.
{% hint style="warning" %}
These costs are not recoverable operating costs and are therefore **not recovered from the tenant**.
{% endhint %}
#### When this category should not be used
Do not enter here:
* your contribution to the maintenance reserve,
* the entire balance of the maintenance reserve,
* your notional share of the existing reserve balance,
* mere transfers within the WEG without a specific maintenance measure,
* the WEG's recoverable operating costs,
* the WEG's administrative costs,
* repairs to your separate property that you commissioned and paid for directly yourself,
* measures to be treated for tax as acquisition or production costs,
* maintenance measures already recorded elsewhere in Immodio.
For your contribution to the reserve use the category **"Contribution to the maintenance reserve according to the WEG statement"** instead.
#### Documents for the bookkeeping and the tax return
Keep in particular:
* the WEG annual statement,
* the individual statement for your freehold apartment,
* the development of the reserve,
* the asset report,
* resolutions of the owners' meeting on carrying out and financing the measure,
* a list of the measures financed from the reserve,
* evidence of the share attributable to your unit,
* invoices or cost lists for the underlying measure, where applicable.
These documents help in particular to show **when, in what amount and for what the maintenance reserve was actually used**.
{% hint style="info" %}
Entries you create in this category are not shown in the operating cost statement, because they are not relevant to operating costs. You will find these entries under "[**Income and expenditure**](/en/anleitung/einnahmen-und-ausgaben.md)" accordingly.
{% endhint %}
{% endstep %}
{% step %}
### Water consumption
In the next step you now enter the water consumption for the individual tenancies and any vacancies.
Where there was a change of tenant during the settlement period and a vacancy arose in connection with it, it is necessary to take an interim reading and to record the corresponding meter readings for the vacancies. Where there was neither a change of tenant nor a vacancy during the settlement period, this step can be skipped.
{% hint style="info" %}
You can find a guide on how to record the individual water consumption figures in Immodio [**here**](/en/anleitung/betriebskostenabrechnungen/wasserverbrauch.md).
{% endhint %}
{% endstep %}
{% step %}
### Heating and hot water consumption
With a WEG you generally do not have to prepare a heating cost statement, because it is normally already prepared by the WEG management or by a metering service provider responsible for it.
You can therefore skip the step for heating and hot water consumption by clicking **"Continue"**.
{% hint style="info" %}
Where, exceptionally, a change of tenant that took place was not taken into account in the WEG statement and you therefore want to prepare the heating cost statement yourself, you can find a detailed step-by-step guide [**here**](/en/anleitung/betriebskostenabrechnungen/heiz-und-warmwasserverbrauch.md).
{% endhint %}
{% endstep %}
{% step %}
### Checking the statement
This page is the last check before the operating cost statement is sent.
In the preview, check that all WEG items were entered against the right tenancy, that the advance payments were assigned correctly and that the amounts match the individual WEG statement.
{% hint style="info" %}
You can find further information on this page [**here**](/en/anleitung/betriebskostenabrechnungen/betriebskostenabrechnung.md).
{% endhint %}
{% endstep %}
{% step %}
### Attaching the WEG statement
At the end of every operating cost statement you can now attach a copy of the WEG statement and other documents specifically relevant to the selected tenancy. These files are automatically sent to the tenants of that tenancy together with the operating cost statement.
You can upload files by **drag and drop** or add them using the **camera**, the **gallery** or the file picker. The documents uploaded should only contain information intended for this tenancy.
#### Typical examples of attachments
Suitable attachments can be, for example:
* the finished **heating and hot water statement** from a metering service provider,
* the finished **service charge statement** or an extract from it,
* a list of the **recoverable share** from the service charge statement,
* receipts or explanations of individual cost items,
* evidence of **labour costs under Section 35a of the German Income Tax Act (EStG)**,
* supplementary calculations where there was a change of tenant or a vacancy,
* individual letters or explanations of the statement.
{% hint style="warning" %}
Before uploading, check that the document really belongs to the selected tenancy and does not contain confidential data of other tenants or owners. With service charge statements or service provider statements in particular, personal information that is not relevant should be redacted or removed before it is passed on.
{% endhint %}
{% endstep %}
{% step %}
### Providing the operating cost statement
In the last step you can complete the statement for the selected tenancies and hand it over to the tenants digitally by clicking "**Provide**". It can no longer be edited afterwards.
{% hint style="info" %}
You can find further information on providing the operating cost statement [**here**](/en/anleitung/betriebskostenabrechnungen/betriebskostenabrechnung/betriebskostenabrechnung-bereitstellen.md).
{% endhint %}
#### ***The operating cost statement for a unit in a WEG is thereby successfully completed.***
{% endstep %}
{% endstepper %}
***
## What applies with two or more units in the same WEG property
Where you manage two units in the same WEG property in Immodio, record the entries from the respective WEG statement for each unit one after the other in one operating cost statement. Each unit has its own individual WEG statement and is therefore considered separately.
Proceed as follows:
1. Record the WEG items for **unit 1** as separate entries and assign these entries to **unit 1** or to the appropriate **tenancy** of unit 1.
2. Then record the WEG items for **unit 2** as separate entries and assign these entries to **unit 2** or to the appropriate **tenancy** of unit 2.
{% hint style="warning" %}
In the step "[**Attaching the WEG statement**](#attaching-the-weg-statement)", make absolutely sure that you attach the correct WEG statement to each individual tenancy.
{% endhint %}