> For the complete documentation index, see [llms.txt](https://help.immodio.app/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://help.immodio.app/en/anleitung/betriebskostenabrechnungen/co-steuer-aufteilen.md).
# Splitting the CO₂ tax
This page explains which details are relevant in connection with allocating the CO₂ tax.
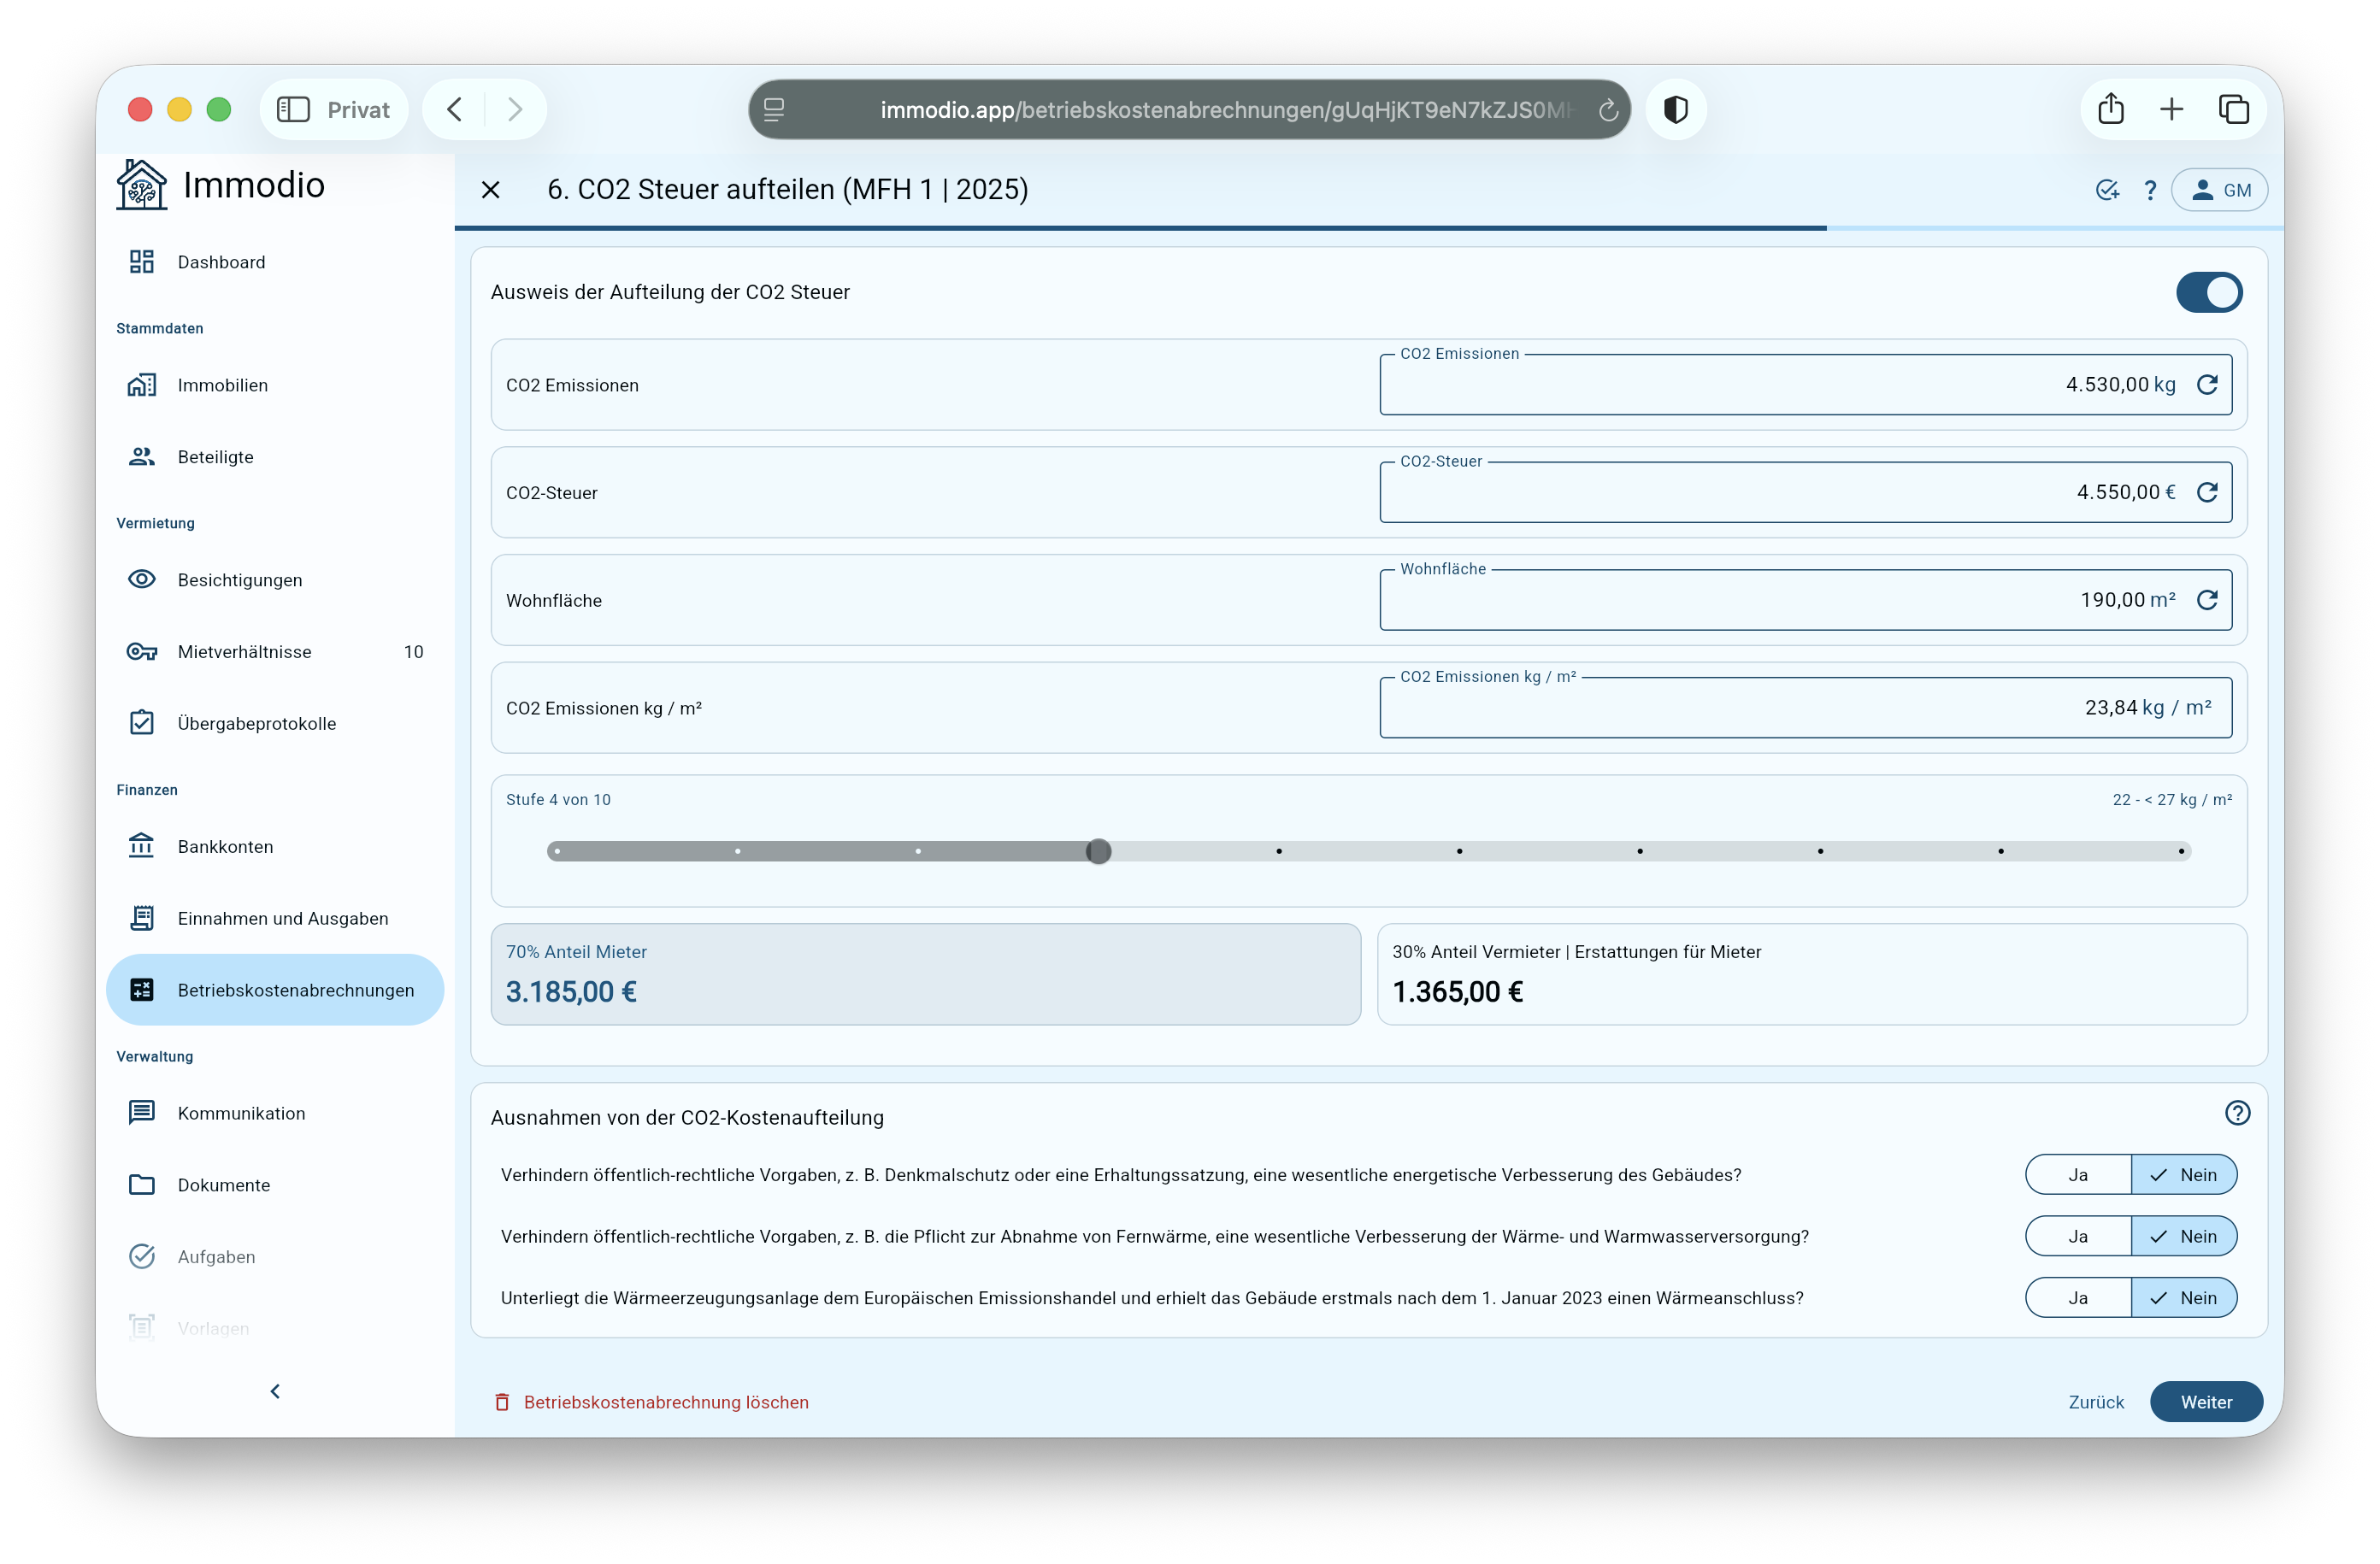
In this step Immodio calculates the allocation of the CO₂ costs for the operating cost statement.
The basis is the CO₂ quantity and the CO₂ costs of the consumption and cost data stored under "[Income and expenditure](/en/anleitung/einnahmen-und-ausgaben.md)" together with the [area data stored in the unit](/en/anleitung/immobilien/einheit/grunddaten-einheit.md#floor-area). From this Immodio automatically determines the CO₂ emissions per m², assigns the property to the statutory band and calculates the share for tenant and landlord.
### **Showing or deactivating the CO₂ tax**
The "**Show the allocation of the CO₂ tax**" switch is enabled by default. Leave it enabled if CO₂ costs are to be shown for your statement and allocated between tenant and landlord.
If an allocation of CO₂ costs is not required for your operating cost statement, you can deactivate the CO₂ cost allocation. Please observe the [statutory provisions](#verlinkung-der-rechtsgrundlage-und-relevanter-gesetzesvorgaben) here. Immodio takes the three statutory "[exceptions to the CO₂ cost allocation](#exceptions-to-the-co-cost-allocation)" listed in this step into account automatically, so you do **not** have to deactivate the CO₂ cost allocation for them.
### **Exceptions to the CO₂ cost allocation**
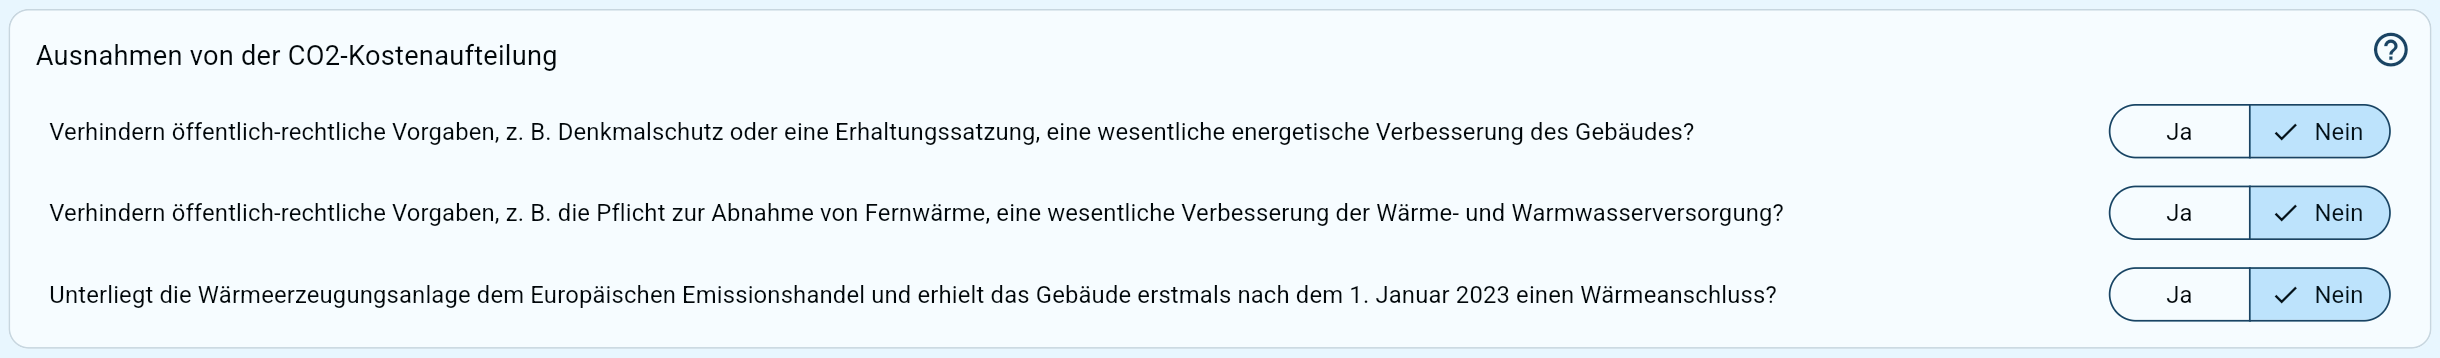
The German Carbon Dioxide Cost Allocation Act (CO₂KostAufG) provides for three **statutory** **exceptions** that can affect the allocation of the CO₂ costs.
Immodio takes these exceptions into account **automatically** in the calculation as soon as you store the corresponding details. To this end Immodio asks about the possible statutory exceptions. "**No**" is selected by default in each case.
Choose "**Yes**" where the respective condition applies to your property. In that case Immodio automatically adjusts the CO₂ cost allocation in the background.
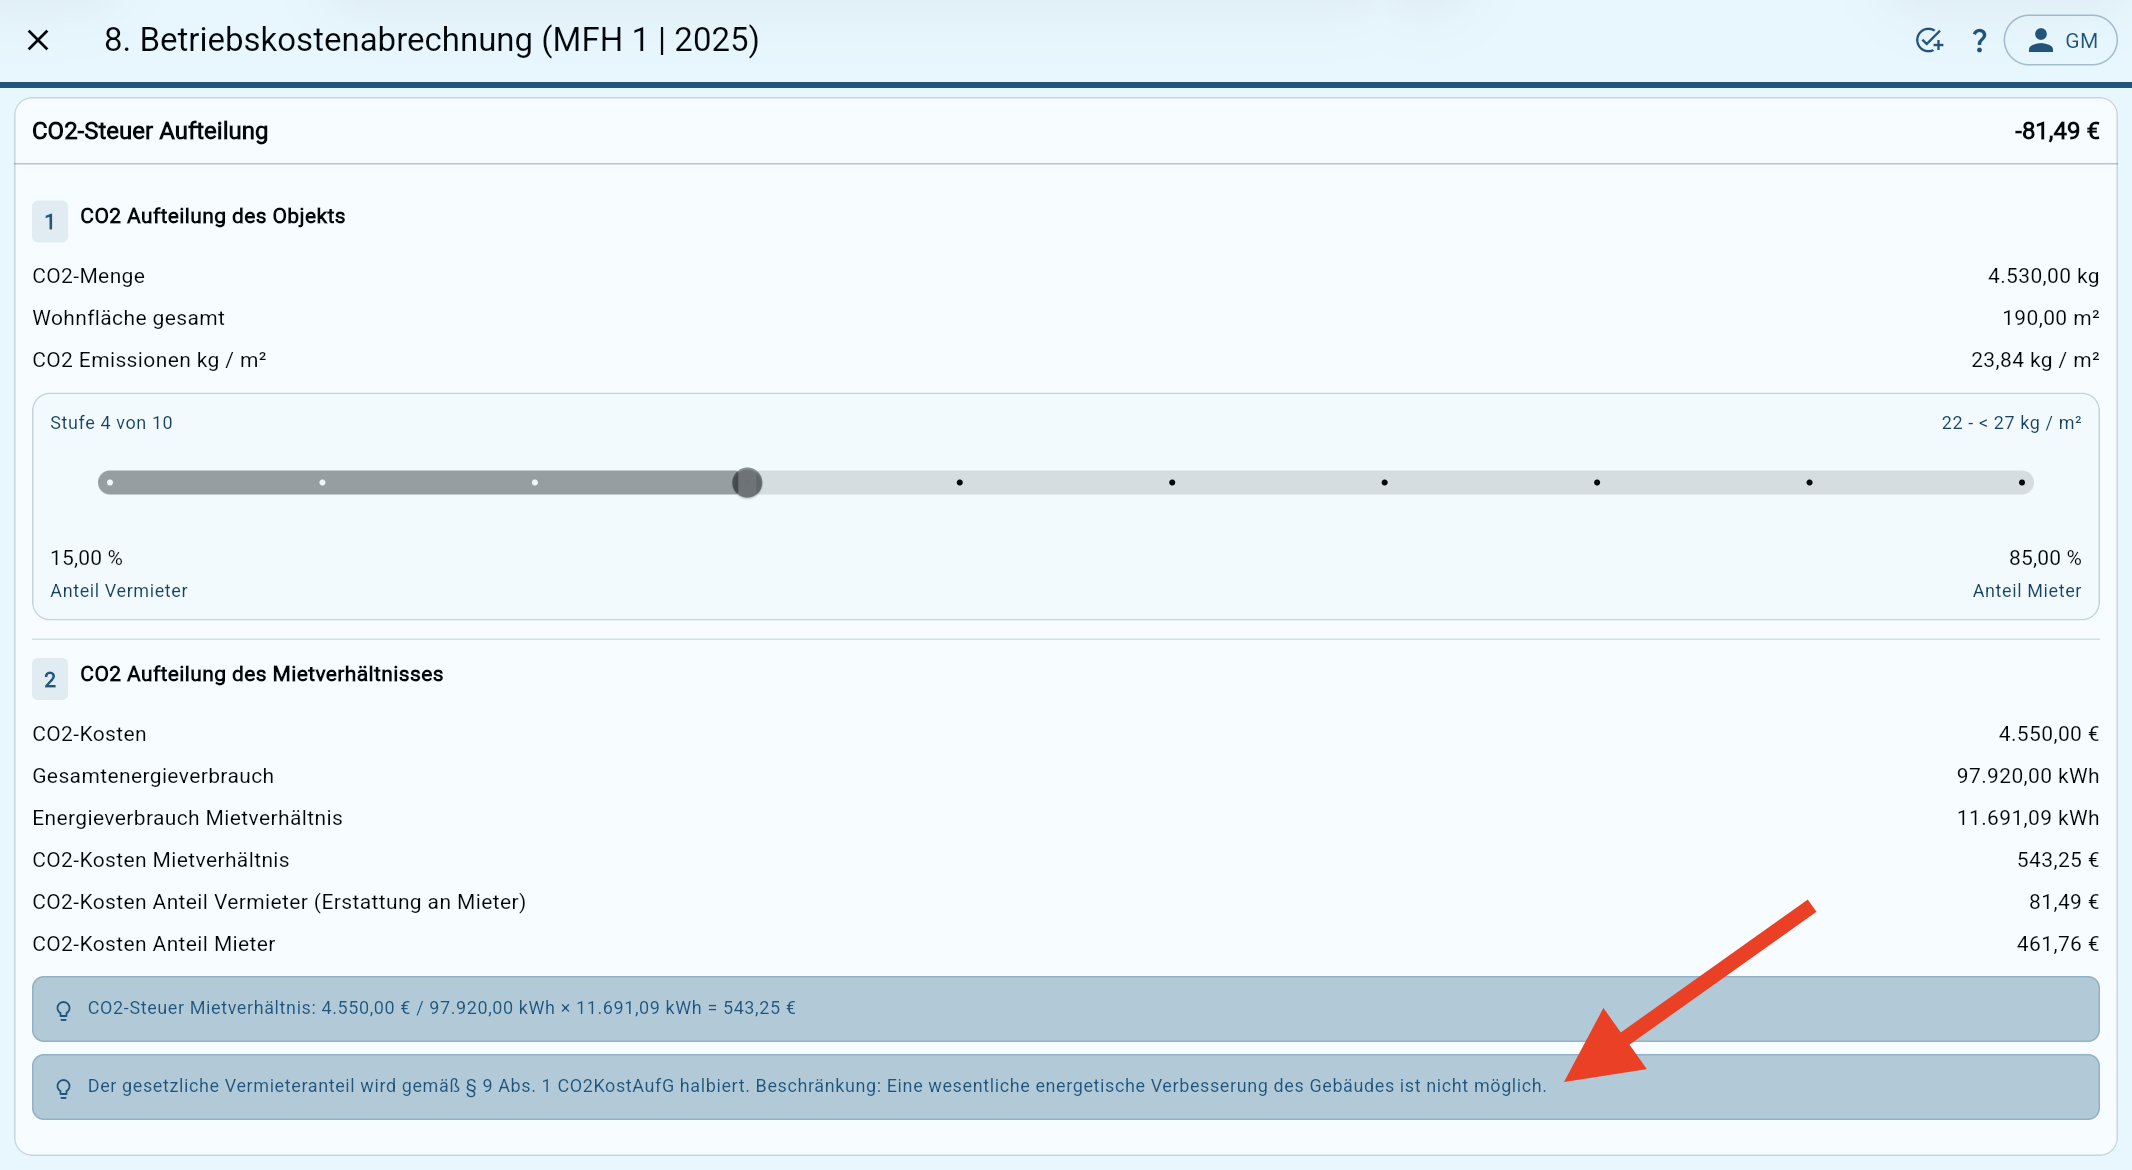
In addition, your tenant is shown in step 8 of the operating cost statement which share of the CO₂ costs is attributable to the individual tenancies. Where an exception was selected, a corresponding note appears there explaining why the landlord's share was reduced or why no CO₂ cost allocation is made *(see the image "Reasons for the CO₂ cost allocation in the operating cost statement" below)*.
Do public law requirements, for example listed building protection or a conservation statute, prevent a substantial improvement in the building's energy performance?
Answer this question with **"Yes"** where public law requirements mean that a substantial improvement in the building's energy performance is impossible or possible only to a very limited extent.
What is meant are restrictions on the **building envelope** in particular, for example on the facade, the roof or the windows. Typical cases are:
* facade insulation is not permitted for reasons of listed building protection,
* historic windows may not be replaced with windows offering better energy performance,
* requirements protecting a listed building or an ensemble prevent substantial changes to the building envelope,
* a conservation statute or its specific requirements prevent a substantial energy refurbishment measure.
The mere fact that a building **is listed or lies in a conservation area does not automatically mean that "Yes" is to be selected**. What matters is whether the public law requirement **actually prevents a substantial improvement in energy performance**. According to the explanatory memorandum to the act, minor restrictions are not sufficient. The legislator expressly names a ban on energy-related facade insulation as an example of a substantial restriction.
The landlord has to **be able to prove** the conditions to the tenant. Possible evidence includes, for example, information from the listed buildings authority, the relevant statute or a decision refusing permission. Section 9 (3) CO₂KostAufG expressly prescribes this duty of proof.
**Where can I check this?**\
Check the list of protected buildings or contact the competent listed buildings authority of your city or district. You can find out from the respective city or municipality whether a conservation statute applies to the property. Conservation statutes are governed by Section 172 of the German Building Code (BauGB).
**Effects in Immodio**
Where "Yes" was selected, Immodio halves the statutory landlord's share. The remaining share is assigned to the tenant.
**Further information:**
* [Section 9 CO₂KostAufG – restrictions on energy-related improvements](https://www.gesetze-im-internet.de/co2kostaufg/__9.html?utm_source=chatgpt.com)
* [Section 172 BauGB – conservation statute](https://www.gesetze-im-internet.de/bbaug/__172.html?utm_source=chatgpt.com)
Do public law requirements, for example an obligation to take district heating, prevent a substantial improvement in the heat and hot water supply?
Answer this question with **"Yes"** where a public law obligation prevents you from substantially changing the heating technology or the type of heat supply.
A typical case is a **municipal obligation to connect to and use local or district heating**. Where such an obligation exists and you therefore may not switch from district heating to a heat pump or another heating system, for example, there is in principle a relevant restriction within the meaning of Section 9 CO₂KostAufG.
Typical cases are:
* a municipal district heating statute obliges the building to use the heating network,
* another public law provision prohibits switching to an alternative heating technology,
* an exemption from the obligation to connect or use is impossible or was refused.
Answer the question with **"No"**, on the other hand, where despite an existing district heating connection you are legally free to decide to switch to another heating technology.
Important: the mere fact that the municipality **has designated the area as a heating network area in its municipal heat planning does not yet create an obligation to connect**. According to information from the federal government, an obligation to connect and use can only arise on the basis of a corresponding municipal provision, in particular a district heating statute.
Nor is a purely private law contract with a heat supplier automatically equivalent to a **public law requirement** within the meaning of Section 9 CO₂KostAufG. What matters is whether a statutory, official or municipal provision actually restricts your freedom of choice.
**Where can I check this?**\
Check the statutes of your city or municipality or ask there whether an obligation to connect and use applies to the property. On the basis of state law, municipalities can provide for such an obligation for public district heating or district cooling networks.
**Effects in Immodio**
Where "Yes" was selected, Immodio halves the statutory landlord's share. The remaining share is assigned to the tenant.
**Further information:**
* [Section 9 CO₂KostAufG – restrictions on energy-related improvements](https://www.gesetze-im-internet.de/co2kostaufg/__9.html?utm_source=chatgpt.com)
* [Section 109 of the German Buildings Energy Act – obligation to connect and use](https://www.gesetze-im-internet.de/geg/__109.html?utm_source=chatgpt.com)\
[The federal government's FAQ on municipal heat planning and the obligation to connect](https://www.energiewechsel.de/KAENEF/Redaktion/DE/FAQ/Waermeplanung/faq-waermeplanung-wpg.html?utm_source=chatgpt.com)
Is the heat generation plant subject to European emissions trading and did the building first receive a heat connection after 1 January 2023?
This question is only to be answered with **"Yes"** where **both** conditions are met at the same time:
1. The heat supplied to the building comes from a heat generation plant that is subject to the **European Emissions Trading System (EU ETS)**, **and**
2. the building **first received a heat connection after 1 January 2023**.
For such new connections Section 2 (4) CO₂KostAufG provides a special exception: the extension of the CO₂KostAufG to heat supplied from EU ETS plants does not apply to these buildings.
**Example:**\
A building was previously supplied by its own gas heating and was connected to a district heating network for the first time after 1 January 2023. Where that heating network is fed by a heat generation plant subject to the EU ETS, the question is in principle to be answered with "Yes".
Where the building already had a corresponding heat connection **before or at the latest at the beginning of 2023**, this exception does **not** apply. Likewise, "No" is to be selected where the heat generation plant is not subject to the EU ETS.
**How can I check whether the heat generation plant is subject to the EU ETS?**
You can check publicly in the [European Commission's Union Registry](https://union-registry-data.ec.europa.eu/report/eu-registry-operator-accounts?utm_source=chatgpt.com) whether a specific heat generation plant takes part in European emissions trading (EU ETS 1). The register contains the stationary installations taking part in the EU ETS, including the installation name, operator, location, activity and permit data.
With a district heating network it is not always sufficient to search only for the name of the supplier. A heating network can be fed by **several different generation plants**. Some of these plants may be subject to the EU ETS and others not.
If you cannot clearly establish which plants feed your specific heating network, contact your **heat supplier.** Ask as specifically as possible:
> "Is the heating network supplying the property at \[address] fed, in whole or in part, by heat generation plants that are subject to European emissions trading (EU ETS 1) under the German Greenhouse Gas Emissions Trading Act? If so, which heat generation plants are these?"
**Effects in Immodio**
Where "Yes" was selected, Immodio assigns the CO₂ costs entirely to the tenant. **No** landlord's share is calculated.
**Further information:**
* [Section 2 CO₂KostAufG – scope and new EU ETS connections](https://www.gesetze-im-internet.de/co2kostaufg/__2.html?utm_source=chatgpt.com)
* [Section 3 CO₂KostAufG – details from the fuel and heat supplier](https://www.gesetze-im-internet.de/co2kostaufg/__3.html?utm_source=chatgpt.com)\
[The federal government's official guide to CO₂ cost allocation](https://www.bmwk.de/Redaktion/DE/Artikel/Energie/berechnung-aufteilung-kohlendioxidkosten.html?utm_source=chatgpt.com)
Reasons for the CO₂ cost allocation in the operating cost statement
#### Checking the statement of the CO₂ tax allocation manually in the overview
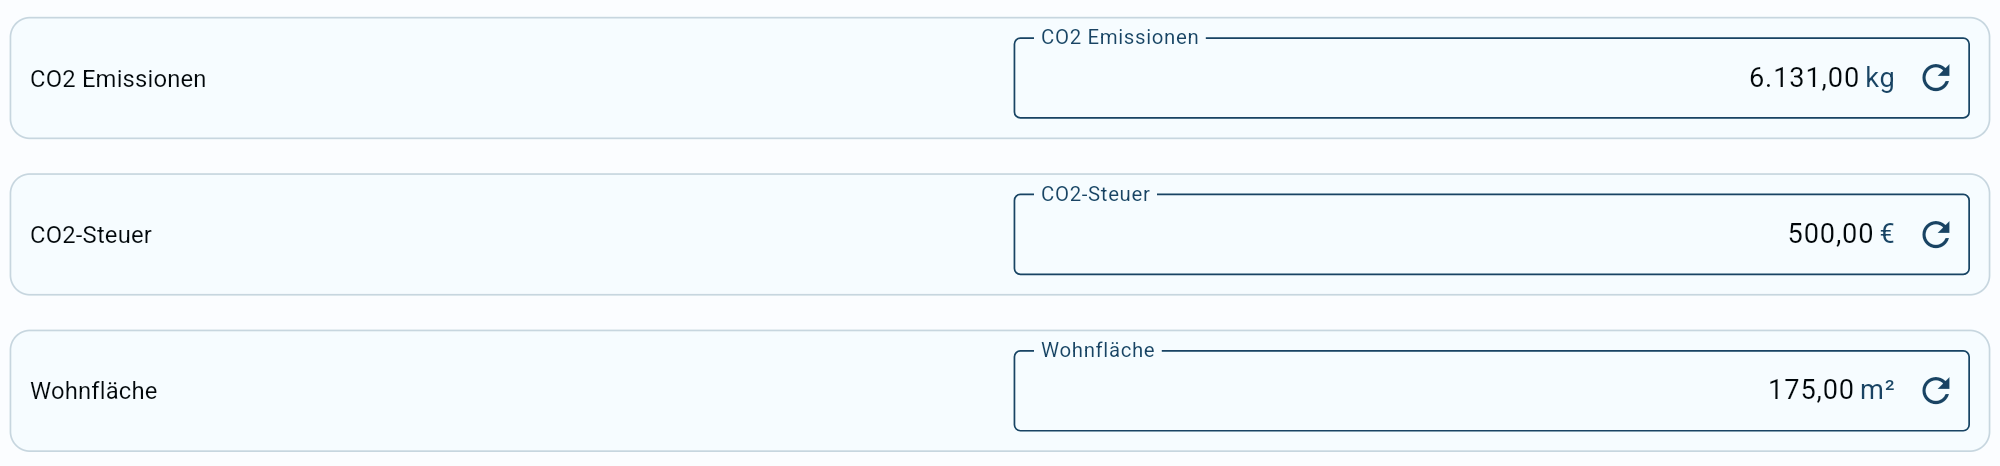
In the overview the CO₂ emissions in kg, the CO₂ tax and the living space used as a basis can be checked and adjusted manually.
This option serves to follow the calculation on the basis of the documents available and to compare different bases of calculation easily. It shows, for example, how lower CO₂ emissions would affect the classification and the allocation of the CO₂ costs.
{% hint style="warning" %}
For the actual operating cost statement the values have to match the details from the fuel or heat supplier's invoice and the property and area data stored. You can restore the values originally calculated by clicking the arrow icon.
{% endhint %}
**For a more detailed check and further research, you will find the most important legal bases for CO₂ cost allocation here:**
Links to the legal basis and relevant statutory requirements
The corresponding obligation to state the CO₂ costs follows from [Section 7 (3) CO₂KostAufG](https://www.gesetze-im-internet.de/co2kostaufg/__7.html).
**Relevant legal bases for more detailed research:**
* [CO₂KostAufG – the full text of the act](https://www.gesetze-im-internet.de/co2kostaufg/)
* [Section 2 CO₂KostAufG – scope](https://www.gesetze-im-internet.de/co2kostaufg/__2.html)
* [Section 3 CO₂KostAufG – details from the fuel or heat supplier](https://www.gesetze-im-internet.de/co2kostaufg/__3.html)
* [Section 5 CO₂KostAufG – allocation for residential buildings](https://www.gesetze-im-internet.de/co2kostaufg/__5.html)
* [Annex to the CO₂KostAufG – the band model for residential buildings](https://www.gesetze-im-internet.de/co2kostaufg/anlage.html)
* [Section 7 CO₂KostAufG – calculation, statement and right to a reduction](https://www.gesetze-im-internet.de/co2kostaufg/__7.html)
* [Section 8 CO₂KostAufG – rules for non-residential buildings](https://www.gesetze-im-internet.de/co2kostaufg/__8.html)
* [Section 9 CO₂KostAufG – restrictions due to public law requirements](https://www.gesetze-im-internet.de/co2kostaufg/__9.html)
* [Section 11 CO₂KostAufG – temporal scope](https://www.gesetze-im-internet.de/co2kostaufg/__11.html)
### **A special case: allocating the CO₂ costs where an existing heating cost statement does not take a change of tenant into account**
As a rule you can adopt the heating and hot water statement of a WEG manager or a metering service provider where the settlement period and any change of tenant have already been taken into account correctly there.
If, however, you have a finished heating cost statement that was prepared only for the unit or for the entire settlement period and does **not allocate a change of tenant during the year separately**, the allocation of the heating costs has to be reproduced manually in Immodio.
In this case also check whether the external heating cost statement already shows a landlord's share of the CO₂ costs. That landlord's share may **not** be recovered from the tenant. It therefore has to be deducted from the heating costs before the remaining amount is allocated to the tenants.
**Example:**
The external heating cost statement shows heating costs of **€1,000** for the unit. These include CO₂ costs of which **€30** are shown as the **landlord's share**.
The **landlord's share** of **€30** may **not** be recovered from the tenant. Only **€970** may therefore be taken into account as recoverable heating costs for the operating cost statement.
As there was a change of tenant in the billing year and the external heating cost statement does not take this change into account, you then allocate these **€970** manually to the tenancies concerned, for example by entering the costs in the category "[**Other operating costs (recoverable from tenant)**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10110010-sonstige-betriebskosten-umgelegt-auf-mieter.md)".
For this special case you can **deactivate** the automatic statement of the CO₂ tax and explain how the landlord's share was taken into account in the statement's [**Message to tenant free text field**](/en/anleitung/betriebskostenabrechnungen/betriebskostenabrechnung.md#message-to-tenant). Also enclose the external heating cost statement and your manual allocation as an [**annex to the operating cost statement**](/en/anleitung/betriebskostenabrechnungen/betriebskostenabrechnung.md#attaching-files).
**Example wording for an explanation in the free text field:**
> The heating cost statement of the WEG manager or the metering service provider was prepared for the unit's entire period and does not separately take into account the change of tenant on \[date]. The external heating cost statement shows heating costs of \[amount]. The landlord's share of the CO₂ costs contained in it is \[amount] and was not recovered from the tenant. Only the remaining amount of \[amount] was therefore taken into account for the operating cost statement and allocated manually to the tenancies concerned via the item "Other operating costs". The external heating cost statement and the manual allocation are enclosed as an annex.