> For the complete documentation index, see [llms.txt](https://help.immodio.app/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://help.immodio.app/en/anleitung/betriebskostenabrechnungen/relevante-buchungen/pauschale-vorauszahlung.md).
# Flat rate / advance payment
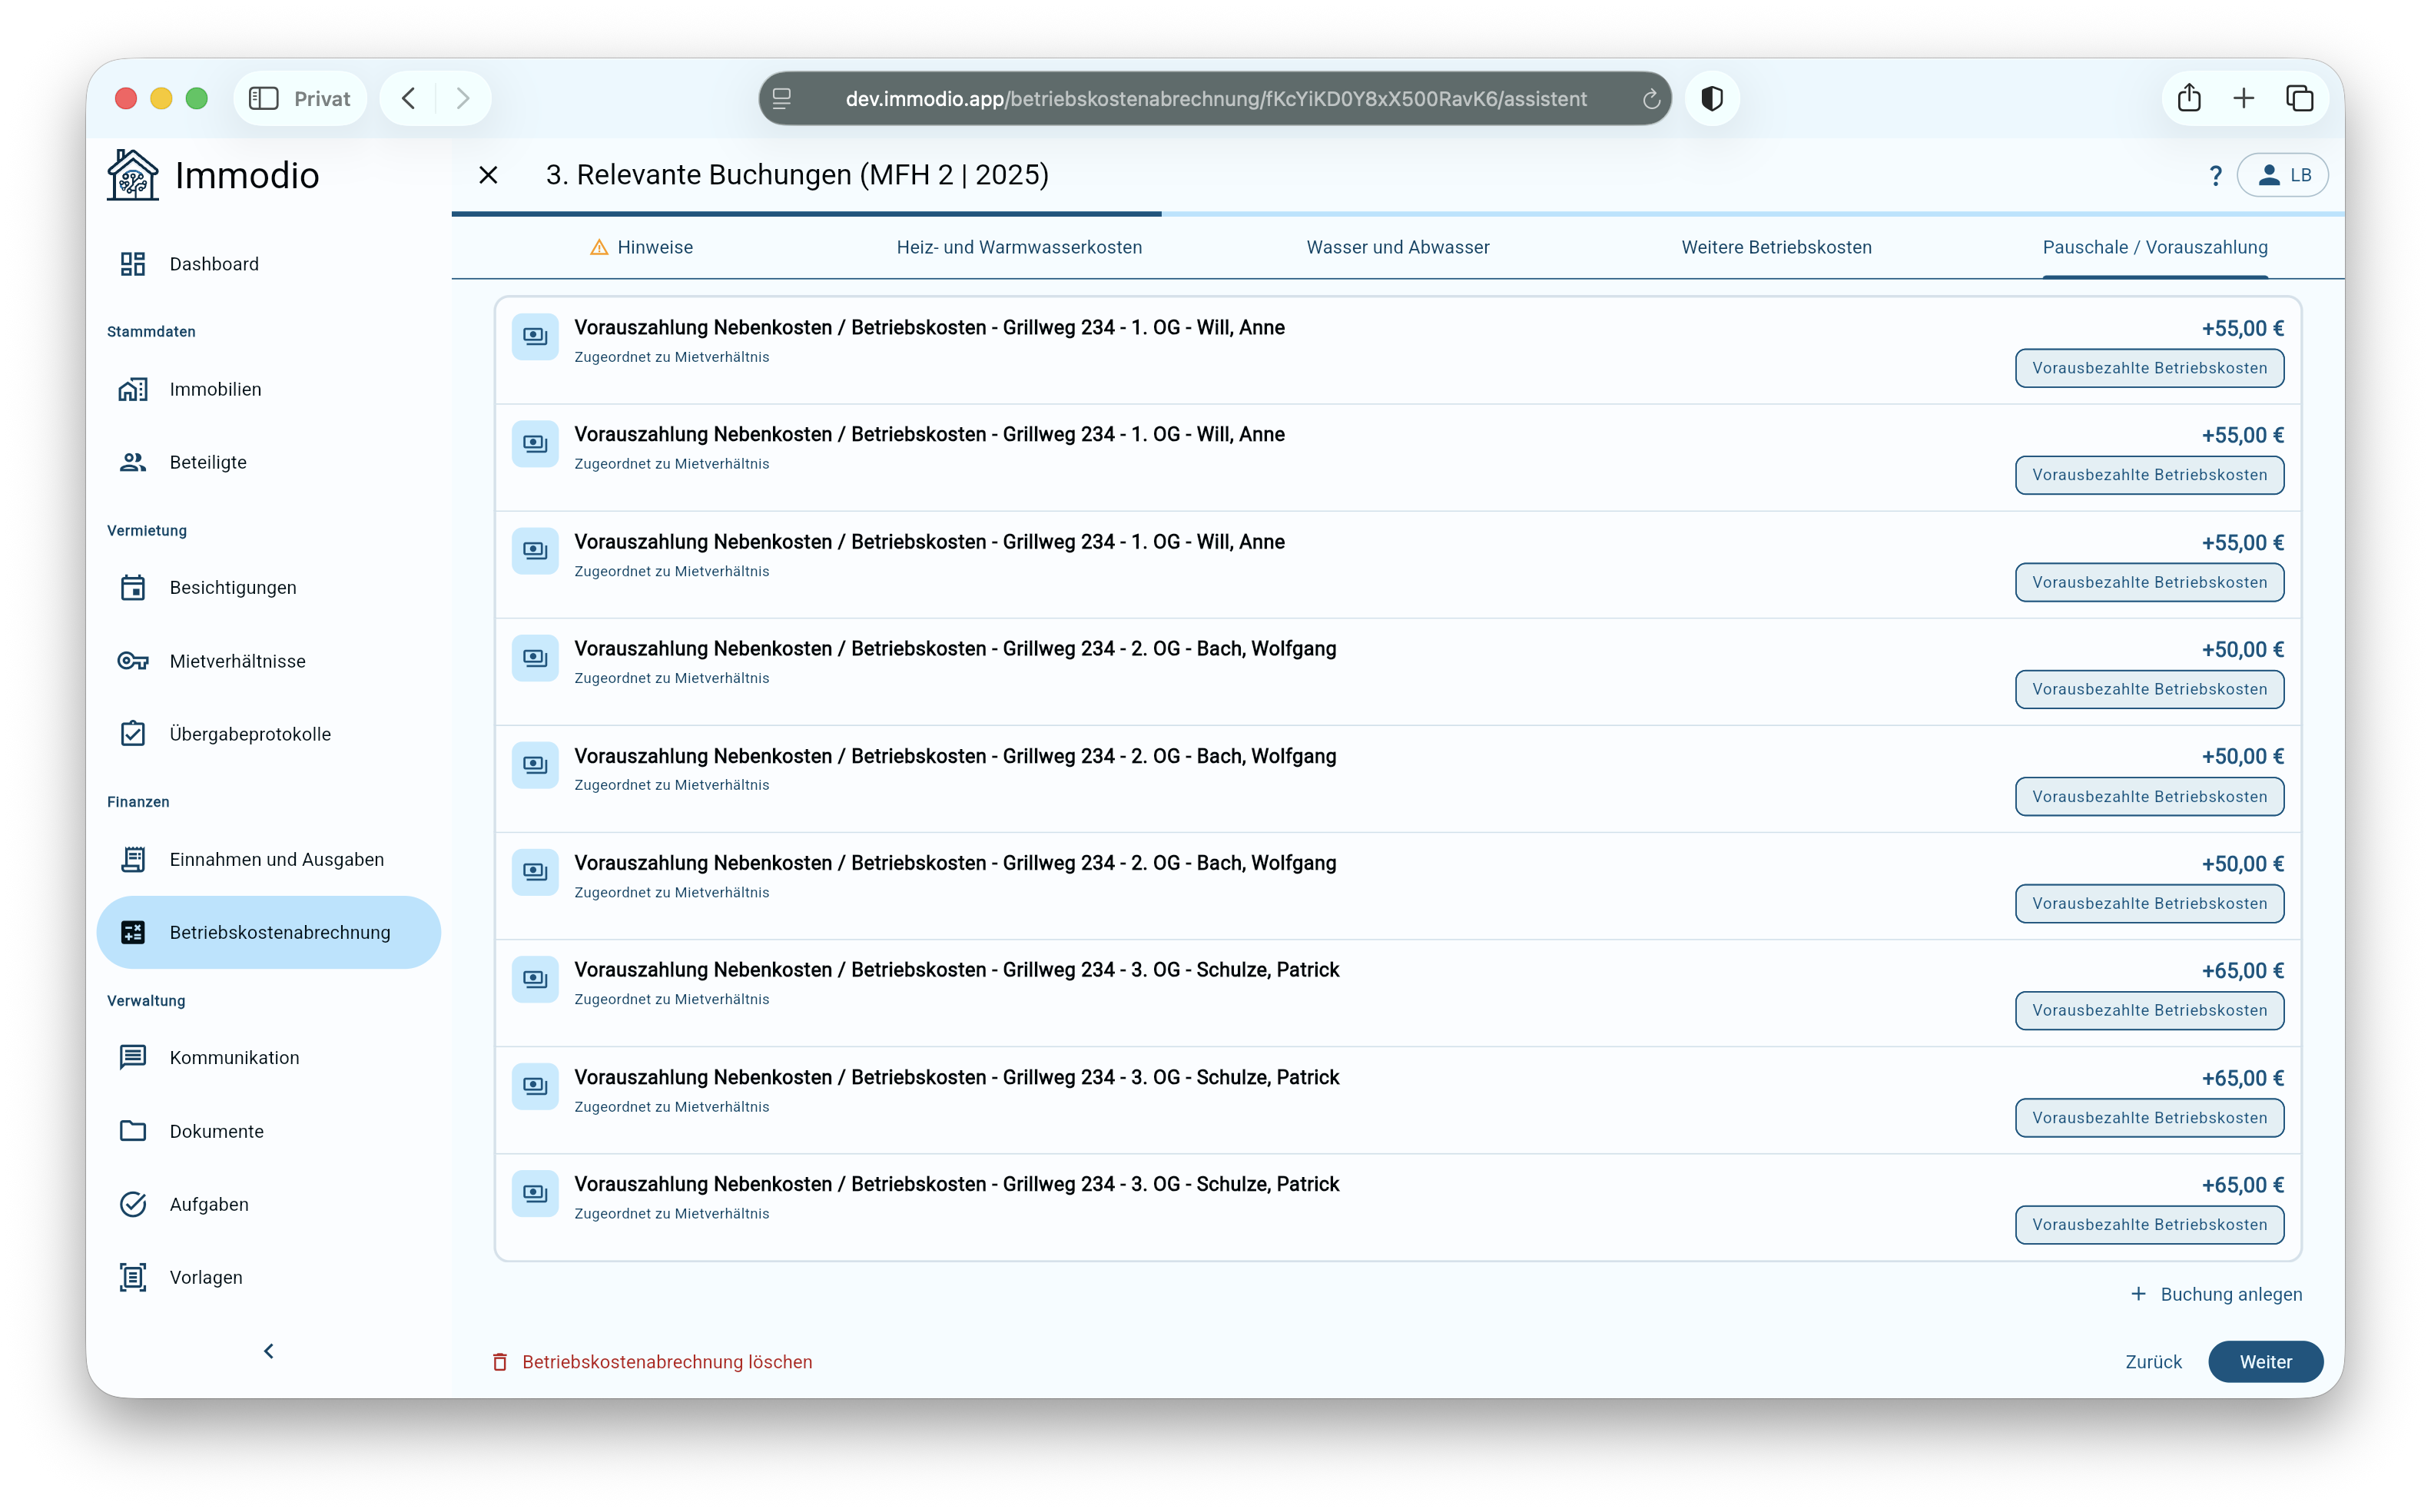
On this page you see all operating cost payments assigned to the individual tenancies in the settlement period.
A distinction is made between **advance payments** and **flat rates**.
* **Advance payments** are payments on account towards the operating costs to be billed later. They are deducted from the costs actually incurred in the operating cost statement. This can result either in a credit balance or in an additional payment for the tenant. You can find further information on advance payments for operating costs [here](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/vorauszahlung-der-betriebskosten.md).
* **Flat rates**, on the other hand, are fixed amounts which settle certain operating costs. Unlike advance payments they are not set off against the costs actually incurred. With operating costs agreed as a flat rate there is therefore usually neither an additional payment nor a credit balance. You can find further information on the flat rate for operating costs [here](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/pauschale-betriebskosten.md).
At this point, check that all payments are recorded in full, assigned to the right tenancy and marked correctly as an **advance payment** or a **flat rate**. The amounts listed here are then included in the operating cost statement according to their type.
If a payment is missing from this list, you can record a further entry using **"Create entry"**:
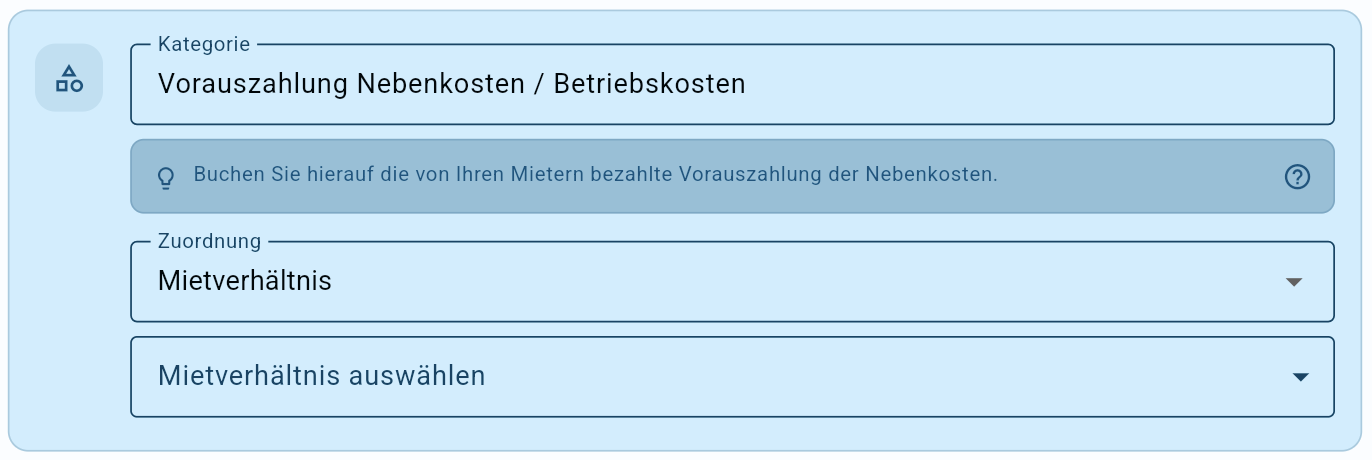
Advance payment of ancillary costs / operating costs
Use this category for amounts of ancillary costs or operating costs agreed with the tenant as a monthly **advance payment**.
Only record payments here that the tenant actually made as an **advance payment of ancillary or operating costs** and that belong to the settlement period. Advance payments that were not made should not be entered as a payment. They are first of all arrears on the tenant's part and would wrongly reduce the statement in the tenant's favour.
An **advance payment** is a payment on account towards the operating costs to be billed later. Unlike a **flat rate** it is set off against the costs actually incurred. This can result in a credit balance or an additional payment in the operating cost statement.
You can find further information on advance payments for operating costs [here](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/vorauszahlung-der-betriebskosten.md).
Also note whether an **advance payment** or a **flat rate** was agreed in the rental agreement. You can see this under [**Tenancy details**](/en/anleitung/mietverhaltnisse/mietverhaltnis-ubersicht/details-mietverhaltnis.md).
{% hint style="info" %}
**This category does not cover** the net base rent, rent deposits, additional payments from an operating cost statement already prepared or amounts of ancillary costs agreed as a flat rate.
{% endhint %}
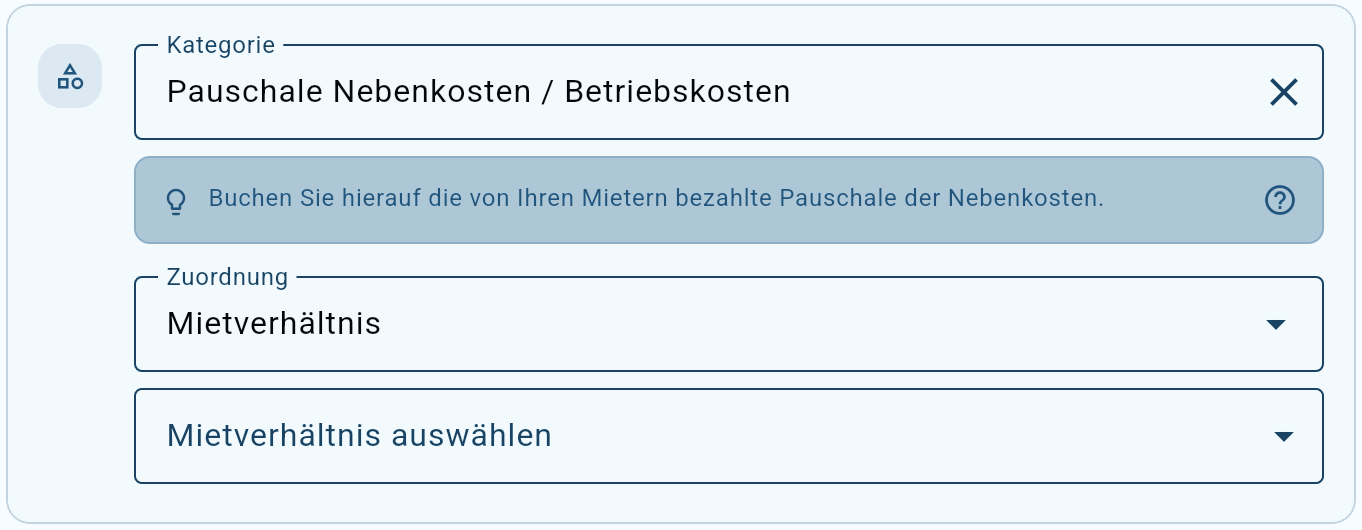
Flat rate for ancillary costs / operating costs
Use this category for **flat rate payments of ancillary or operating costs** which your tenant pays you in addition to the rent itself on the basis of an effectively agreed **flat rate for operating costs**.
With a flat rate for operating costs, landlord and tenant agree a **fixed amount** which in principle settles the operating costs covered by the flat rate.
#### **This category is only for a genuine flat rate for operating costs**
If your tenant pays, for example, per month:
* **Net base rent: €800**
* **Flat rate for operating costs: €200**
then you enter:
* **€800 per month in the category → "**[Net base rent, rental income for residential space (excluding ancillary costs)](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10089900-nettokaltmiete-mieteinnahmen-fuer-wohnraum-ohne-nebenkosten.md)**"** and
* **€200 per month in the category → "**[**Flat rate for ancillary costs / operating costs**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10099200-pauschale-nebenkosten-betriebskosten.md)**"**
#### **The key difference from an advance payment of operating costs**
A **flat rate for operating costs** and an **advance payment of operating costs** are not the same thing.
With an **advance payment**, the tenant first pays amounts on account during the year. The actual recoverable operating costs are determined later and compared with the advance payments made.
This can result in:
* an **additional payment by the tenant**
* or a **credit balance for the tenant**
With a **genuine flat rate for operating costs**, on the other hand, there is generally **no annual statement based on the costs actually incurred**. The agreed flat rate is precisely intended to settle the operating costs it covers on a flat rate basis.
The following therefore applies in Immodio:
* **Flat rate for operating costs** → **"**[**Flat rate for ancillary costs / operating costs**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10099200-pauschale-nebenkosten-betriebskosten.md)**"**
* **Advance payment of operating costs** → **"**[**Advance payment of ancillary costs / operating costs**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10144700-vorauszahlung-nebenkosten-betriebskosten.md)**"**
**An additional payment or refund from an annual statement**
→ only where advance payments are actually billed, in the category "[Additional payments / refunds of operating costs / ancillary costs](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10092700-nachzahlungen-erstattungen-fuer-wohnraum-umsatzsteuerfreie-vermietung.md)".
#### **A flat rate when letting to relatives**
Where residential space is let to a relative and a flat rate for operating costs is agreed, the special tax treatment of letting to relatives also has to be observed.
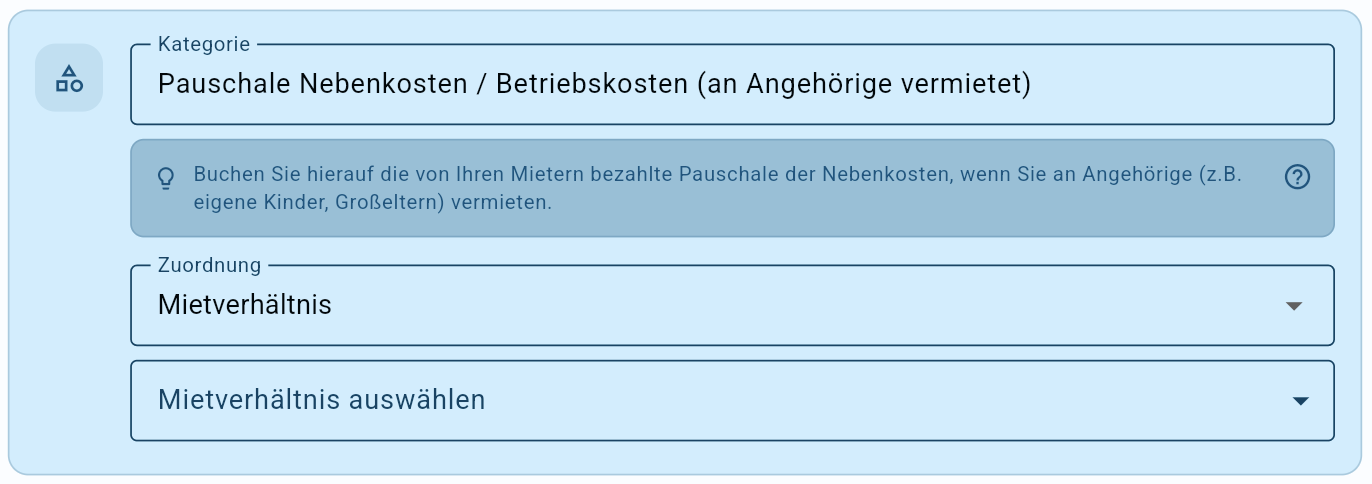
Income and recharges when letting to relatives have to be recorded separately. Use the category "[Flat rate for ancillary costs / operating costs (let to relatives)](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10099300-pauschale-nebenkosten-betriebskosten-an-angehoerige-vermietet.md)" for this
#### **Assignment in Immodio**
With this category the assignment is to the **tenancy.** Select the tenancy in which the flat rate for operating costs was actually agreed.
For this reason keep in particular:
* the rental agreement,
* the exact arrangement on the flat rate for operating costs,
* a list of the types of cost covered by the flat rate,
* notices of increases or reductions,
* and evidence of the flat rate amounts actually paid
permanently.
{% hint style="info" %}
You can find further information on the flat rate for operating costs [**here**](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/pauschale-betriebskosten.md).
{% endhint %}
***
### A special feature when letting to relatives
If you let an apartment to relatives, higher requirements apply to the tax documentation than with an ordinary tenancy. In Immodio you can therefore record the entries for ancillary cost payments from relatives separately:
Flat rate for ancillary costs / operating costs from relatives
Use this category for amounts of ancillary costs or operating costs where you let the property to **relatives** and a **flat rate** was agreed with them.
A **flat rate** is a fixed amount for agreed operating costs. Unlike an **advance payment** it is not set off against the costs actually incurred. As a rule there is therefore neither a credit balance nor an additional payment.
You can find further information on the flat rate for operating costs [here](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/pauschale-betriebskosten.md).
### A special feature when letting to relatives
With tenancies involving relatives, the amounts agreed should be documented particularly comprehensibly. The tax office regularly checks here whether the rental agreement is at arm's length and whether the payments are actually made as agreed.
For the tax assessment of the level of rent, the **gross rent** is generally considered. In addition to the base rent this includes the recoverable operating costs, for example an agreed flat rate for operating costs. Where the agreed gross rent actually paid is considerably below the local market rent, this can affect the deduction of income-related expenses.
{% hint style="info" %}
The Bavarian State Tax Office names in particular the thresholds of 66% and 50% of the local market rent for this. You can find further information [here](https://www.lfst.bayern.de/fileadmin/RESSOURCEN/INFORMATIONEN/Steuerinfos/Zielgruppen/Haus_und_Grund/2025-07-29_Merkblatt_zur_verbilligten_Vermietung.pdf). This is not tax advice and in individual cases a tax adviser should always be consulted.
{% endhint %}
Only record flat rates here that were actually agreed in the rental agreement and were also paid by the relative. Amounts that were not paid, were waived or were only offset internally should not be entered as a payment.
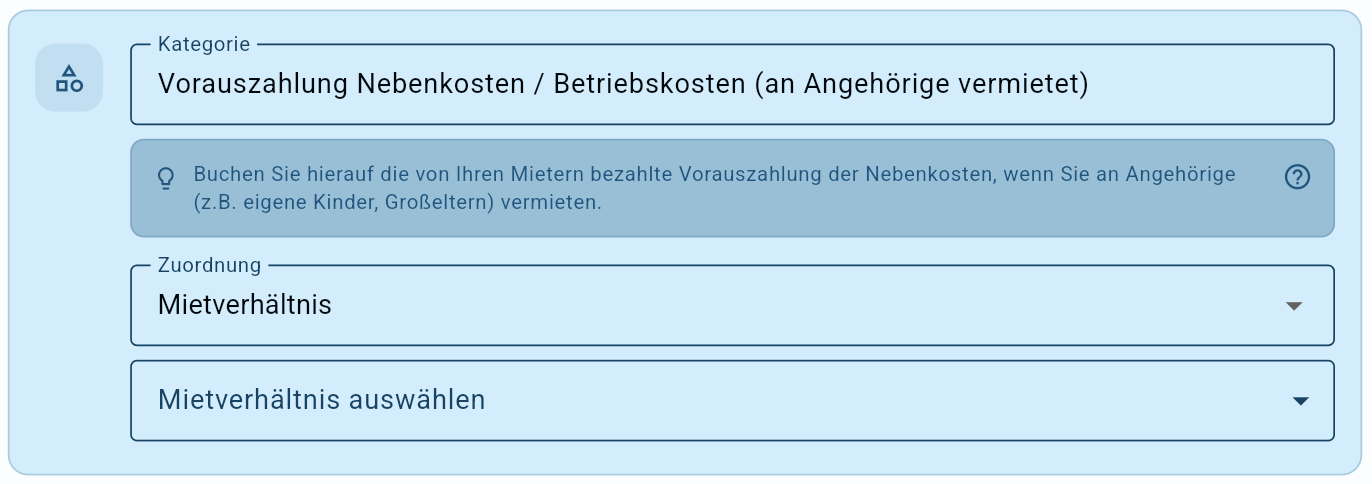
Advance payment of ancillary costs / operating costs from relatives
Use this category for advance payments of ancillary or operating costs where you let the property to relatives and an **advance payment** was agreed with them.
An advance payment is a payment on account towards the operating costs to be billed later. Unlike a flat rate it is set off against the costs actually incurred. This can result in a credit balance or an additional payment in the operating cost statement.
You can find further information on advance payments for operating costs [here](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/betriebskosten/vorauszahlung-der-betriebskosten.md).
### A special feature when letting to relatives
With tenancies involving relatives, the amounts agreed and actually paid should be documented particularly comprehensibly. The tax office regularly checks here whether the rental agreement is at arm's length and whether the payments are actually made as agreed.
For the tax assessment of the level of rent, the **gross rent** is generally considered. In addition to the base rent this includes the recoverable operating costs, for example an agreed advance payment of operating costs. Where the agreed gross rent actually paid is considerably below the local market rent, this can affect the deduction of income-related expenses.
{% hint style="info" %}
The Bavarian State Tax Office names in particular the thresholds of 66% and 50% of the local market rent for this. You can find further information [here](https://www.lfst.bayern.de/fileadmin/RESSOURCEN/INFORMATIONEN/Steuerinfos/Zielgruppen/Haus_und_Grund/2025-07-29_Merkblatt_zur_verbilligten_Vermietung.pdf). This is not tax advice and in individual cases a tax adviser should always be consulted.
{% endhint %}
Only record advance payments here that were actually agreed in the rental agreement and were also paid by the relative. Amounts that were not paid, were waived or were only offset internally should not be entered as a payment.
***
### A special feature when letting garages and commercial premises
With advance payments for garages, parking spaces, commercial premises or other premises not let for residential purposes, special VAT rules can apply. Immodio therefore has its own categories for payments recorded with 19% VAT. The following explains when this category is used and what you should note when making the entry.
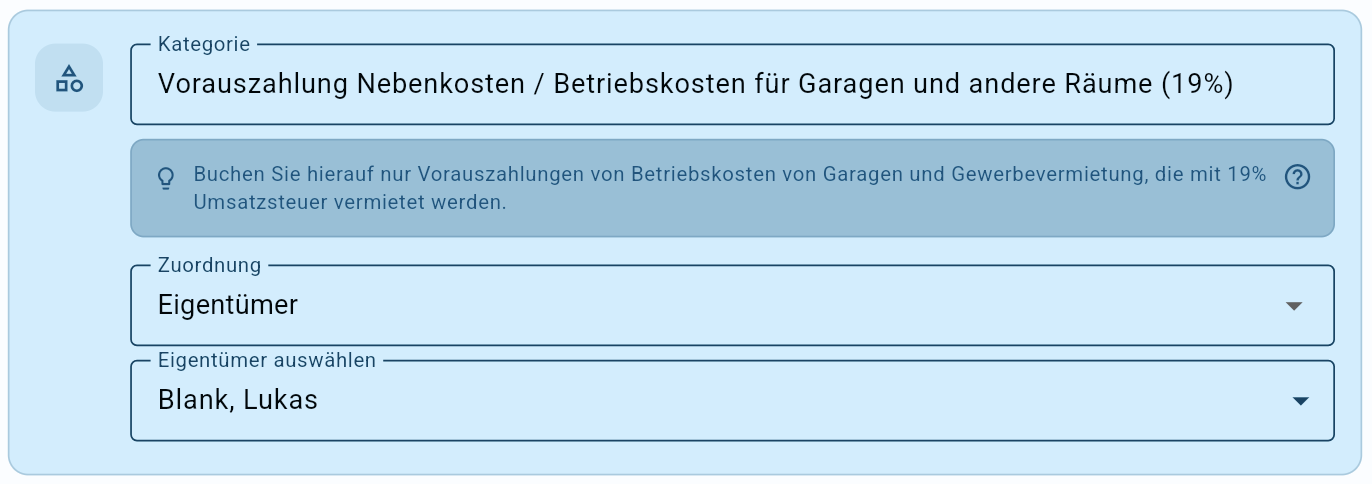
Advance payment of ancillary costs / operating costs for garages and other premises with 19% VAT
Use this category for advance payments of operating costs agreed for garages, parking spaces, commercial premises or other premises with **19% VAT**.
Only enter advance payments here where the letting is actually **subject to VAT** **and the operating costs are also billed with VAT**. The payment is later set off against the operating costs actually incurred.
{% hint style="info" %}
Assign the entry not to a tenancy but to the respective **owner** (usually yourself).
{% endhint %}
### A special feature with garages and parking spaces
With garages and parking spaces, what matters is whether they are let separately or together with an apartment.
Where a garage or a parking space is let **separately**, the letting can be subject to VAT. In that case the associated advance payments of operating costs are also recorded with 19% VAT.
Where the garage or parking space is let together with a VAT-exempt apartment to the same tenant, on the other hand, it is often regarded as an ancillary service to the residential tenancy. In that case **no** VAT usually arises and this category should not be used.
### A special feature with commercial letting
Commercial premises are also let VAT-exempt in principle at first. Under certain conditions, however, the landlord can opt for VAT. That is possible in particular where the tenant is a business and uses the premises for turnover that does not exclude the deduction of input VAT.
Where VAT was effectively opted for, the advance payments of operating costs are billed with 19% VAT in addition to the rent. In the later operating cost statement the costs have to be treated with VAT accordingly. The standard rate of tax is 19%.
### Do not enter in this category
The following do not belong in this category:
* ordinary advance payments of operating costs for VAT-exempt residential tenancies
* advance payments for garages or parking spaces let together with a VAT-exempt apartment
* advance payments without agreed VAT
* flat rates for operating costs
* the base rent or the garage rent itself
* additional payments from a statement already prepared
Where the landlord uses the small business rule, no VAT may generally be shown. In that case this 19% category should not be used. Since 2025 the small business threshold has been €25,000 of turnover in the previous year and €100,000 of turnover in the current year.
{% hint style="info" %}
Only use this category where the rental agreement, the invoice and the tax treatment fit together. With commercial premises in particular, it should be clearly agreed that the rent and the operating costs are owed plus statutory VAT.
{% endhint %}
{% hint style="danger" %}
**Note:** This information is intended only as general guidance and expressly does not replace tax advice. Whether VAT has to be shown in an individual case should be clarified with a tax adviser.
{% endhint %}
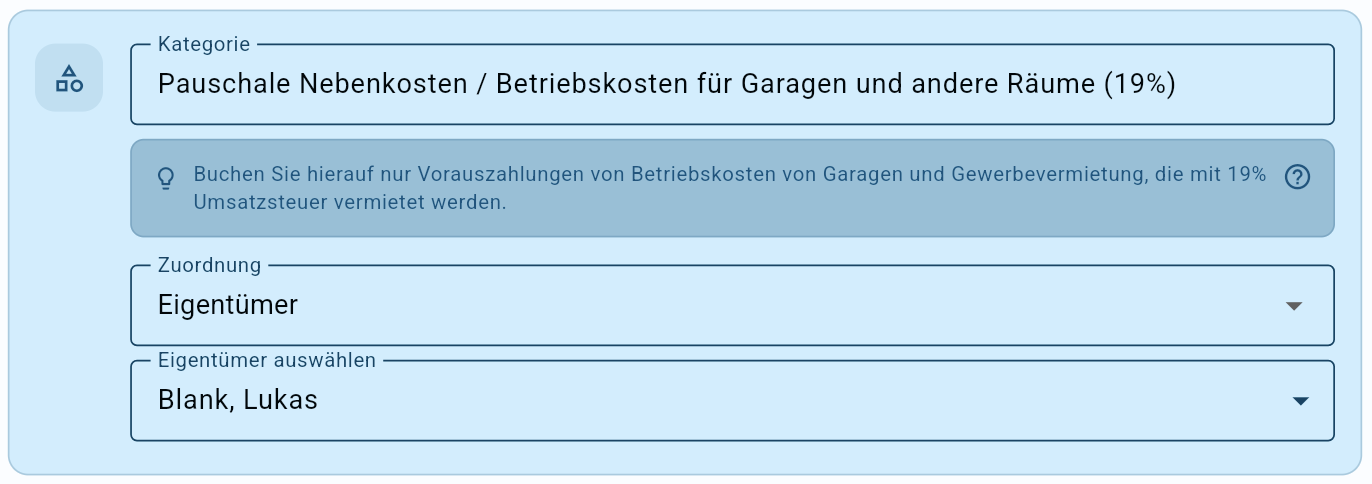
Flat rate for ancillary costs / operating costs for garages and other premises with 19% VAT
Use this category for amounts of ancillary costs or operating costs agreed for garages, parking spaces, commercial premises or other premises as a **flat rate with 19% VAT**.
A **flat rate** is a fixed amount for agreed operating costs. Unlike an advance payment it is not set off against the costs actually incurred. As a rule there is therefore neither a credit balance nor an additional payment.
{% hint style="info" %}
Assign the entry not to a tenancy but to the respective **owner** (usually yourself).
{% endhint %}
### A special feature with garages and parking spaces
With garages and parking spaces, what matters is whether they are let separately or together with an apartment.
Where a garage or a parking space is let **separately**, the letting can be subject to VAT. In that case the associated advance payments of operating costs are also recorded with 19% VAT.
Where the garage or parking space is let together with a VAT-exempt apartment to the same tenant, on the other hand, it is often regarded as an ancillary service to the residential tenancy. In that case **no** VAT usually arises and this category should not be used.
### A special feature with commercial letting
Commercial premises are also let VAT-exempt in principle at first. Under certain conditions, however, the landlord can opt for VAT. That is possible in particular where the tenant is a business and uses the premises for turnover that does not exclude the deduction of input VAT.
Where VAT was effectively opted for, the advance payments of operating costs are billed with 19% VAT in addition to the rent. In the later operating cost statement the costs have to be treated with VAT accordingly. The standard rate of tax is 19%.
### Do not enter in this category
The following do not belong in this category:
* ordinary flat rates for operating costs for VAT-exempt residential tenancies
* flat rates for garages or parking spaces let together with a VAT-exempt apartment
* flat rates without agreed VAT
* advance payments of operating costs
* the base rent or the garage rent itself
* additional payments from a statement already prepared
Only use this category where the flat rate was actually agreed with **19% VAT**.
{% hint style="info" %}
Where the landlord uses the small business rule, no VAT may generally be shown. In that case this 19% category should not be used. Since 2025 the small business threshold has been €25,000 of turnover in the previous year and €100,000 of turnover in the current year.
{% endhint %}
{% hint style="danger" %}
**Note:** This information is intended only as general guidance and expressly does not replace tax advice. Whether VAT has to be shown in an individual case should be clarified with a tax adviser.
{% endhint %}