> For the complete documentation index, see [llms.txt](https://help.immodio.app/llms.txt). Markdown versions of documentation pages are available by appending `.md` to page URLs; this page is available as [Markdown](https://help.immodio.app/en/anleitung/betriebskostenabrechnungen/relevante-buchungen/weitere-betriebskosten.md).
# Further operating costs
### Usual entries for the "Other operating costs" part
In this area you will find typical types of cost that are frequently recorded under **Other operating costs** as part of the statement.
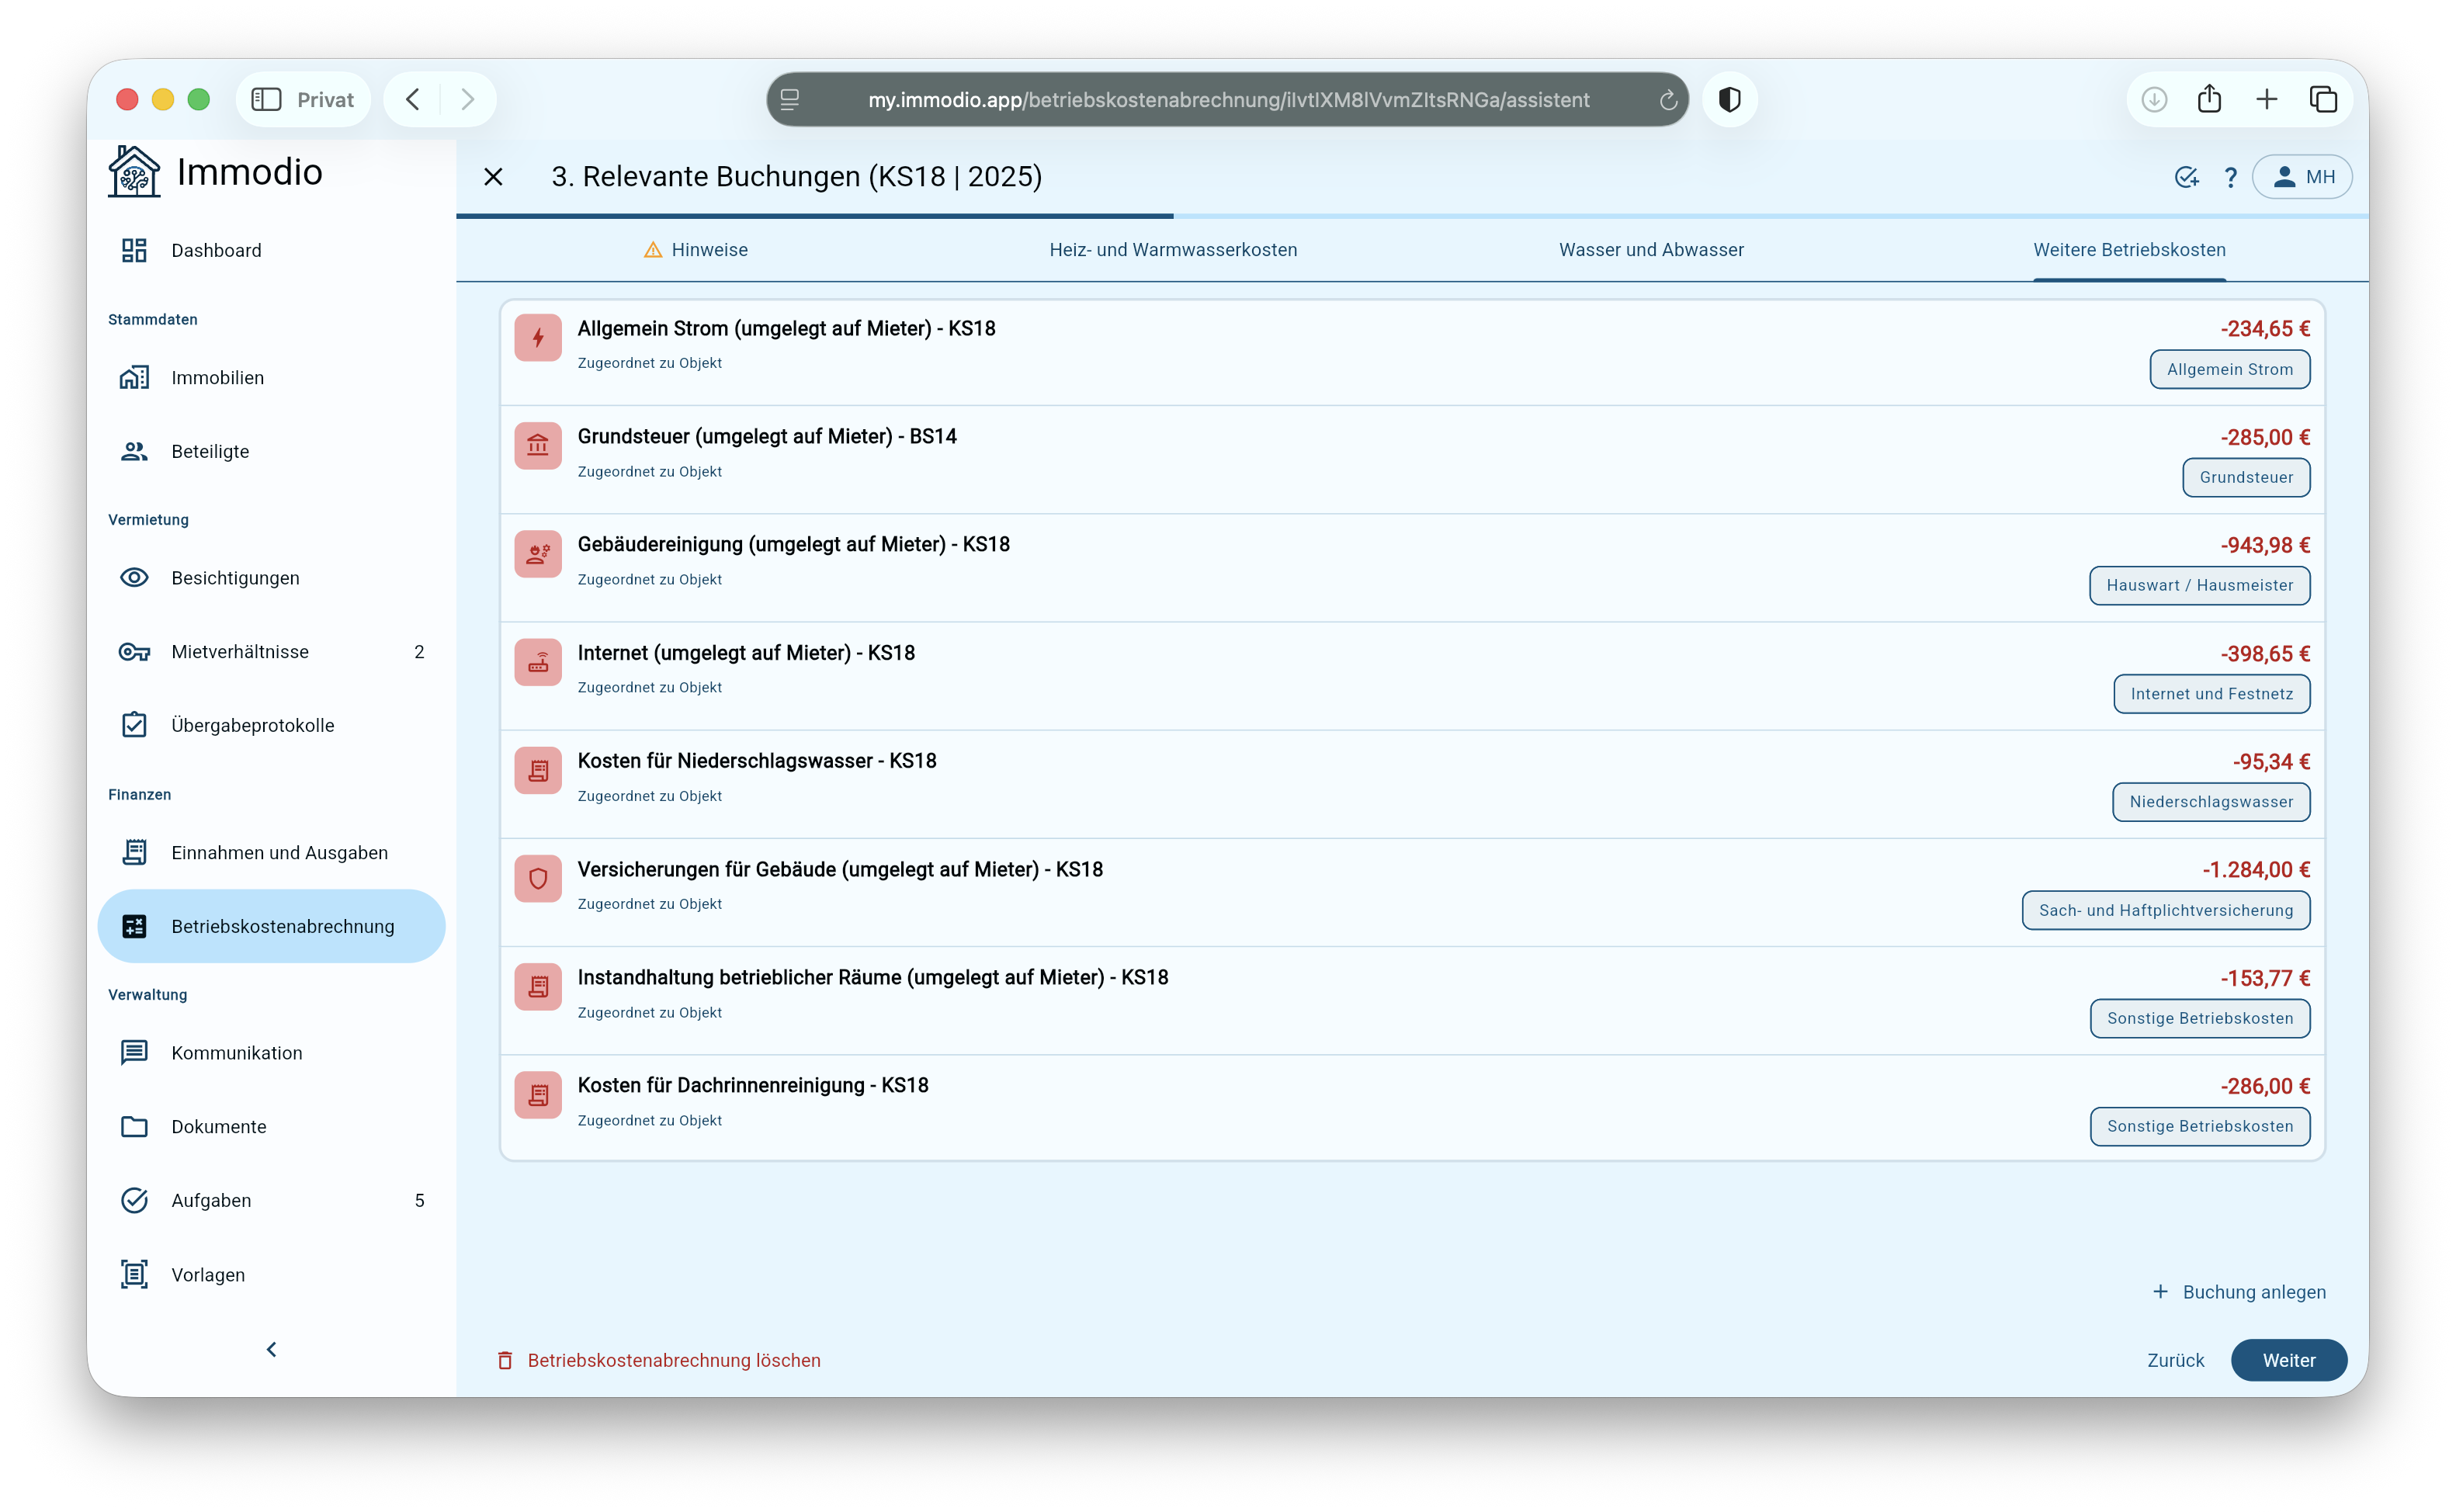
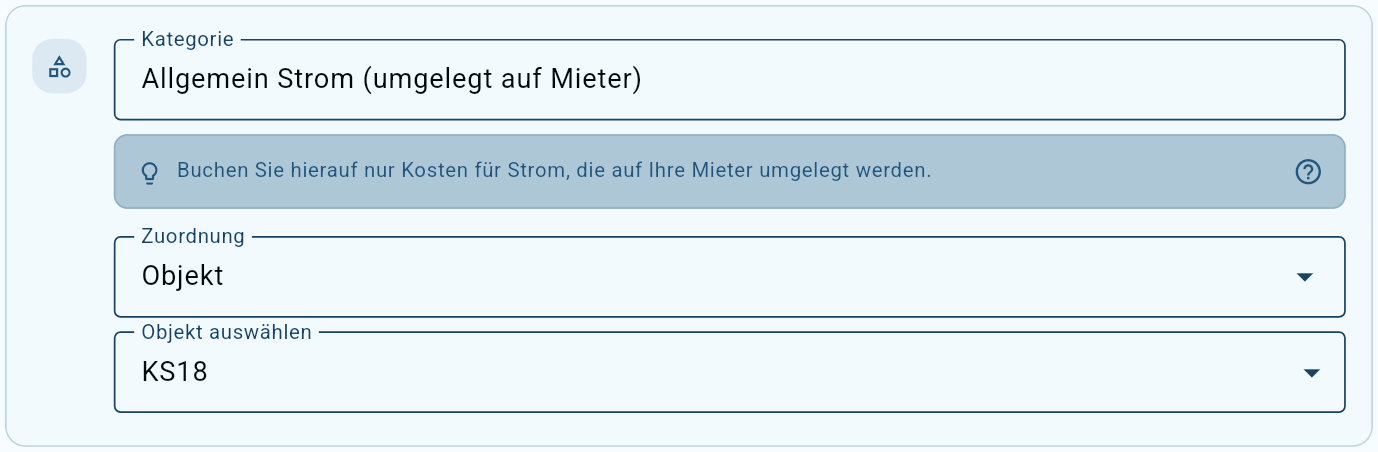
Communal electricity (recoverable from tenant)
Use this category for the **running electricity costs of the communal lighting** of the building and the property. These include in particular the outdoor lighting and the lighting of accesses, entrance areas, corridors, stairwells, cellars, attics and communal laundry rooms. These lighting costs are listed as operating costs in Section 2 no. 11 of the Operating Costs Ordinance.
#### What can be entered here?
This can include, for example:
* electricity for the stairwell and corridor lighting,
* electricity for communal entrance areas,
* electricity for cellar and attic lighting,
* electricity for communal laundry rooms,
* electricity for the outdoor lighting,
* electricity for lit accesses, private paths or yards,
* the share of the basic price, meter rental and other running components of the electricity bill attributable to this lighting.
{% hint style="info" %}
This requires the electricity costs concerned actually to be attributable to the communal lighting of the selected property.
{% endhint %}
#### Assignment
For the assignment select **"Property"** and then the property concerned.
The costs are thereby assigned to the entire property and allocated to the associated tenancies as part of the operating cost statement.
Recovering them from the tenants generally requires the assumption of the operating costs to have been agreed in the rental agreement (in the Immodio rental agreement these operating costs are of course taken into account). Where no other effective allocation key was set, operating costs are allocated automatically according to the share of the living space.
#### When this category should not be used
Do **not** enter the individual electricity consumption within individual apartments or commercial units here. This is usually billed directly by the respective user with their electricity supplier.
{% hint style="warning" %}
The operating electricity of a central heating system is expressly part of the **heating costs** and may **not** be allocated as communal electricity together with the lighting electricity. Use the category **"Operating electricity, electricity for the heating"** for it.
{% endhint %}
**Important**: Only enter **running consumption costs** here.
The following in particular do not belong in this category:
* buying new light fittings,
* replacing lamps or bulbs,
* repairs to light fittings, switches or motion detectors,
* repairs to electrical wiring,
* installing a new lighting system,
* modernisation and renewal measures.
By law, maintenance and repair costs are not operating costs. Replacement bulbs are generally also not classified as recoverable maintenance costs.
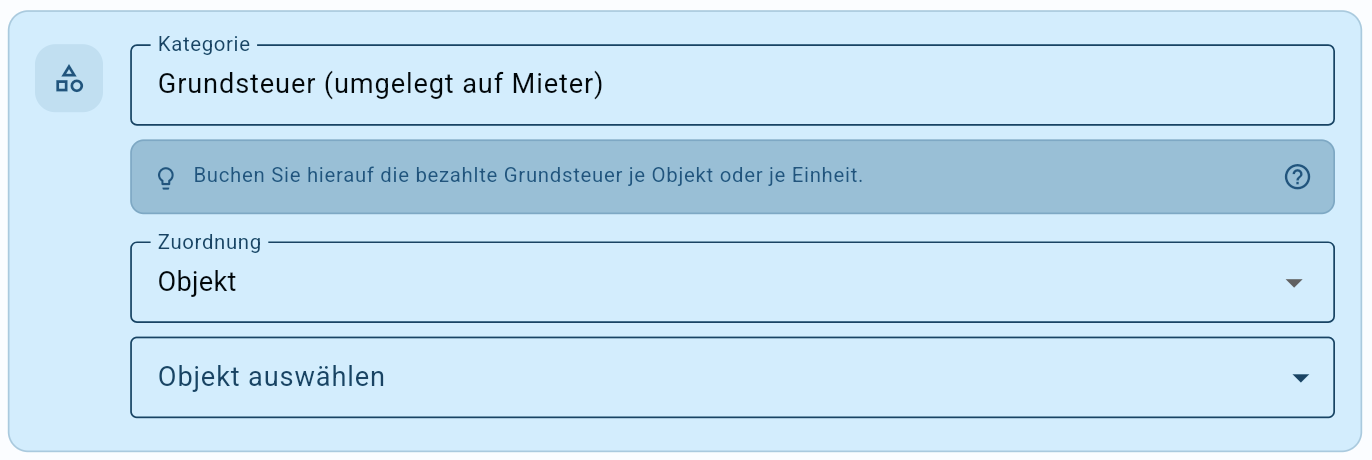
Property tax (recoverable from tenant)
Use this category for the **property tax paid** which was incurred for the property or an individual unit.
Property tax is a recoverable operating cost. Section 2 no. 1 BetrKV expressly names it as part of the "running public charges on the land". Recovering it from the tenant requires the allocation of operating costs to have been agreed in the rental agreement.
#### What can be entered here?
Enter the property tax here in accordance with the property tax assessment from the municipality or city.
That can be, for example:
* the annual property tax for an apartment building
* a quarterly payment of the property tax
* the property tax for a single freehold apartment
* the property tax for a unit let within a WEG
Since 2025 property tax has been levied under new rules and new municipal multipliers. For settlement periods from 2025 onwards, therefore, use the current property tax assessment.
#### Assignment
* For the assignment select **"Property"** where the property tax is incurred for the entire property.
* Select **"Unit"** where the property tax was charged to you directly for a single unit or freehold apartment.
#### Important
Only enter the property tax itself here. The following, for example, do **not** belong in this category:
* real estate transfer tax
* reminder fees, late payment penalties or surcharges for late filing
* the costs of appeals, tax advice or legal advice
{% hint style="info" %}
With mixed-use properties, that is with residential and commercial units in one building, a prior deduction for commercial use is generally not automatically required for property tax under the case law of the Federal Court of Justice. The court has ruled on this: **BGH, judgment of 10/05/2017 – VIII ZR 79/16**. The provisions of the rental agreement and the specific structure of the property should nevertheless be checked.
{% endhint %}
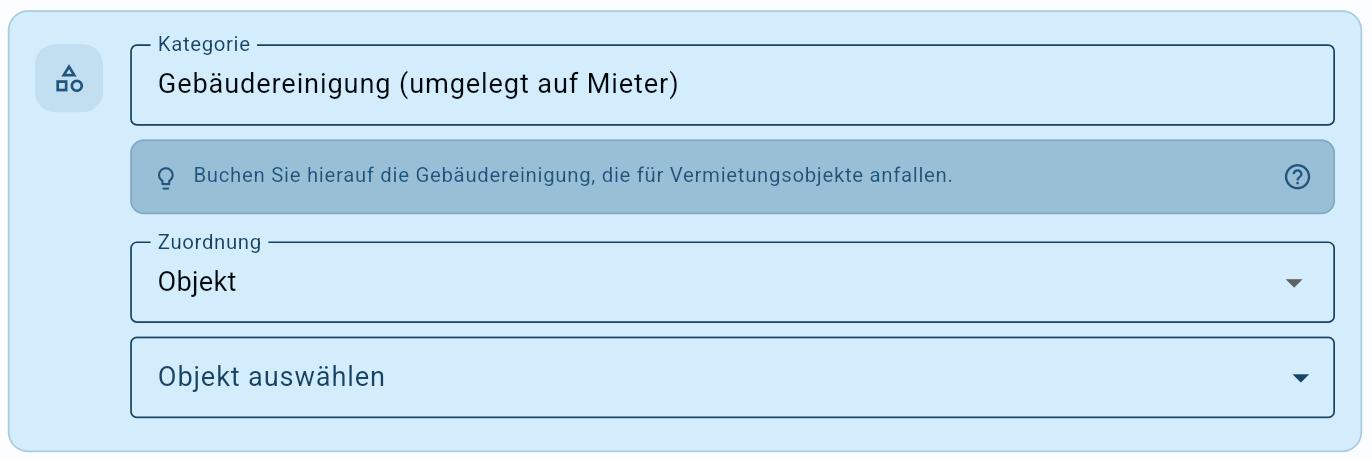
Building cleaning (recoverable from tenant)
## Building cleaning
Use this category for the running costs of building cleaning that are to be assigned to a rental property and recovered from the tenants as part of the operating cost statement.
The category is intended for cleaning costs concerning parts of the building used communally. These include, for example:
* the stairwell
* corridors and entrance areas
* cellar corridors
* laundry rooms
* attic rooms
* shared accesses
* the car of a lift
### Cleaning materials and the cleaning service
Invoices from an external cleaning service can be recorded in this category where they concern the running cleaning of parts of the building used communally. Cleaning materials needed regularly can typically also belong here, for example cleaning products for cleaning the stairwell.
Purchases of cleaning equipment or durable working equipment, on the other hand, are not readily recoverable, for example:
* vacuum cleaners
* brooms / mops
* buckets
* cleaning machines
{% hint style="info" %}
These purchases should **not** be recorded **as recoverable costs of building cleaning**. Maintenance or repair costs for mechanical cleaning aids can be an exception. These can be recoverable where they arise in connection with the running building cleaning.
{% endhint %}
### The landlord's own work
Where the landlord does the cleaning themselves, materials and work can in principle be applied as operating costs.
An arbitrarily chosen amount may not simply be entered, however. As a rule the measure is the amount that would have arisen for an **equivalent service by a third party**.
### Important to know
In principle only running, regularly recurring costs of building cleaning are recoverable.
One-off special cleaning should be checked before it is entered, as it often is not a recoverable operating cost.
The following, for example, do not belong, or do not readily belong, in this category:
* cleaning after building or refurbishment work
* removing exceptional soiling
* facade cleaning
Caretaker, winter services, snow clearing (recoverable from tenant)
Use this category for the **running and recoverable costs of a caretaker or caretaking service** and for the costs of winter services and clearing snow and ice at the selected property.
In law two types of operating cost are combined here:
* caretaker costs under Section 2 no. 14 BetrKV,
* winter services and snow clearing as non-public street cleaning measures under Section 2 no. 8 BetrKV.
Caretaker costs include the remuneration, the social security contributions and benefits in kind, as far as the activity does **not** serve administration, repair, maintenance, refurbishment, renewal or the carrying out of decorative repairs.
### What can be entered here?
#### Running caretaker costs
The following in particular can be entered here:
* the running remuneration of an employed caretaker,
* the employer's contributions and social security charges,
* benefits in kind valued comprehensibly,
* invoices from an external caretaking service,
* regular checking, tidying, cleaning and maintenance work,
* the running costs of winter services,
* labour costs for clearing snow and ice,
* grit used, such as chippings or permitted road salt,
* the travel and call-out costs of a winter service company.
With an external caretaking company, the contract and the invoice have to show which services are actually provided. A blanket description such as "caretaking service" is not sufficient for the internal check where it may also include repair or administrative work.
### Which caretaking activities are recoverable?
Recoverable activities can be in particular **routine work for the safety, order, cleaning and upkeep** of the communal areas.
This can include, for example:
* checking the communal corridors, stairwells, cellars and outdoor areas,
* checking that rescue and escape routes are kept clear,
* checking that house and cellar doors close properly,
* checking freely accessible drains on the property,
* checking that the lighting of communal areas works,
* routine visual checks of the building services,
* checking communal glass surfaces for identifiable hazards,
* monitoring compliance with the house rules,
* checking the stairwell cleaning,
* checking the winter service,
* cleaning communal areas,
* putting out and returning refuse bins,
* garden maintenance and looking after communal outdoor areas,
* clearing snow and ice.
### Winter services and snow clearing
Recoverable winter services can include in particular:
* clearing snow from pavements and accesses,
* removing snow from private paths used communally,
* gritting where there is snow and ice,
* repeated clearing or gritting,
* removing patches of ice,
* clearing accesses to refuse areas, garages or parking spaces,
* grit used,
* the costs of an engaged winter service company.
Which areas, times and grit are involved depends on the local rules, the nature of the property and the service assumed under the contract.
### The contractual requirement
Caretaker costs and the costs of non-public street cleaning measures are expressly listed in the Operating Costs Ordinance. With residential space an effective agreement under which the tenant bears the operating costs in accordance with the Operating Costs Ordinance is therefore generally sufficient, and this is implemented accordingly in the Immodio rental agreement.
Where the rental agreement instead lists only individual operating costs expressly, it has to be checked whether the caretaker and the winter service are covered by that list.
### Assignment
For the assignment select **"Property"** and then the building for which the caretaking or winter service costs were incurred.
The costs are assigned to the selected property and allocated to the associated tenancies as part of the operating cost statement.
Where no other effective allocation key was agreed, allocation in residential tenancies is generally according to the share of the living space.
### Splitting mixed caretaker contracts
Caretakers frequently perform both recoverable and non-recoverable activities. It should therefore be checked which share of the work actually relates to operating costs.
Where the contract contains the following tasks, for example:
* regular property checks,
* cleaning the stairwell,
* winter services,
* repairing minor damage,
* handovers of apartments,
* dealing with tenant enquiries,
only the shares for the regular checks, the cleaning and the winter service may be allocated to the tenants.
A blanket deduction, of five or ten per cent for non-recoverable activities for example, is not sufficient if the tenant disputes the statement. The landlord has to break down comprehensibly the actual activities and the time each of them takes. The burden of presentation and proof for the recoverable caretaker costs lies with the landlord.
The following are therefore helpful:
* a detailed schedule of services,
* records of work or activities,
* time records,
* a separate price breakdown,
* property-related service reports.
### When this category should not be used
The following in particular do not belong here:
* repairs and remedying faults,
* replacing defective components,
* maintenance and refurbishment work,
* renewal and modernisation measures.
{% hint style="info" %}
Maintenance and repair costs are not operating costs and have to be borne by the landlord.
{% endhint %}
### The caretaker's emergency service flat rates
A general emergency service flat rate under which the caretaker receives reports of faults such as burst water pipes, heating or power failures outside business hours and then organises repairs is **not** recoverable.
The Federal Court of Justice regards such general availability as an administrative activity. The fact that being contactable also benefits the tenants does not make it a recoverable operating cost service.
This has to be distinguished from emergency call facilities required by law or technically for particular installations, such as a lift. These belong in the category **"Lift maintenance (recoverable from tenant)"** and not to the general caretaker costs.
### Damage and exceptional call-outs
Costs arising because of specific damage or a defect are not recoverable simply because the caretaker carries out the work.
The following are not recoverable, for example:
* dealing with a burst pipe,
* repairing a defective door,
* replacing a lock,
* repairing a lighting system,
* sealing a leaking roof,
* repairing a damaged fence,
* dealing with storm damage.
Where a particular tenant caused damage culpably, there may be an individual claim for damages against that tenant. The costs may not, however, be allocated as caretaker costs to all tenants across the board.
### Where the landlord carries out the work themselves
Where the landlord carries out caretaking work or the winter service themselves, their own materials and work can in principle be applied at the amount a suitable third party would have charged for an equivalent service.
Notional VAT may **not** be applied where it did not actually arise.
The following should be documented:
* the date and duration of the work,
* the activities actually carried out,
* the areas looked after or cleared,
* the grit used,
* the market comparison price used,
* the source of the comparison price.
### Economic efficiency and documents
With caretaking and winter service costs too, the landlord has to observe the requirement of economic efficiency. A particularly comprehensive or expensive contract can be justified, for instance because of a large plot, difficult accesses or high requirements for traffic safety. The scope and the price must, however, be in reasonable proportion to the service actually needed.
Keep in particular:
* the caretaking or winter service contract,
* a detailed schedule of services,
* invoices and proof of payment,
* records of activities and hours,
* payroll statements and employer costs,
* the split between recoverable and non-recoverable activities,
* clearing and gritting plans,
* records of winter service call-outs,
* the allocation where there are several buildings,
Tenants can ask to inspect the receipts underlying the operating cost statement.
Maintenance of operational rooms (recoverable from tenant)
Use this category for the costs of maintaining **commercially let premises** where the commercial rental agreement expressly and effectively transfers the maintenance obligation concerned to the tenant.
Without such an agreement the landlord is generally obliged to keep the rented property in a condition suitable for use in accordance with the contract during the tenancy. Maintenance and repair costs are also expressly **not ordinary operating costs**. They therefore cannot be passed on solely on the basis of a general agreement on the allocation of operating costs.
#### What can be entered here?
Only enter costs here that
* concern the commercial premises let directly,
* are to be borne by the commercial tenant under the commercial rental agreement,
* were caused by the contractual use of the premises or fall within the tenant's sphere of risk,
* and cannot be assigned to a more specific cost category.
Depending on the specific contractual provision, this can include, for example:
* running maintenance work on doors and locks used exclusively by the tenant,
* maintaining window fittings within the commercial unit,
* smaller maintenance measures on sanitary items and fittings in the rented premises,
* maintaining switches, sockets or other installations within the commercial unit,
* looking after and maintaining facilities made available exclusively to the tenant,
* maintenance measures on tenant-specific technical systems assumed under the contract,
* other maintenance work within the rented premises, as far as it is attributable to the tenant's use or area of responsibility.
{% hint style="info" %}
With a standard form rental agreement provided by the landlord, the maintenance obligation may not be transferred to the commercial tenant without limitation. A transfer can be permissible in particular where it is limited to the rented premises and to damage or wear arising from the use of the premises or from the tenant's sphere of risk.
{% endhint %}
#### Check the contractual agreement
Before making the entry, check the corresponding provision in the commercial rental agreement. The clause should set out as clearly as possible:
* which rooms, components and systems are covered,
* whether only maintenance or also repair is assumed,
* which damage and wear the tenant has to bear,
* whether a cost ceiling was agreed,
* how areas used communally are allocated,
* whether certain parts of the building are expressly excluded.
A blanket wording such as "the tenant bears all maintenance costs" can be problematic, particularly in standard terms and conditions. Contractual clauses have to be clear and understandable and may not impose an incalculable or unreasonable cost risk on the tenant.
#### Communal areas and technical systems
Particular care is needed where the costs relate to areas or systems used communally, for example:
* corridors and stairwells,
* communal sanitary facilities,
* car parks and driveways,
* lifts,
* central ventilation or air conditioning systems,
* main pipes and cables,
* communal doors and gates.
Transferring the maintenance and repair costs of such communal areas by standard form is generally invalid without an appropriate limit on the amount. The tenant would otherwise also bear costs for wear already present, for damage caused by other users or for parts of the building they cannot influence.
Where the commercial rental agreement contains an effective cost ceiling, only the amounts within that limit may be recorded and passed on. Costs above it remain with the landlord.
#### Assignment
For the assignment select **"Tenancy"** and then the tenancy concerned.
Where an invoice concerns several commercial units, the amount has to be split by a measure agreed contractually or by an appropriate and comprehensible measure.
#### The distinction from repairs and renewals
As a rule, do not use this category for:
* extensive repairs,
* replacing completely worn out components,
* renewals due to age,
* modernisation measures,
* the initial installation of new facilities,
* remedying defects already present at the start of the tenancy,
* damage from ageing or the weather outside the tenant's sphere of risk,
* damage caused by other tenants or other third parties,
* work on the roof, the facade or load-bearing parts of the building,
* repairs to central main pipes and cables or to the general building fabric.
Such measures are in principle within the landlord's area of responsibility, unless there is an effective agreement to the contrary that is permissible in the specific case. Transferring incalculable costs to the commercial tenant by standard form can breach Section 307 BGB.
#### Damage caused by the tenant
Where the tenant damaged the rented property culpably, this is generally not an ordinary allocation of maintenance costs but a possible **claim for damages against the tenant who caused it**.
#### Splitting mixed invoices
Where a tradesman's invoice contains both recoverable maintenance services and repair, replacement or modernisation work that cannot be passed on, the whole invoice amount may not be transferred to the tenant.
If possible, ask the company carrying out the work to show separately:
* maintenance and running care,
* upkeep,
* repair or refurbishment,
* spare parts,
* new purchases,
* modernisation.
Only the share actually to be borne by the tenant under the commercial rental agreement should be entered in this category.
#### Important when the tenancy ends
The landlord's claims because of maintenance or repair measures assumed under the contract but not carried out can be subject to the short limitation period of Section 548 BGB after the commercial premises are returned. The Federal Court of Justice applies this short period to claims for performance and damages because of unfulfilled maintenance obligations too. Landlords should therefore inspect the premises promptly after they are returned, document their condition and pursue possible claims in good time.
#### Documents for the statement
Keep in particular:
* the commercial rental agreement and the relevant contractual clause,
* invoices and records of the work carried out,
* a description of the component or system concerned,
* evidence of the commercial unit concerned,
* photos or handover reports, where relevant,
* the split of mixed invoices,
* the calculation of an agreed cost ceiling,
* proof of payment.
Maintenance, tradesmen, repairs to technical systems and machinery (recoverable from tenant)
Use this category exclusively for the **costs of a small repair** which the tenant concerned has to bear on the basis of an effective small repairs clause in the rental agreement.
In principle the landlord is obliged to keep the rented property in a condition suitable for use in accordance with the contract during the tenancy. Repair and maintenance costs are also **not** operating costs and may therefore not be allocated through the ordinary annual operating cost statement. The tenant assuming the costs only comes into consideration on the basis of a separate and effective small repairs provision in the rental agreement, which is governed by Section 13 of the Immodio rental agreement.
### What can be entered here?
Only enter the actual costs of a smaller repair to an item here where that item
* is part of the apartment let,
* is subject to the tenant's frequent and direct access,
* has repair costs that lie entirely within the contractual maximum amount per repair,
* and where the contractual annual maximum has not yet been exhausted.
Depending on the rental agreement and the specific case, repairs to the following items, for example, can be recorded:
* taps and mixer taps,
* the controls of a toilet flush,
* light switches and sockets,
* door handles, door locks and closing devices,
* window handles and window catches,
* the controls of roller shutters or blinds,
* radiator thermostats and heating valves operated by the tenant,
* the controls of a cooker let with the apartment or of other cooking equipment let with it.
{% hint style="info" %}
The Federal Court of Justice allows small repairs clauses only for items that the tenant frequently operates themselves or whose wear they can influence through regular use. The underlying case law names as examples installation items for electricity, water and gas, heating and cooking equipment and window and door catches.
{% endhint %}
### What does "frequent and direct access" mean?
It is not sufficient that an item is merely located within the apartment. The tenant has to touch, operate or use the component concerned regularly.
A radiator thermostat, for example, is operated directly by the tenant. The pipes running inside the radiator or in the wall, on the other hand, are not subject to their direct access. The same applies to a light switch as opposed to the electrical wiring behind it.
With technical devices a distinction therefore has to be made between the accessible control element and the internal technical components. The control knob of a cooker let with the apartment can in principle come into consideration; the internal electronics, the heating element or the device control, on the other hand, may not in the individual case.
### The conditions for an effective small repairs clause
A standard form small repairs provision has to meet several conditions at the same time:
1. **A limitation as to the items covered**\
The clause may only cover items subject to the tenant's frequent direct access.
2. **A maximum amount per individual repair**\
The rental agreement has to state clearly up to what amount an individual small repair is borne by the tenant.
3. **A maximum burden within a particular period**\
The contract also has to limit the total burden that may arise for the tenant within a calendar year, for example.
4. **Only assumption of costs, no obligation to repair**\
A standard form rental agreement may in principle only impose the bearing of costs on the tenant. They may not be obliged to carry out the repair themselves or to engage a tradesman on their own.
{% hint style="info" %}
Where one of these conditions is missing, the whole small repairs clause can be invalid. Standard form clauses that are unclear or unreasonably disadvantageous do not withstand the review of content under Section 307 BGB.
{% endhint %}
### Exceeding the maximum amount per repair
Where the actual costs of a repair exceed the contractual maximum amount per repair, in principle a partial amount up to the agreed limit may not simply be charged to the tenant.
The Federal Court of Justice has held a standard form provision invalid under which a tenant was to contribute to larger repairs as well, merely up to the small repairs maximum amount. The specific repair itself has to remain a small repair and be below the agreed limit overall.
**Example:**
The rental agreement provides for a maximum amount per repair of 120 euros.
* Total repair costs: 95 euros → the tenant assuming the costs can be possible where all the other conditions are met.
* Total repair costs: 580 euros → 120 euros may not simply be applied as the tenant's share.
The complete specific repair invoice should be considered for the assessment.
### Monitoring the annual maximum
Even where several individual repairs are each below the maximum amount per repair, the annual total burden set out in the contract may **not** be exceeded.
For each tenancy, therefore, keep a comprehensible overview with:
* the date of the repair,
* the item concerned,
* the full invoice amount,
* the amount charged to the tenant,
* small repairs already charged within the year,
* the remaining annual maximum.
{% hint style="info" %}
For this you can use the comment function in the tenancy directly, for example, or record comments through the [comment function in the defect identified and to be repaired](/en/anleitung/immobilien/mangel/mangel-anlegen.md#working-with-defects).
{% endhint %}
### Assignment
For the assignment select **"Tenancy"** and then the specific tenancy concerned.
Small repair costs are not general property costs. They may therefore not be allocated to all residents of the building. The entry is to be assigned exclusively to the tenant whose rental agreement contains an effective small repairs clause and whose rented rooms or accessible facilities are affected.
Before making the assignment, check:
* whether the rental agreement contains a small repairs clause,
* whether the clause is effectively worded,
* whether the item concerned is covered by the clause,
* whether the maximum amount per repair is observed,
* whether the annual maximum has not yet been exceeded.
{% hint style="info" %}
The entries made here are listed separately under the "Very small repairs" category in the finished operating cost statement.
{% endhint %}
### When this category should not be used
The following repairs in particular do not belong in this category, repairs to:
* central heating and hot water systems,
* boilers, burners and heat pumps,
* pumps, motors or central control units,
* water, gas and heating pipes,
* electrical wiring under the plaster,
* fuse boxes and sub-distribution boards,
* central ventilation or air conditioning systems,
* building services in communal areas,
* roofs, facades or load-bearing components,
* communal doors and gate systems,
* technical facilities the tenant cannot operate directly.
The following also do not belong here:
* new purchases,
* modernisation,
* repairs above the maximum amount per repair,
* repairs after the annual maximum has been exceeded,
* costs arising from an invalid or missing small repairs clause.
The tenant contributing to new purchases or larger repairs cannot become permissible by limiting the amount to the small repairs maximum.
### Do not mix maintenance and repairs
Regular maintenance and remedying a specific defect are different services:
* **Maintenance** serves to preserve operational readiness.
* **A repair** restores a function that is already impaired or has failed.
Where an invoice contains both maintenance and repair services, have them shown separately if possible.
### Damage caused by the tenant
Where the tenant damaged an item culpably, this is not an ordinary small repair. An individual claim for damages then comes into consideration.
Normal changes and deterioration as a result of **use in accordance with the contract**, on the other hand, are not the tenant's responsibility. Damages generally require a breach of duty for which the tenant is responsible.
Examples of possible damages cases are:
* a door damaged by force,
* a switch destroyed by improper use,
* a window handle broken off as a result of gross misuse,
* a device damaged by a foreign object introduced by the tenant.
{% hint style="info" %}
Such claims should **not** be entered as a blanket small repair. Instead, document the damage, the cause, responsibility, the age of the item, the invoice and, where applicable, a deduction for wear already present, and check your right to an individual claim for damages.
{% endhint %}
### Documents for the statement
Keep in particular:
* the tradesman's invoice and proof of payment,
* a description of the defect,
* details of the item concerned,
* photos, where applicable,
* evidence of the full repair amount,
* the check of the maximum amount per repair,
* an overview of the annual burden so far,
* the calculation of the amount assigned to the tenant,
* correspondence about the defect report.
Internet (recoverable from tenant)
Use this category where the landlord provides internet access for one or more tenants and the costs are borne by the participating tenants on the basis of a **separate contractual agreement**.
#### An important legal note
Since **1 July 2024** the running monthly charges for broadband, cable or internet connections may in principle **no longer be allocated to all tenants through the operating cost statement**. The former ancillary cost privilege has ended. The tenant pays for their internet connection either directly to a provider of their own choice or to the landlord on the basis of their own contract. This generally requires a **separate and transparent agreement on the internet supply**.
#### What can be entered here?
Costs arising from an agreed internet supply for the tenants in particular can be recorded here, for example:
* the running fees of an internet provider,
* a tenant's contractually agreed share of a shared internet connection,
* agreed charges for internet access provided by the landlord,
* contractually agreed rental costs for routers or other access technology,
* other running charges that clearly belong to the agreed internet supply for the tenants.
#### The conditions for passing the costs on
The internet supply and the charge to be paid for it should be agreed clearly. The agreement should show at least:
* which internet service is provided,
* how high the charge is,
* which tenants take part in the supply,
* which contract term and notice period apply,
* whether additional costs arise, for a router for example.
{% hint style="info" %}
Where the landlord provides internet or other telecommunications services themselves in connection with the tenancy and charges the tenants for them, they generally have to observe the consumer protection provisions of the German Telecommunications Act. These include requirements on contract information, contract terms, termination, service failures and changing provider.
{% endhint %}
#### Assignment
For the assignment select **"Property"** where you have made an agreement on the internet supply with all tenants. Where the agreement exists with only one tenant, the entry should be assigned directly to the **"Unit"** or the **"Tenancy"** concerned.
A blanket allocation to all tenants of a property is not permissible simply because there is a shared internet connection in the building. The Federal Network Agency points out that a shared supply remains possible but requires corresponding individual agreements.
#### When this category should not be used
Do not use this category for:
* the landlord's private or business internet connection,
* internet costs for the office or the property management,
* the landlord's telephone or mobile contracts,
* internet costs of a vacant unit that cannot be effectively passed on to a tenant,
* repairs or the purchase of new routers, cables and other network technology, as far as these costs are not expressly part of a permissible separate service agreement.
{% hint style="info" %}
The landlord's own internet costs are recorded in the category **"Internet (not recoverable from tenant)"**.
{% endhint %}
#### The distinction from recoverable costs of the building infrastructure
Certain costs of a shared telecommunications infrastructure have to be distinguished from the internet fees themselves. Under Section 2 no. 15 BetrKV, the operating electricity of a communal aerial system or a private broadband distribution system and certain costs of a fibre optic system inside the building, for example, can still be recoverable under narrow conditions. The monthly fee for the internet service itself is, however, not automatically part of this.
For a newly built fibre optic infrastructure inside the building, a fibre optic provision charge can be allocated under the statutory conditions. It is in principle limited to **at most 60 euros per year and 540 euros in total per residential unit**. The tenant also has to be able to choose their telecommunications provider freely.
Cable fees, cable television (recoverable from tenant)
Since **1 July 2024** this category may only be used for narrowly limited running costs of the communal reception or distribution system.
Since that date the monthly charges for a cable TV or broadband connection may no longer be allocated to all tenants as ordinary operating costs. The former **ancillary cost privilege** has ended. Tenants now pay for a TV, internet or telephone connection either directly to a provider of their own choice or to the landlord on the basis of a separate individual contract.
### What can be entered here?
#### Operating an existing communal aerial system
With a communal aerial system the following running costs can in principle still be taken into account:
* the operating electricity of the aerial system,
* regular checks of operational readiness,
* regular adjustment of the system by a specialist,
* labour and travel costs, as far as they are directly attributable to that checking or adjustment.
This only applies to systems to which Section 2 no. 15 letter a BetrKV is still applicable:
> "*The costs of operating the communal aerial system, comprising the costs of the operating electricity and the costs of regularly checking its operational readiness including its adjustment by a specialist, and up to 30 June 2024 also the usage charge for an aerial system not belonging to the building and the fees arising under the Copyright Act for cable retransmission.*"
{% hint style="info" %}
For systems built on or after **1 December 2021**, this rule is **no longer applicable.**
{% endhint %}
#### Operating an existing private broadband distribution system
With a private distribution system present in the building that is connected to a broadband network, since 1 July 2024 in principle only the **operating electricity of the distribution system** is named as an operating cost item.
The monthly cable connection fees, basic TV charges and the costs of an external aerial system or of cable retransmission that used to be recoverable in addition are no longer covered.
{% hint style="info" %}
For systems built on or after **1 December 2021**, this rule is **no longer applicable.**
{% endhint %}
#### A fibre optic distribution system inside the building
With a distribution system inside the building that is connected entirely by fibre optic cable to a public network of very high capacity, the following can be entered under the statutory conditions:
* the operating electricity of the fibre optic system inside the building,
* a permissible fibre optic provision charge under Section 72 of the German Telecommunications Act.
{% hint style="warning" %}
This requires in particular that the tenant **can freely choose** their telecommunications provider over the connection.
{% endhint %}
The tenant also only has to bear the provision charge where the measure was implemented economically. With an elaborate measure with total costs of more than 300 euros per residential unit, the landlord has to obtain **three quotations and choose the most economical one**, as far as possible, before concluding the agreement.
### What may no longer be entered as operating costs since 1 July 2024
The following in particular do not belong in this category:
* monthly basic cable TV fees,
* charges for a basic TV connection,
* fees for programme packages or pay TV,
* internet and telephone fees,
* monthly broadband connection fees,
* the costs of a multi-user or collective contract for the telecommunications services themselves,
* usage charges for an aerial system not belonging to the building,
* copyright fees for cable retransmission,
* a tenant's activation fees,
* rental of receivers, routers or other terminal equipment.
The Operating Costs Ordinance expressly limited the allocation of the additional aerial, cable retransmission and basic broadband fees to the period up to **30 June 2024**.
{% hint style="warning" %}
An old rental agreement clause listing "cable fees", "broadband connection" or "communal aerial" as operating costs does **not** extend this statutory transitional period.
{% endhint %}
### A separate contract with the tenant
Landlords can still conclude a multi-user contract with a cable or telecommunications provider. The TV, internet or telephone charges arising from it may, however, no longer be allocated automatically to all tenants through the operating cost statement.
Passing them on only comes into consideration on the basis of a corresponding **individual contract with the respective tenant**. The tenant therefore has to be able to decide consciously in favour of the telecommunications service offered.
Where the landlord provides a TV, internet or telephone connection themselves and charges for it, they generally have to comply with the customer protection provisions of the German Telecommunications Act. These include, among other things:
* transparent details of the service and the price,
* a contract summary before the contract is concluded,
* information about the term, extension and termination,
* an initial term of at most 24 months,
* the offer of a contract variant with a term of at most twelve months,
* a notice period of at most one month after a tacit extension of the contract.
{% hint style="info" %}
Where the tenancy has already existed for at least 24 months, the consumer can accordingly end their use of a telecommunications service provided by the landlord on one month's notice.
{% endhint %}
### The fibre optic provision charge
The fibre optic provision charge is not an ordinary monthly fee for an internet or TV tariff. It serves to refinance, for a limited time, a fibre optic infrastructure built inside the building for the first time.
The charge is limited to:
* at most **60 euros per year and residential unit**,
* at most **540 euros in total per residential unit**,
* in principle a collection period of up to five years,
* with an elaborate measure, exceptionally up to nine years.
The operator has to ensure the operational readiness of the infrastructure and to give other telecommunications providers transparent and non-discriminatory access. The statutory rule applies to fibre optic infrastructures built by **31 December 2027** at the latest.
#### No double financing of the fibre optic roll-out
Where a fibre optic provision charge is billed through the operating costs, the landlord may not additionally claim the same roll-out costs through a modernisation rent increase.
A modernisation rent increase for the initial fibre optic connection only comes into consideration where the tenant can choose their provider freely and no fibre optic provision charge was or is allocated as operating costs.
### Assignment
For the assignment select **"Tenancy"** and then the tenancy for which the costs of the aerial, broadband distribution or fibre optic system may be allocated to the operating costs under an individual contract.
Assignment to the **property** is suitable exclusively for the **remaining recoverable infrastructure costs**, for example:
* the operating electricity of an existing system,
* the regular checking of a permissible communal aerial system,
* a permissible fibre optic provision charge.
### Split mixed invoices carefully
Invoices from cable network and telecommunications companies can contain different services, for example:
* basic TV supply,
* internet connections,
* the operating electricity of the building distribution system,
* maintenance or repairs,
* the fibre optic provision charge,
* router or device rental,
* connection and activation fees.
Such an invoice may not be entered in this category in full. Have the following shown separately if possible:
1. telecommunications and programme charges,
2. recoverable operating electricity,
3. permissible checking and adjustment work,
4. the fibre optic provision charge,
5. repairs and spare parts,
6. acquisition and installation costs,
7. terminal equipment and other additional services.
Only the infrastructure share actually recoverable under the current law may be allocated through the operating cost statement.
### Placing older case law in context
Under the former law the Federal Court of Justice partly allowed the allocation of broadband cable costs. Those decisions concerned settlement periods in which the Operating Costs Ordinance still recognised monthly basic cable fees as recoverable costs. No entitlement to continue allocating them as operating costs can be derived from them for periods from 1 July 2024 onwards.
Even before the end of the ancillary cost privilege, the Federal Court of Justice also held that a landlord who provides a cable TV connection for a charge can be treated as a provider under telecommunications law and has to allow tenants to end the service after a corresponding contract period. These provider duties are now expressly governed by Section 71 of the German Telecommunications Act.
### Settlement periods around 1 July 2024
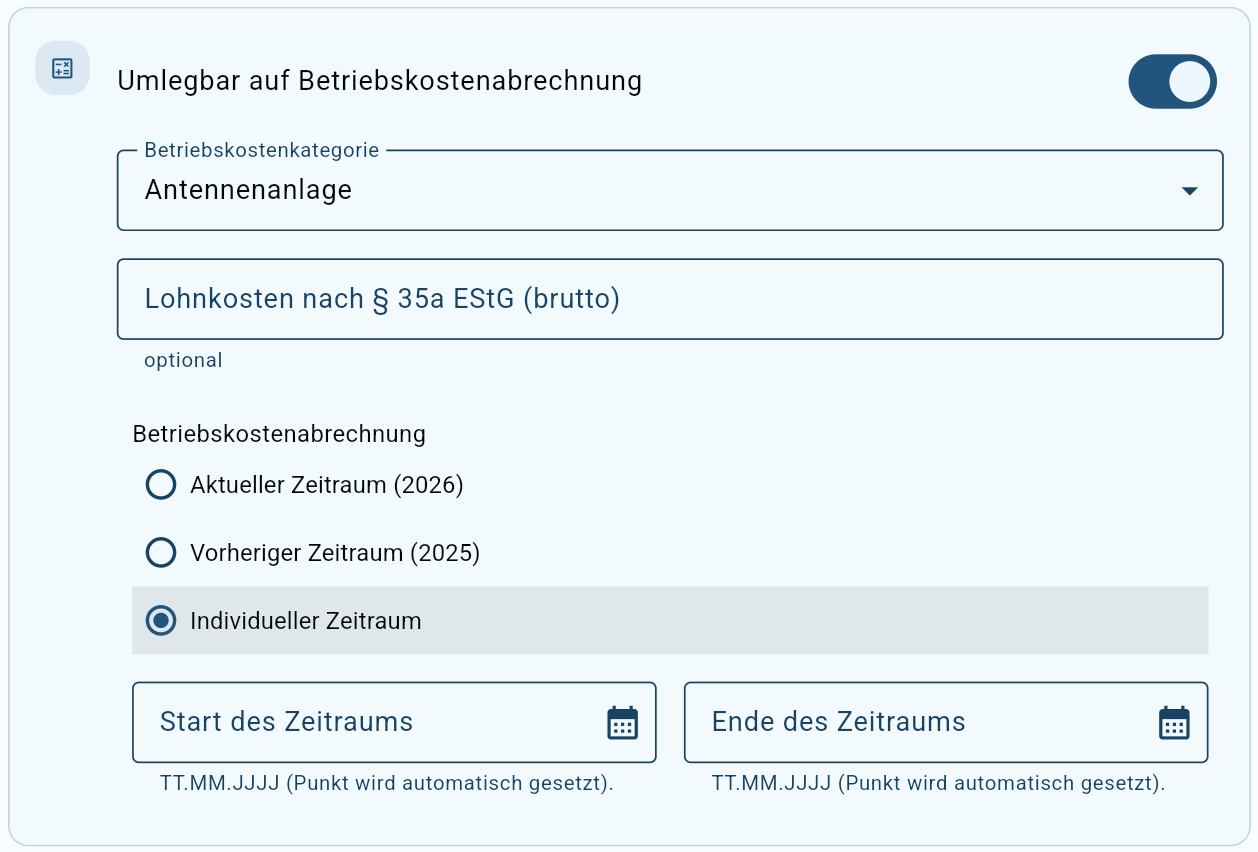
Where an invoice covers periods both before and after 1 July 2024, it has to be split pro rata by time.
With an annual invoice from 1 January to 31 December 2024, for example, the full basic TV price may not be applied as operating costs. Depending on the specific invoice and contractual position, at most the share attributable to the period up to 30 June 2024 can be taken into account under the old law. For the period from 1 July 2024 onwards, only the infrastructure costs still permitted by law may be applied.
In Immodio you can set an individual period for individual categories here:
### Documents for the statement
Keep in particular:
* the contract with the cable or network operator,
* the complete annual invoices,
* a breakdown of the individual services,
* details of the age and type of the building distribution system,
* invoices for the operating electricity,
* checking and adjustment records,
* documents on the fibre optic roll-out,
* evidence of the free choice of provider,
* the calculation of the fibre optic provision charge,
* the comparative quotations obtained, where applicable,
* the split by time for the year 2024,
* separate individual contracts with participating tenants.
Advance payments of operating costs have to be billed annually and in compliance with the requirement of economic efficiency. The tenant can ask to inspect the receipts underlying the statement.
The costs of cleaning gutters
Use this category for the **regular cleaning of gutters and, where applicable, the associated downpipes** where this work is needed regularly in order to remove leaves, moss, mud and other deposits and to keep the water draining properly.
The costs are then recovered from the tenants under **"other operating costs"**. They are neither ordinary drainage costs nor building cleaning, because gutters are not parts of the building used communally by the residents.
#### What can be entered here?
This can include in particular:
* the regular removal of leaves, moss, mud and other deposits,
* flushing out and cleaning the gutters,
* cleaning gutter inlets and leaf guards,
* the regular cleaning of connected downpipes, as far as it is part of the same cleaning service,
* the labour and travel costs directly necessary for the cleaning,
* the costs of an aerial platform or other necessary access equipment, as far as it is used directly for the regular cleaning,
* disposing of the material removed during the cleaning.
Only enter the share of an invoice that actually relates to the **running cleaning**. Where the invoice also contains checks, repairs or work on damaged components, those services have to be separated out.
### The requirement: agree it expressly in the rental agreement
Cleaning gutters is one of the **other operating costs under Section 2 no. 17 BetrKV**. In residential tenancies it is therefore generally not sufficient to refer in the rental agreement only in general terms to "operating costs" or to the Operating Costs Ordinance.
The type of cost should be named expressly in the rental agreement, which is the case in the Immodio rental agreement.
#### What does "regularly" mean?
The cleaning does not necessarily have to be carried out every year. Cleaning at intervals of several years can also be a running type of operating cost where it is necessary **recurrently and according to plan** because of local conditions.
That can be the case in particular with:
* trees in the immediate vicinity of the building,
* a regularly heavy accumulation of leaves or needles,
* gutters with particularly many corners or poor drainage,
* soiling that recurs according to experience.
A comprehensible cleaning cycle is helpful, for example annually, every two years or after each documented routine check. A one-off cleaning because of exceptional damage or because upkeep was neglected for years, on the other hand, is more difficult to classify as running operating costs.
### Assignment
For the assignment select **"Property"** and then the building concerned.
The costs are assigned to the entire property and allocated to the associated tenancies as part of the operating cost statement.
Where no other effective allocation key was agreed, allocation in residential tenancies is generally according to the share of the living space.
### When this category should not be used
The following in particular do not belong here:
* repairing and sealing leaking gutters,
* replacing damaged gutter parts,
* renewing downpipes,
* dealing with rust, frost or storm damage,
* repairing loose brackets,
* renewing gutter boxes and outlets,
* installing new leaf guards,
* the initial purchase or fitting of a gutter,
* work on the roof, the facade or the roof drainage,
* clearing blockages caused by a structural defect,
* emergency call-outs following water damage that has already occurred.
These are generally maintenance, repair or acquisition costs. Such costs are expressly **not** operating costs and may not be allocated to tenants under gutter cleaning.
### Splitting mixed invoices
Tradesmen's invoices frequently contain both cleaning and repairs. Typical examples are:
* "gutter cleaned and leaking seam sealed",
* "downpipe flushed out and damaged section of pipe replaced",
* "gutter cleaning and fitting of a leaf guard".
In such cases only the share clearly attributable to the regular cleaning may be entered in this category. If possible, ask the service provider to show separately:
* cleaning,
* checks,
* repairs,
* spare parts,
* new installations and
* access equipment.
### Where the landlord does the cleaning themselves
Where the landlord cleans the gutters themselves, their own materials and work can in principle be applied at the amount a **comparable service provider would have charged for an equivalent service**. Notional VAT may **not** be applied in that case.
For a comprehensible statement, the following should be documented:
* the date and scope of the cleaning,
* the gutters and downpipes concerned,
* the work carried out,
* the comparison price used,
* the basis of the comparison price,
* material and disposal costs, where applicable.
The costs applied for own work may not be higher than the market costs of a suitable specialist company.
### Economic efficiency and safety
With this type of cost too, the landlord has to observe the principle of economic efficiency. The cheapest quotation does not necessarily have to be chosen. The cleaning cycle, the scope of the service and the costs should, however, match the building's actual risk of soiling.
### Documents for the operating cost statement
Keep in particular:
* the rental agreement with the type of cost named expressly,
* the invoice and the description of the service,
* proof of payment,
* the cleaning date and the building concerned,
* documentation of the regular need for cleaning,
* the split of mixed invoices,
* the calculation where there are several buildings,
* the allocation key used,
* evidence of own work.
Tenants can ask to inspect the receipts underlying the operating cost statement.
The costs of precipitation water
Use this category for running charges levied for draining rain and precipitation water from the property into the public sewer system. This includes in particular water running off roof surfaces, courtyards, driveways, parking spaces and other paved or sealed areas.
In law, precipitation water charges are part of the **costs of drainage** and can in principle be recovered from the tenants as operating costs where the allocation of operating costs was effectively agreed in the rental agreement, which is of course the case in the **Immodio rental agreement**.
#### What can be entered here?
Enter here, for example:
* the precipitation water charge shown separately in the charge notice,
* rainwater or surface drainage charges,
* running charges for discharging precipitation water into the public sewer system,
* the running operating costs of a drainage pump, as far as it serves to drain precipitation water.
What matters is that these are **regularly recurring costs for draining the property**. In addition to the public drainage charges, Section 2 no. 3 BetrKV also covers the costs of operating corresponding non-public systems and drainage pumps.
#### How is the charge calculated?
The precipitation water charge is normally not based on the residents' water consumption or on how much it actually rained in the year concerned. What matters are the **local charging statute** and the **areas of the property** from which rainwater reaches the sewer system.
Depending on the municipality, the calculation is based, for example, on:
* the built-up and paved area connected,
* the sealed area of the property,
* particular run-off factors for different surfaces,
* the area of the property combined with an area run-off coefficient.
{% hint style="info" %}
The specific calculation differs from region to region. Hamburg calculates the charge on the basis of the sealed or built-over area connected, for example, while Munich combines the size of the plot with an area run-off coefficient.
{% endhint %}
#### When this category should not be used
Do not use this category for:
* fresh or drinking water costs,
* consumption-based foul water charges,
* general waste water charges, as far as they are calculated exclusively by water consumption,
* repairs to waste water or rainwater pipes,
* dealing with burst pipes or blockages resulting from a defect,
* renewing sewers, pipes or pumps,
* the purchase and construction of a cistern or infiltration system,
* structural unsealing or redesign measures.
{% hint style="info" %}
Foul water charges belong in the category **"All costs for drainage, waste water outflow, waste water and maintenance, no repairs"**. Where a charge notice contains both foul water and precipitation water, the amounts shown should be recorded separately in the respective appropriate categories.
{% endhint %}
#### Assignment
For the assignment select **"Property"** and then the property concerned.
The precipitation water charge arises for the property as a whole and is therefore first assigned to the entire property. It is then allocated to the associated tenancies as part of the operating cost statement.
Where no other effective allocation key was agreed, the costs in residential tenancies are generally allocated according to the share of the living space.
#### Check the charge notice carefully
Check in particular:
* whether the notice concerns the right property,
* which roof, yard, path and parking areas were taken into account,
* whether the sealed or connected area stated is correct,
* whether the partial areas actually drain into the sewer system,
* whether unsealing or structural changes have already been taken into account,
* whether foul water and precipitation water are shown separately,
* which settlement period the charge relates to.
Where the areas recorded do not match the actual position, the competent municipality or the drainage operator should be informed.
#### Options for reducing the charge
Depending on the local statute, the precipitation water charge can be reduced where rainwater no longer reaches the sewer system, or only partly does so. The following come into consideration, for example:
* unsealing paved areas,
* permeable paving,
* infiltration troughs or soakaways,
* green roofs,
* cisterns or rainwater storage,
Whether and by how much a reduction is possible always depends on the local rules. Structural measures should not be carried out solely because of a potential saving on charges. The local drainage statute, water law requirements, the nature of the ground and any permits needed have to be checked beforehand, among other things.
**Info:** For the statement, keep in particular the following documents:
* the charge or levy notice,
* the municipality's list of areas,
* details of the sealed and connected areas,
* documents on reductions or exemptions,
Tenants can ask to inspect the documents underlying the operating cost statement.
The costs of pest control
Use this category for **regularly recurring and preventive pest control measures** at the selected property.
The costs of pest control are expressly listed as operating costs in Section 2 no. 9 BetrKV. Only costs that **arise on a running basis** from the ownership or the intended use of the building are recoverable, however. One-off measures to deal with a specific infestation are generally **not** operating costs but costs of remedying a defect or of maintenance, and are therefore to be borne by the landlord.
### The legal classification
For the allocation, what matters is why the measure was carried out:
* **Preventive and recurring according to plan:** recoverable in principle.
* **Because of a specific acute infestation:** in principle costs for the landlord.
* **Demonstrably caused by a particular tenant:** possibly an individual claim for damages against that tenant, but no property-wide allocation of operating costs.
Most case law of the lower courts treats only regularly carried out, prophylactic measures as operating costs. The Hamburg Local Court, on the other hand, classified dealing with an existing acute infestation as remedying a defect. There is an older divergent individual decision of the Offenbach Local Court under which a one-off treatment could also be recoverable. For a legally reliable statement, however, this minority view should not be made the basis of general entry practice.
### What can be entered here?
Enter here in particular the costs of a **prevention programme provided for contractually or demonstrably carried out regularly**, for example:
* regular checks for rats, mice, cockroaches or other pests,
* setting up and checking bait stations according to plan,
* regularly replacing bait and traps,
* preventive treatment of communal areas at risk,
* monitoring in cellars, refuse rooms, attics, plant rooms or outdoor facilities,
* recurring checks of known entry or infestation areas,
* regular documentation of the checking and prevention measures,
* the labour, travel and material costs directly necessary,
* disposing of used bait and traps, as far as it is part of the running pest control.
The measure should be based on a comprehensible maintenance, inspection or control plan and should not have been commissioned only after specific damage occurred.
### What does "regularly" mean?
Pest control does not necessarily have to be carried out every year. Operating costs can also arise at intervals of several years where they recur according to plan and are part of a typical, foreseeable operating routine. The Federal Court of Justice has recognised in general terms that a cycle of several years can also be sufficient for "running" operating costs.
For pest control, the recurrence should follow from specific circumstances, for example:
* a permanently elevated risk of rats at the location,
* a refuse area regularly at risk,
* recurring checks in a food business,
* a documented risk of infestation in cellars or outdoor facilities.
Where several call-outs are necessary to deal with the same acute infestation, these form a single connected process of remedying a defect.
Examples:
* three treatments against bedbugs in the same apartment,
* repeatedly replenishing bait after an acute rat infestation,
* several inspection appointments to eliminate cockroaches completely,
* follow-up treatments after a mouse infestation identified for the first time.
{% hint style="info" %}
Repeating individual appointments does not automatically make the measure a regularly arising operating cost. What remains decisive is whether there is a **permanent preventive routine** or the **elimination of a specific infestation**.
{% endhint %}
### Distinguishing communal areas and individual apartments
A property-wide allocation comes into consideration above all with regular measures in areas used communally, for example:
* stairwells and entrance areas,
* cellars and attics,
* communal laundry rooms,
* refuse rooms and refuse areas,
* plant and storage rooms,
* courtyards and outdoor facilities.
Where only a single apartment is treated, the costs may not readily be allocated to all tenancies in the building.
### An acute pest infestation
The costs of dealing with an acute infestation on a **one-off** basis should generally not be recovered from the tenants in this category.
That applies in particular to:
* one-off rat or mouse control,
* dealing with a cockroach infestation,
* treating an apartment infested with bedbugs,
* dealing with food or clothes moths,
* removing a single wasps' nest,
* dealing with an ant infestation,
* dealing with wood pests,
* the one-off removal of pigeons, martens or other animals,
* disinfection and cleaning work after a specific infestation.
The landlord is in principle obliged to keep the rented property in a condition suitable for use in accordance with the contract. A considerable pest infestation can also be a defect in the rented property and lead to a reduction in rent.
### An infestation caused by the tenant
Where a particular tenant caused the pest infestation through a culpable breach of duty, there may be an individual claim for damages. This requires a breach of duty, damage caused by it and legal responsibility on the tenant's part.
Cases come into consideration, for example, where it is demonstrable that:
* food was stored permanently in the open or improperly,
* waste was collected in the apartment for a longer period despite requests,
* a considerable unhygienic state caused the infestation,
* pests were brought in with items introduced and the tenant then failed to report the infestation despite being aware of it,
* necessary control measures were culpably prevented.
A mere suspicion, a generally untidy impression or the fact that the infestation was first discovered in a particular apartment is not automatically sufficient to charge the costs. Structural causes, service shafts, cracks, damp, waste water pipes, refuse areas and spread from other units also have to be checked.
Such an amount should **not be allocated across the entire property as an operating cost entry** but assigned as a separate claim to the tenancy specifically responsible.
### Structural causes and consequential costs
Work to remedy structural causes of entry or infestation is not recoverable, for example:
* sealing cracks, joints and wall openings,
* repairing damaged waste water pipes,
* closing access points in the roof or facade,
* renewing defective cellar windows or doors,
* repairing refuse rooms,
* dealing with damp damage,
* replacing infested insulation or timber components,
* renewing pipes, shafts or cladding.
{% hint style="warning" %}
Such work is **repair or refurbishment cost** and remains non-recoverable even where it is carried out in connection with pest control.
{% endhint %}
### Assignment
For the assignment select **"Property"** and then the building for which the regularly recurring preventive measure was carried out.
Where no other effective allocation key was agreed, operating costs for residential space are generally allocated according to the share of the living space.
### Mixed-use buildings
Particular care is needed with buildings containing both apartments and commercial premises.
Where regular pest checks are carried out exclusively because of a:
* restaurant,
* bakery,
* butcher's,
* food shop,
* communal kitchen or
* other food-processing use
the additional costs arising from it should generally be assigned to the commercial unit concerned or to the group of users actually affected. Residential tenants may not be charged with costs caused exclusively by a particular commercial use.
### Splitting mixed contracts and invoices
Pest control contracts can contain different services:
* regular monitoring,
* preventive bait checks,
* acute control of an existing infestation,
* emergency call-outs,
* disinfection and special cleaning,
* sealing and repair work,
* replacing damaged parts of the building.
Such an invoice may not be entered in full as an operating cost item. Have the following shown separately if possible:
1. regularly recurring preventive services,
2. acute control of an infestation,
3. special and emergency call-outs,
4. cleaning and disinfection,
5. repairs and structural measures,
6. spare parts and other materials.
Only the share clearly attributable to the running, preventive pest checks belongs in this category.
### When this category should not be used
The following in particular do not belong here:
* the one-off control of an acute pest infestation,
* the treatment of only one apartment,
* several follow-up treatments of the same infestation,
* removing a single wasps' or bees' nest,
* repairing and sealing entry points,
* replacing infested or damaged components,
* special cleaning and disinfection after an infestation,
* the costs of expert reports on structural defects,
* the costs of damage caused by the tenant,
* control measures in the landlord's private rooms,
* measures for a vacant unit, as far as they do not serve the running operation of the entire property.
### Economic efficiency and documents
With pest control too, the landlord has to observe the requirement of economic efficiency. A running prevention contract should be objectively justified by the location, the use or the infestation risk of the building. Unnecessary or disproportionately frequent treatments may not be passed on to the tenants.
Keep in particular:
* the rental agreement and the operating cost agreement,
* the prevention or maintenance contract,
* the inspection and bait plan,
* call-out and infestation reports,
* invoices and proof of payment,
* the split between prevention and acute control,
* documentation of the regular cycle,
* the assignment of the areas of the building concerned,
* the calculation where there are several buildings or commercial units.
Refuse collection, refuse disposal, waste (recoverable from tenant)
Use this category for the **running costs of waste disposal for the selected property**. These include in particular municipal refuse charges, comparable services from private disposal companies and certain running costs for communal waste facilities and property-related refuse management.
The costs of refuse disposal are expressly listed as operating costs in Section 2 no. 8 BetrKV. Allocating them requires the rental agreement effectively to oblige the tenant to bear the operating costs, which is the case in the Immodio rental agreement.
### What can be entered here?
#### Public refuse charges
Enter here in particular the running costs shown in the charge notice from the municipal waste disposal body, for example:
* basic and container charges,
* charges for the regular collection of residual waste,
* charges for organic waste,
* charges for paper or other waste containers, as far as these are actually levied,
* charges for additional or special emptying,
* running charges for providing and emptying the waste containers,
* other running disposal charges according to the waste charge notice.
{% hint style="info" %}
Which containers, services and price components are charged depends on the local waste and charging statute. Take the actual amounts and the applicable charging period from the notice.
{% endhint %}
#### Private disposal services
In addition to the public charges, the costs of corresponding non-public measures can also be entered, for example:
* regular emptying by a private disposal company,
* the running disposal of communal waste containers,
* the scheduled collection of particular types of waste,
* property-related waste disposal services where there is no public collection,
* the necessary labour and transport costs of the running waste disposal.
The Operating Costs Ordinance expressly covers both public refuse charges and corresponding private measures.
### Refuse management, sorting and refuse locks
Recoverable refuse disposal costs can also include the running services of a refuse management company, for example:
* operating a chip-controlled refuse lock,
* recording the quantity of refuse deposited by individual households,
* calculating and allocating consumption-based refuse costs,
* the regular re-sorting of incorrectly deposited waste,
* removing refuse left beside the containers,
* checking the refuse areas,
* the running cleaning of the bin stands,
* measures to reduce incorrect filling.
The Federal Court of Justice generally classifies the operation of refuse quantity recording systems, the recurring removal of what are known as items left beside the bins and the re-sorting of the waste as costs of refuse disposal. Cleaning the bin stands can also be part of such refuse management.
A refuse management contract may nevertheless not be entered in full without being checked. Where it contains repairs, purchases, administrative services or other non-recoverable components, these have to be deducted.
### Refuse compactors and technical waste systems
The Operating Costs Ordinance expressly names the running costs of operating:
* refuse compactors,
* refuse chutes,
* refuse suction systems,
* refuse quantity recording systems.
These can include, for example, the operating electricity, running operation, monitoring, cleaning and the consumption-based calculation, as far as they serve the operation of the respective system directly.
The following, on the other hand, are not recoverable:
* purchasing and initially installing the system,
* repairs,
* replacing defective components,
* renewal or modernisation,
* replacing a system that is technically worn out.
{% hint style="info" %}
Only the **running operation**, not the purchase or restoration of the technical system, is part of the refuse disposal costs. Maintenance and repair costs are expressly not operating costs.
{% endhint %}
### Bulky waste and waste left without authorisation
Removing bulky waste or other waste left on communal areas of the rental property can also be recoverable in principle. According to the case law, that also applies where the refuse was left by individual tenants or unknown third parties without authorisation.
This requires the removal to take place as part of the running proper management of the property. The fact that such deposits occur only occasionally or at irregular intervals does not automatically deprive the costs of their running character.
This can include, for example:
* regularly necessary bulky waste collections,
* disposing of items recurrently left beside the refuse containers,
* removing furniture or household items left illegally,
* removing refuse from communal cellars, corridors or outdoor areas,
* the necessary transport and disposal charges.
#### Not every clearance is recoverable
The following, on the other hand, may not be entered as general refuse disposal costs:
* clearing an apartment taken over by the landlord or standing empty,
* clearing out after a particular tenancy has ended,
* removing items left behind by a known tenant,
* disposing of the landlord's items,
* the one-off clearance of a stock accumulated over years,
* disposal in connection with refurbishment or building work.
Such costs do not concern the ordinary running waste disposal of the entire property. Where the person responsible is known, a separate claim against that person may come into consideration. Where it is demonstrable that a particular tenant culpably caused additional disposal costs, those costs should not also be allocated to all residents.
That can be the case, for example, where a tenant:
* leaves a large quantity of bulky waste without permission,
* puts building rubble or hazardous waste into the household refuse containers,
* causes a chargeable special emptying through considerable incorrect filling,
* leaves items or waste behind after the contract ends.
{% hint style="info" %}
In this case there can be an individual claim for damages where a breach of duty for which the tenant is responsible and the damage caused by it can be proved.
{% endhint %}
### Waste separation and incorrect filling
The regular costs of re-sorting or checking waste separation can in principle be part of the refuse disposal costs. Re-sorting serves to prepare for disposal and can help avoid incorrect filling, additional charges or regulatory problems.
The following, on the other hand, do **not** belong in this category:
* fines,
* warning or late payment surcharges,
* contractual penalties,
* the costs of litigation,
* the landlord's general administrative effort,
* the costs of preparing information letters to the tenants.
Fines or late payment costs do **not** arise from the intended running use of the building and may **not** be allocated as operating costs.
### Putting out and returning the refuse containers
Depending on how it is arranged, the costs of regularly putting the bins out for collection and returning them can be part of the refuse disposal or of a caretaking service.
It is important that the same service is not applied twice:
* Where the bin service is already included in the caretaking contract, it may not be charged again as refuse disposal.
* Where a disposal or refuse management company charges separately for moving the containers, this can be assigned to the refuse disposal.
* Administrative services for organising the collection are not recoverable.
### Distinguishing commercial and private waste
In mixed-use properties it has to be checked particularly carefully whether commercial units cause considerably more waste or special waste.
That can concern restaurants, food shops, medical practices, workshops or retail businesses, for example. Where separate container, emptying or special disposal costs arise for them, these should if possible be assigned directly to the **tenancy** concerned.
Residential tenants should not be charged with special costs clearly caused by commercial use. Where consumption or causation is recorded, an allocation measure has to be used that reflects these differences.
### Assignment
For the assignment select **"Property"** and then the building for which the refuse charges or disposal costs were incurred.
Where no other effective allocation key was agreed in the residential rental agreement, refuse costs are generally allocated according to the share of the living space.
### Splitting mixed invoices
Where an invoice contains different services, it has to be checked before the entry is made and split if necessary.
Typical mixed invoices contain, for example:
1. running emptying and disposal costs,
2. refuse management and re-sorting,
3. repairing a refuse chute or compactor,
4. buying new containers or technical systems,
5. clearing an apartment,
6. disposing of construction waste,
7. administrative or processing fees.
Only the running, property-related refuse disposal services belong in this category. Repair, acquisition, administrative and building measures have to be deducted.
### When this category should not be used
The following in particular do not belong here:
* repairs to refuse chutes, compactors or suction systems,
* buying and initially installing waste systems,
* replacing or renewing refuse containers or technical facilities outside running disposal charges,
* disposing of construction, renovation or demolition material,
* clearing out individual apartments,
* disposing of the landlord's property,
* winding up an estate,
* removal after a forced eviction,
* removing hazardous building materials such as asbestos,
* commercial hazardous waste caused only by a particular business,
* fines, late payment surcharges and reminder costs,
* general administrative and legal advice costs,
* costs that are to be assigned directly to a known person responsible.
### The requirement of economic efficiency
The landlord has to observe the requirement of economic efficiency when choosing and organising the refuse disposal. That does not mean the cheapest solution always has to be chosen. The container size, the emptying cycle and additional services should, however, be in reasonable proportion to the actual need and to the benefit for the property.
Check regularly, therefore:
* whether the container sizes still match the actual need,
* whether containers are permanently only partly filled,
* whether unnecessary special emptying arises,
* whether incorrect filling causes additional costs,
* whether different services are billed twice,
* whether refuse management and re-sorting have a comprehensible benefit,
* whether commercial additional costs can be recorded separately.
The Federal Court of Justice recognises refuse management services as recoverable in principle. Even a relatively high share of these services in the total refuse costs does not in itself prove a breach of the requirement of economic efficiency.
### Documents for the operating cost statement
Keep in particular:
* refuse charge notices,
* contracts with private disposal companies,
* invoices and proof of payment,
* details of container sizes and emptying intervals,
* a list of the individual properties,
* contracts and records of services for the refuse management,
* evaluations from refuse quantity recording systems,
* invoices for bulky waste and items left beside the bins,
* documentation of particular cases of causation,
* the split of mixed invoices,
* the calculation of the individual tenants' shares.
Agreed advance payments of operating costs have to be billed annually. The statement has to present the total costs, the allocation key, the tenant's share and the advance payments made comprehensibly.
Chimney cleaning, chimney sweep, cleaning the flue system (recoverable from tenant)
Use this category for the **running and recurring costs of sweeping, cleaning and inspecting chimneys and flue systems**, as far as these costs are not already taken into account through the heating cost statement.
The costs of chimney cleaning are expressly listed as operating costs in Section 2 no. 12 BetrKV. Under it, the sweeping charges under the applicable scale of charges, or the corresponding running costs of chimney sweep work, are recoverable. This requires the rental agreement effectively to provide for the allocation of operating costs, which is taken into account accordingly in the Immodio rental agreement.
### What can be entered here?
The running costs of the following work in particular can be recorded here:
* the regular cleaning and sweeping of chimneys,
* cleaning flue pipes and connecting pieces,
* the prescribed inspection of flue systems,
* flue route inspections,
* checking necessary combustion air and extract air systems,
* carbon monoxide measurements as part of the flue route inspection,
* removing the combustion residues arising from the sweeping work,
* labour and travel costs, as far as they belong directly to the recoverable sweeping or inspection work,
* prescribed recurring measurements, provided they are not already entered as heating costs.
Under the German Sweeping and Inspection Ordinance, flue systems, the heating gas routes of fireplaces, smoking installations and necessary combustion air and extract air systems, among other things, are subject to sweeping or inspection. The specific frequency depends in particular on the type of fireplace, the fuel and the use. A blanket assumption that every system has to be swept once a year is therefore not correct.
### Floor heating systems and individual fireplaces
With floor heating systems and individual gas fireplaces, the regular cleaning, maintenance, safety inspection and the measurements under the German Federal Immission Control Act are likewise among the operating costs expressly named.
Where the invoice concerns only a single apartment or a fireplace used exclusively by one tenancy, the amount should if possible be assigned directly to the **unit** or the **tenancy** concerned.
That can concern, for example:
* gas floor heating,
* a wood-burning stove in a particular apartment,
* a tiled stove,
* a single gas boiler,
* a fireplace serving a commercial unit exclusively.
The costs of a chimney may not be allocated to tenants whose apartments are neither connected to that chimney nor able to use it from any conceivable point of view.
### Immission control and flue gas measurements
Recurring measurements on combustion systems prescribed by law can in principle be recoverable operating costs.
Depending on the type, age and technical design of the system, the First Federal Immission Control Ordinance provides for different monitoring intervals. Certain oil and gas combustion systems are measured every two or three calendar years, for example; with systems having self-calibrating continuous combustion control, a longer cycle can apply.
### The fireplace inspection and the fireplace notice
The fireplace inspection has to be distinguished from ordinary sweeping, cleaning and measurement work.
In it the authorised district chimney sweep checks the operational and fire safety of all relevant systems. The fireplace inspection may take place at the earliest three years and should take place at the latest five years after the previous fireplace inspection. A fireplace notice is then issued setting out the chimney sweep work to be carried out in future and the deadlines for it.
The Sweeping and Inspection Ordinance contains its own charge items for:
* the fireplace inspection,
* the fireplace notice,
* additional copies,
* certain official inspections.
### The one-off acceptance of a new or altered system
Costs arising from the initial construction or a substantial alteration of a combustion system do not belong in this category.
For new or substantially altered systems, the First Federal Immission Control Ordinance requires certain determinations and measurements before or shortly after they are put into operation. These services are directly connected with installing or altering the system and are not ordinary recurring chimney cleaning costs.
These include, for example:
* the acceptance of a newly built chimney,
* the acceptance of a newly installed boiler,
* an inspection after heating system conversion work,
* the initial measurement after a substantial alteration of the system,
* the acceptance of a newly installed wood-burning stove,
* an inspection after the initial installation of a flue pipe.
{% hint style="info" %}
Such costs are to be assigned to the acquisition, building or modernisation measure and **not** allocated to the tenants as running operating costs.
{% endhint %}
### Repeat and special inspections after defects are found
Where a measurement or inspection finds that statutory requirements are not met, the defect has to be remedied and a further inspection may then be needed.
The costs of such a repeat or special inspection should not automatically be recovered from the tenants as regular chimney sweep costs. They can be connected with a repair, a defective system or the improper fulfilment of an owner's obligations.
That concerns, for example:
* repeat measurements after an impermissible flue gas value,
* additional checks after a repair,
* inspections prompted by a specific suspicion,
* inspections after a chimney fire,
* follow-up checks of defects identified by the authorities,
* additional appointments because deadlines were missed.
{% hint style="warning" %}
Here a distinction has to be made in the individual case between a running inspection provided for by law and non-recoverable costs of remedying defects or of administration.
{% endhint %}
### Special sweeping work
Where combustion residues cannot be removed with ordinary sweeping tools, the Sweeping and Inspection Ordinance provides for special work such as burning out, knocking out or chemical cleaning under certain conditions.
Such costs can only come into consideration as running operating costs where the work:
* became necessary through the intended operation of the system,
* is a prescribed sweeping or cleaning service,
* is not based on a structural defect,
* and does not involve a repair or refurbishment.
Where the special work is instead the result of damage, of maintenance neglected for years, of a faulty system or of a structural defect, it should **not** be recovered from the tenants.
### Assignment
For the assignment select **"Property"** and then the building whose chimney or flue system was cleaned or inspected. Where costs concern only a particular tenancy, enter them against the **"Tenancy"** accordingly.
Where no other effective allocation key was agreed, ordinary operating costs are generally allocated according to the share of the living space.
### When this category should not be used
The following in particular do not belong here:
* repairing a damaged chimney,
* chimney refurbishment,
* inserting a new stainless steel liner,
* sealing leaking chimney flues,
* replacing defective flue pipes,
* renewing chimney heads or covers,
* dealing with damp or condensation damage,
* repairing a fireplace or heating system,
* the initial acceptance of a new system,
* acceptance after modernisation,
* the costs of remedying defects found,
* fines, reminder fees and late payment surcharges,
* the costs of substitute performance by the authorities,
* the landlord's general administrative fees,
* chimney sweep services already included twice in the heating costs.
Maintenance and repair costs to remedy damage from wear, ageing or other effects are expressly not operating costs.
### Documents for the operating cost statement
Keep in particular:
* chimney sweep invoices,
* the fireplace notice,
* certificates of sweeping and inspections,
* measurement records under the First Federal Immission Control Ordinance,
* evidence of the fireplaces concerned,
* the split where there are several buildings or chimney flues,
* evidence of the assignment to heating or operating costs,
* invoices for any repairs deducted,
* proof of payment.
Advance payments of operating costs have to be billed annually in compliance with the requirement of economic efficiency. The tenant can ask to inspect the underlying receipts.
Other levies and costs (recoverable from tenant)
Use this category only for **running, property-related costs** which may in principle be recovered from the tenants as operating costs but for which there is no more suitable entry category.
{% hint style="warning" %}
The category is **not a general catch-all account for any expenditure by the landlord**. Other operating costs have to meet the conditions of Section 1 BetrKV and may not already be covered by one of the specific types of operating cost in Section 2 nos. 1 to 16 BetrKV. Administrative costs, repairs, refurbishment and acquisition costs remain excluded.
{% endhint %}
### The conditions for allocation
An expense can be recorded in this category where it in principle meets **all** the following conditions:
* It arises from the ownership of the land or the intended use of the building, its systems or its facilities.
* It arises on a running basis or at recurring intervals.
* It serves the proper operation, checking, upkeep or safety of the building.
* It is not a repair, refurbishment, administration or acquisition.
* There is no more suitable category in Immodio for the expense.
* The specific type of cost may be recovered from the tenant under the rental agreement (it was recorded under the [**individual additional agreements**](/en/anleitung/mietverhaltnisse/mietverhaltnis-anlegen/zusatzvereinbarungen.md#individual-agreements), for example).
With **other operating costs under Section 2 no. 17 BetrKV**, the wording "other operating costs" alone is generally not sufficient in a residential rental agreement. The type of cost concerned has to be named as specifically as possible, for example as "the costs of the regular electrical inspection" or "the costs of cleaning the gutters".
### What can be entered here?
Depending on the building's features and the specific provisions of the rental agreement, the following items, for example, might come into consideration in certain circumstances:
#### Regular technical inspections
* recurring inspections of the building's electrical system,
* the regular inspection of fixed electrical systems in communal areas,
* recurring function and safety checks of technical facilities,
* the regular inspection of a lightning protection system,
* the regular inspection of a pressure boosting system,
* the regular inspection of emergency or safety lighting systems.
The Federal Court of Justice has held that regularly recurring costs for checking the operational safety of an electrical system can be other operating costs. The inspection may not, however, be confused with remedying defects found: the check can be recoverable, the subsequent repair generally not.
#### Fire protection and safety equipment
Depending on the rental agreement and the building, the running inspection and maintenance costs of the following facilities might come into consideration in certain circumstances:
* fire extinguishers,
* smoke and heat extraction systems,
* automatic fire dampers,
* sprinkler or extinguishing systems,
* fire detection and alarm equipment,
* escape route and emergency lighting,
* other safety equipment subject to regular inspection.
Only the running checks, maintenance, cleaning and function tests may be recorded. Buying, initially installing, replacing, repairing or renewing the equipment does **not** belong in this category.
#### The regular cleaning of particular parts of the building
The following might be recorded here in certain circumstances:
* the regular cleaning of gutter inlets and the associated downpipes,
* other recurring cleaning services on particular building facilities that cannot be assigned to an existing category.
#### Other particular building facilities
Depending on the property, recurring costs for monitoring, maintaining or testing the function of the following systems might also come into consideration in certain circumstances:
* ventilation or extract air systems, as far as they cannot be assigned to a heating cost item,
* automatic doors and gates,
* barrier and access systems,
* lifting units or special pump systems,
* backflow protection,
* facade access systems,
* communal access control systems,
* emergency power or safety power systems,
* other technical systems not named separately in Section 2 nos. 1 to 16 BetrKV.
{% hint style="info" %}
Whether these costs are actually recoverable always has to be checked against the specific content of the service and the rental agreement. As a rule, other costs can only be recorded where they are comparable to running operating costs.
{% endhint %}
### Other running public levies
The category can in certain circumstances also cover **running public charges relating to the land** where:
* they are levied regularly,
* they concern the property in question directly,
* they are recoverable in principle,
* and there is no more suitable category in Immodio.
A public levy should only be recorded under "Other levies and costs" where no more specific category exists. Take the exact description from the charge or levy notice.
One-off development, expansion, connection or frontager contributions are in principle **not** running operating costs and do **not** belong in this category.
### Assignment
For the assignment select, depending on the type of cost, either **"Property"** where the costs concern an entire building, or **"Tenancy"** or **"Unit"** accordingly where only individual tenancies or units are affected by these costs.
Alternatively, in the property's [**"Billing"**](/en/anleitung/immobilien/objekt/abrechnung-objekt.md#individual-allocation-keys) area you can create individual allocation keys.
### When this category should not be used
The following in particular do not belong here:
* property management and bookkeeping costs,
* the costs of preparing the general operating cost statement,
* tax advice and legal advice costs,
* postage, bank and account management fees,
* loan interest and financing costs,
* rent loss or vacancy costs,
* reminder, late payment and enforcement costs,
* fines and contractual penalties,
* repairs and remedying faults,
* spare parts,
* maintenance and refurbishment measures,
* initial purchases and installations,
* modernisation and renewals,
* device rentals that economically replace a purchase,
* one-off expert reports because of damage or a defect,
* the costs of remedying a defect found,
* one-off connection, expansion or development contributions,
* costs serving exclusively the landlord's personal or economic interest.
Administrative, maintenance and repair costs are expressly excluded from operating costs by law. Acquisition and financing costs cannot be shifted to the tenants through the catch-all category "other operating costs" either.
### Documents for the statement
Keep in particular:
* the rental agreement and the types of cost agreed,
* invoices and descriptions of services,
* maintenance and inspection contracts,
* inspection and maintenance records,
* charge and levy notices,
* the split of mixed invoices,
* the calculation where there are several buildings,
* proof of payment,
* the allocation key used.
Advance payments of operating costs have to be billed annually. The tenant can ask to inspect the underlying receipts; the landlord also has to observe the requirement of economic efficiency when choosing and commissioning services.
Other operating costs (recoverable from tenant)
Use this category for **other running operating costs of your rental property that can be recovered from the tenant and for which there is no more suitable specific category in Immodio**.
The category corresponds in particular to the **"other operating costs" under Section 2 no. 17 BetrKV**. These are running operating costs within the meaning of Section 1 BetrKV that are not already covered by the types of operating cost expressly named in Section 2 nos. 1 to 16 BetrKV.
**This category is a catch-all category**
Only use this category where:
* the costs arise **on a running basis** from the land, the building or its intended use,
* they are actually **operating costs** and not repair, administrative or acquisition costs,
* the specific type of cost may be recovered from the tenant,
* the allocation is effectively agreed in the rental agreement,
* and there is **no more specific category** in Immodio for this type of cost.
{% hint style="warning" %}
Where an exactly matching Immodio category already exists, use it and not the general category **"**[**Other operating costs (recoverable from tenant)**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10110010-sonstige-betriebskosten-umgelegt-auf-mieter.md)**"**.
{% endhint %}
#### **Which costs can be entered here, for example?**
Depending on the building and the rental agreement, regularly recurring costs can be recorded here, for example, for:
* the regular maintenance or inspection of particular technical facilities,
* recurring inspections of safety or fire protection equipment,
* the regular inspection of electrical systems,
* maintaining particular communal systems,
* or other running costs of the building not already covered by a more specific type of operating cost.
#### **Particularly important: the type of cost has to be named specifically in the rental agreement**
With **other operating costs under Section 2 no. 17 BetrKV** it is not sufficient for the rental agreement merely to refer in general terms to "**other operating costs**".
The specific type of cost that is later to be recovered from the tenant generally has to be **described with sufficient precision in the rental agreement**.
#### **Distinguishing running costs and one-off purchases**
Operating costs generally have to **arise on a running basis**. Not every expense for the building therefore becomes an operating cost.
**Example**
* A regular annual inspection of a technical facility of **€250** → where the other conditions are met, this can be an operating cost item.
* The initial purchase and installation of the technical facility of **€2,000** → is in principle not a running operating cost item.
#### **Repairs do not belong in this category**
A particularly important difference exists between:
* **maintenance or running inspections** and
* **repairs or refurbishment**.
Administrative, maintenance and repair costs are expressly **not** operating costs.
**Example: an inspection and a repair on the same invoice**
A specialist company invoices:
* the regular inspection: **€300**
* repairing a defect found: **€700**
Total: **€1,000**
The invoice may not be entered in full in **"**[**Other operating costs (recoverable from tenant)**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10110010-sonstige-betriebskosten-umgelegt-auf-mieter.md)**"**.
Where the conditions in the rental agreement are met, the **€300 for the regular inspection** can be taken into account as operating costs.
The **€700 for the repair**, on the other hand, may **not** be recovered from the tenant.
#### **The distinction from "Other levies and costs (recoverable from tenant)"**
Immodio also has the category:
**"Other levies and costs (recoverable from tenant)"**
The two categories should be distinguished by the actual character of the expense.
* **Another running operating service on the building or the land** → **"**[**Other operating costs (recoverable from tenant)**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10110010-sonstige-betriebskosten-umgelegt-auf-mieter.md)**"**
* **another recoverable levy or comparable cost** → **"Other levies and costs (recoverable from tenant)"**
#### **The distinction from "Other operating expenses"**
The category **"**[**Other operating expenses**](/en/anleitung/einnahmen-und-ausgaben/buchhaltung-erweiterung/10109600-sonstige-betriebliche-aufwendungen.md)**"** also has to be distinguished
It is intended for the owner's other expenses which are **not recovered from the tenant** and for which there is no more suitable category.
#### **Assignment in Immodio**
With this category the assignment is to the **property**. Select the rental property for which the other operating costs were actually incurred.
The costs can thereby be assigned to the property concerned and then to the associated tenancies for the operating cost statement.
The allocation key applicable to the type of cost or agreed contractually has to be observed here.
#### **The "Recoverable in the operating cost statement" switch**
This category is expressly intended for **recoverable operating costs**.
The **"Recoverable in the operating cost statement"** switch therefore has to be **enabled** where the type of cost concerned actually meets the conditions for allocation.
It has to be checked, however, whether:
* these are genuine running operating costs,
* no repair or administrative costs are included,
* and the specific other type of cost was effectively agreed with the tenant.
#### **What does not belong in this category**
The following in particular do not belong here:
* repairs,
* maintenance and refurbishment costs,
* administrative costs,
* buying new devices or systems,
* production costs,
* one-off investments,
* the owner's private costs,
* costs not effectively transferred to the tenant,
* types of cost for which a **more suitable specific category** already exists in Immodio.
With this catch-all category in particular, you should keep the **invoice, the description of the service and the rental agreement** together. That keeps it comprehensible later which specific type of cost was billed and on what basis it could be recovered from the tenant.
Other insurance (recoverable from tenant)
Use this category for the **running premiums of other property-related property and liability insurance** serving to protect the land, its technical facilities and the residents and visitors.
{% hint style="warning" %}
**Building property insurance** against fire, water from pipes, storm, hail or other natural hazards is not entered here but in the existing category **"Building insurance (recoverable from tenant)"**.
{% endhint %}
Alongside building insurance, Section 2 no. 13 BetrKV expressly names glass insurance and liability insurance for the building or land, the oil tank and the lift. The statutory list is not exhaustive. Under the case law, other property and liability insurance can in principle also be covered where it serves to protect the building, its residents or visitors.
### What can be entered here?
#### Glass insurance
Enter here the running premium of a **separate glass insurance policy**, as far as it covers glazing permanently attached to the building or used communally.
This can include, for example:
* window and door glazing,
* glass surfaces in entrance areas and stairwells,
* glass facades,
* skylights and roof lights,
* communal glass walls or partitions,
* the glazing of lift cars,
* permanently installed mirrors or other building glazing, as far as they are covered by the contract.
Glass insurance is expressly named as recoverable property insurance in Section 2 no. 13 BetrKV.
Glass insurance for the following does **not** belong in this category:
* the landlord's furniture,
* private household items,
* shop windows and fittings belonging exclusively to a particular commercial business, provided the premium can be assigned to that commercial tenant directly,
* glass items owned by individual tenants.
Where the glass insurance covers both communal building glazing and private or exclusively commercial risks, the premium has to be split appropriately.
#### Property owner's liability insurance
The running premium of **property owner's liability insurance** in particular belongs here, sometimes also called land, building or landlord liability insurance.
It protects the owner against liability claims that can arise from the condition or use of the land and its communal facilities, for example in connection with:
* paths that are not sufficiently secured,
* falling parts of the building,
* inadequate lighting of communal areas,
* hazards in the stairwell,
* trees and outdoor facilities,
* breaches of duties of inspection and traffic safety,
* communal play or recreation areas.
Property owner's liability insurance has to be distinguished from **residential building property insurance**. It does **not** compensate damage to the building itself but defends against liability claims directed at the owner or settles justified claims. The Federal Court of Justice has classified property owner's liability insurance as typical landlord insurance recoverable from tenants.
{% hint style="info" %}
The landlord's private liability insurance, on the other hand, may not be allocated simply because it may also include some risks relating to the land. With a combined policy, have the property-related share shown separately.
{% endhint %}
#### Oil tank or water pollution liability insurance
Enter here the running premiums of:
* oil tank liability insurance,
* water pollution liability insurance,
* liability insurance for above-ground or underground heating oil tanks.
This insurance covers liability risks where, for example, heating oil escapes from the tank or the associated pipes and damages the soil, groundwater or third party property. Liability insurance for an oil tank is expressly listed in Section 2 no. 13 BetrKV.
This requires the tank insured to serve the selected rental property or its heat supply. Where a policy insures several tanks or buildings, the share attributable to the respective property has to be split comprehensibly.
{% hint style="info" %}
Make sure the premium for the insurance item is not also entered as a component of the heating costs.
{% endhint %}
#### Lift liability insurance
The running premiums of liability insurance for a passenger or goods lift can be entered here.
Lift liability insurance is expressly named as recoverable liability insurance in Section 2 no. 13 BetrKV.
The following are not to be confused with the insurance premium:
* maintenance and safety inspection of the lift,
* the lift emergency call system,
* the operating electricity,
* cleaning the installation,
* repairs and spare parts.
#### Other particular property or liability insurance
Other insurance might be recoverable in an individual case in certain circumstances where it:
* is property or liability insurance,
* clearly relates to the selected property or a communal facility,
* serves to protect the building, its residents or visitors,
* arises on a running basis,
* is economically necessary and appropriate,
* and cannot be assigned to a more suitable category.
### Which insurance is not recoverable?
The following in particular do not belong in this category:
* landlords' legal expenses insurance,
* tenancy law legal expenses insurance,
* separate rent loss insurance,
* insurance against rent evasion or bad debts,
* deposit and guarantee insurance,
* credit, loan and residual debt insurance,
* the owner's private liability or contents insurance,
* individual tenants' contents, stock or business insurance,
* a property manager's financial loss liability insurance,
* professional indemnity, D\&O or cyber insurance,
* insurance against general vacancy or letting risks,
* litigation cost and debt collection insurance,
* construction and builder's liability insurance for individual construction projects,
* insurance for vehicles, machinery or other landlord property with no direct connection to the running operation of the building.
Such policies primarily protect the landlord's personal, financial, administrative or business risk and not the building, its residents or visitors. Under the case law, **separate rent loss insurance** in particular has to be distinguished from a rent loss module within building insurance and is **not** recoverable as an ordinary operating cost item.
### The contractual requirement
The costs of property and liability insurance are expressly listed in Section 2 no. 13 BetrKV. With residential space an effective agreement under which the tenant bears the operating costs in accordance with the Operating Costs Ordinance is therefore generally sufficient, which is taken into account accordingly in the Immodio rental agreement.
Where the rental agreement instead contains only an exhaustive list of individual types of cost, it has to be checked whether the property or liability insurance concerned is covered by it.
With newly concluded or unusual specialist insurance it also has to be checked:
* whether by its content it can actually be assigned to Section 2 no. 13 BetrKV,
* whether the rental agreement also covers operating costs arising newly later,
* whether taking it out is necessary and appropriate for the property.
### What may be entered from the insurance invoice?
In principle only enter the **running insurance premium** including the insurance tax on it, as far as the invoice concerns exclusively a recoverable policy.
The following do **not** belong here:
* excesses in the event of a claim,
* uninsured costs of damage,
* repair and restoration costs,
* the costs of remedying damage,
* damages payments,
* expert and lawyer costs,
* the administrative effort of settling a claim,
* reminder, default or returned direct debit costs,
* brokerage or advisory costs charged separately for administering the contract,
* contributions to an own damage or maintenance reserve.
{% hint style="info" %}
Excesses and specific costs of damage are not running insurance premiums. As far as they serve to remedy damage or defects, they are generally non-recoverable maintenance or repair costs.
{% endhint %}
### Assignment
For the assignment select **"Property"** and then the building or land to which the policy relates.
The costs are assigned to the property and allocated to the associated tenancies on the basis of their living spaces as part of the operating cost statement.
### The requirement of economic efficiency
The landlord may only charge the tenant with necessary and appropriate insurance costs. The requirement of economic efficiency does not necessarily demand the cheapest tariff, but it protects against unnecessary double insurance, obviously excessive premiums and insurance cover that is not appropriate for the specific property.
Check regularly, therefore:
* whether the property insured is described correctly,
* whether facilities that no longer exist are still insured,
* whether an oil tank or lift is still in operation,
* whether risks are insured more than once under different policies,
* whether private or commercial additional risks are included,
* whether the insurance cover matches the building's actual risk,
* whether increases in contributions are comprehensible,
* whether comparative quotations make sense where prices rise considerably.
### Documents for the operating cost statement
Keep in particular:
* the insurance policy,
* the contribution invoice,
* current contract addenda,
* a description of the risks insured,
* a list of the individual insurance modules,
* proof of payment,
* the calculation where there are several properties,
* evidence of non-recoverable components deducted,
* details of the commercial additional contribution, where applicable.
Advance payments of operating costs have to be billed annually and in compliance with the requirement of economic efficiency. The tenant can ask to inspect the underlying insurance and billing documents.
Street cleaning, sweeping service
Use this category for the **running costs of publicly or privately organised street and pavement cleaning** attributable to the selected property.
Section 2 no. 8 BetrKV expressly counts the following among these:
* charges for public street cleaning and
* the costs of corresponding non-public cleaning measures.
The costs can in principle be recovered from the tenants where the assumption of the operating costs was effectively agreed in the rental agreement, which is taken into account accordingly in the Immodio rental agreement.
### What can be entered here?
#### Public street cleaning charges
Enter here in particular the charges levied regularly by the municipality or the municipal street cleaning operator, for example:
* street cleaning charges,
* sweeping charges,
* regular charges for cleaning public carriageways,
* charges for cleaning public pavements, as far as this service is carried out by the municipality,
* the running components of a municipal street cleaning notice.
What matters is the actual charge notice. Which areas, cleaning classes, frequencies and services are included depends on the respective municipal street cleaning and charging statute.
#### Non-public street and pavement cleaning
Also enter here the costs of a private company or another person engaged where the cleaning is not carried out by the municipality.
This can include in particular:
* regularly sweeping the pavement in front of the property,
* cleaning access paths and private pavements,
* regularly sweeping the property's driveways,
* cleaning paved communal paths,
* removing leaves, sand, soil and ordinary street litter,
* removing paper, packaging and other usual soiling,
* the regular cleaning of kerbs and edges,
* the labour and travel costs directly necessary,
* the running costs of a sweeping service engaged under contract.
The costs of corresponding non-public measures are expressly covered by Section 2 no. 8 BetrKV. What matters is that the service serves the running cleaning of streets or paths and is not a repair, a one-off special cleaning or garden maintenance.
### Which areas belong in this category?
The following come into consideration above all:
* public pavements whose cleaning has been transferred to the property owner,
* private paths between the street and the house entrance,
* paved communal accesses,
* communal driveways,
* other traffic areas that have to be swept regularly.
The exact delimitation depends on the property and the scope of the service ordered.
### Winter services and street cleaning
In law, clearing snow and ice and gritting can also be part of the costs of non-public street cleaning. Immodio, however, already has its own category for this which you can use for winter services: **"Caretaker, winter services, snow clearing (recoverable from tenant)"**.
### Distinguishing bearing the costs and the duty to clean
An agreement in the rental agreement on the allocation of street cleaning or winter service costs initially only governs **who bears the costs**. It does not automatically transfer the actual duty to sweep, clear snow or grit to the tenant.
Where a tenant is to carry out the work themselves, a separate and sufficiently clear provision is necessary.
Where the landlord engages an external service provider, they should also check and document whether the service is carried out properly. Merely placing the order does not necessarily exclude the landlord's responsibility under the rental agreement.
### Assignment
For the assignment select **"Property"** and then the building for which the costs were incurred. The costs are then allocated to the associated tenancies by living space.
### Check public charges and private sweeping services separately
Both municipal street cleaning charges and the costs of a private sweeping service can arise. Both items may be allocated where they actually concern different services.
Example:
* The municipality cleans the public carriageway.
* A private service cleans the pavement and the access to the house.
### One-off special cleaning
Not every cleaning of paved areas is **running** street cleaning.
The following in principle do not belong in this category:
* cleaning after building or refurbishment work,
* removing building rubble,
* cleaning after fire or water damage,
* removing oil, paint or hazardous substances,
* the one-off removal of soiling accumulated over years,
* cleaning after an event held by the landlord,
* removing waste caused exclusively by the landlord,
* deep cleaning in connection with a new letting,
* the costs of remedying defects or damage.
{% hint style="info" %}
Operating costs have to arise on a running basis from the ownership or the intended use of the land. Maintenance and repair costs are expressly excluded.
{% endhint %}
### Soiling caused by a particular tenant
Where a particular tenant culpably causes exceptional soiling, these are not ordinary street cleaning costs to be allocated to all tenants.
That can concern, for example:
* spilled liquids,
* building rubble left behind,
* larger quantities of packaging material,
* soiling caused by a particular business,
* items left without permission.
{% hint style="info" %}
Where the person responsible is known and responsibility can be proved, a separate claim against that tenant may come into consideration. The costs should not be allocated across the entire property through this category.
{% endhint %}
### Repairs and purchases
The following in particular do not belong in this category:
* repairing damaged pavements,
* replacing or relaying paving slabs,
* removing trip hazards,
* renewing a driveway,
* repairing kerbs,
* buying sweeping machines,
* buying brooms, leaf blowers or cleaning equipment,
* building a new path,
* structural drainage measures,
* general administrative costs,
* fines and contractual penalties.
Buying durable working equipment and repairing or renewing paved areas are not running street cleaning costs. Smaller cleaning and working materials consumed on a running basis, on the other hand, can be part of the service where they are used directly for the regular cleaning and are not already charged elsewhere.
### Where the landlord does the sweeping themselves
Where the landlord carries out the recoverable street or pavement cleaning themselves, they may in principle apply the amount a suitable third party would have charged for an equivalent service. Merely notional VAT may **not** be applied.
For a comprehensible statement, the following should be documented:
* the areas cleaned,
* the type and scope of the work,
* the cleaning dates or the cleaning cycle,
* the time spent,
* the comparison price used,
* the basis of the comparison price,
* material costs actually incurred, where applicable.
{% hint style="info" %}
The price applied may not be higher than the market costs of an equivalent service from a third party.
{% endhint %}
### The requirement of economic efficiency
When organising the street cleaning too, the landlord has to ensure a reasonable ratio between cost and benefit.
Check in particular:
* whether the scope and frequency of the cleaning are necessary,
* whether areas are cleaned twice by the municipality and a private service,
* whether a caretaker already performs the same service,
* whether different cleaning intervals by season make sense,
* whether unnecessary additional services are included,
* whether comparative quotations make sense where prices rise considerably.
The cheapest quotation does not always have to be chosen. The costs should, however, be objectively comprehensible and appropriate for the property. The requirement of economic efficiency applies expressly to the annual operating cost statement.
### Documents for the operating cost statement
Keep in particular:
* municipal street cleaning and charge notices,
* the contract with the private sweeping service,
* a precise description of the service,
* invoices and proof of payment,
* a list of the areas cleaned,
* records of cleaning and call-outs,
* the delimitation from the caretaker and the winter service,
* the split where there are several buildings,
* evidence of own work,
Tenants can in principle ask to inspect the receipts underlying the operating cost statement.
Electricity (recovered from one tenant)
Use this category exclusively for **electricity costs that are clearly attributable to a particular tenancy and are passed on to that tenant on the basis of a separate contractual provision**.
It is intended in particular for cases in which the electricity supply contract with the energy supplier runs through the landlord but the electricity is consumed exclusively by a particular unit let or a particular tenancy.
{% hint style="warning" %}
Do **not** enter **communal electricity** or the electricity costs of communal technical systems here.
{% endhint %}
### The legal classification
The individual household electricity of an apartment is not an ordinary type of operating cost under the Operating Costs Ordinance. The Ordinance names only certain property-related electricity costs, such as the operating electricity of the heating, the lift electricity and the lighting of areas used communally. Private apartment electricity should therefore not be allocated through the building's general operating cost statement.
Where the electricity is procured by the landlord and passed on to a tenant by consumption, in law there can be a **supply of electricity to an end consumer**. Not only tenancy law but in principle also energy industry law then has to be observed. Which duties apply specifically depends, among other things, on the meter structure, the electricity supply model, the contractual arrangement and whether supply takes place through the public grid or exclusively within a customer installation.
{% hint style="warning" %}
The description "recovered from one tenant" should therefore not be confused with an ordinary allocation of operating costs; it is rather a **separate electricity statement addressed to a particular tenancy**.
{% endhint %}
### When can this category be used?
The category comes into consideration, for example, where:
* an apartment let has its own sub-meter but the main supply contract runs through the landlord,
* the landlord procures the electricity for a furnished or temporarily let unit and bills it by actual consumption,
* a granny flat within the customer installation is supplied through its own billable meter,
* the landlord lets individual rooms of an apartment with only one shared main connection and allocates the electricity costs to the individual tenancies on the basis of a clear agreement,
* a particular commercial unit is supplied through a sub-meter,
* there is a separate electricity supply contract between landlord and tenant.
It is always a condition that the amount concerned can be assigned comprehensibly to the selected tenancy.
### What can be entered here?
Where costs are passed on by consumption, the following in particular can be taken into account:
* the electricity consumption in kilowatt hours determined from the meter,
* a basic price attributable to the settlement period and the tenancy,
* running metering and metering point costs, as far as these are borne by the landlord and are contractually part of the electricity supply,
* the taxes, levies, grid charges and other price components contained in the supplier's invoice,
* where applicable, a contractually agreed share of a shared main connection,
* the consumption-based electricity costs of a facility used exclusively by the tenant concerned.
The basic price should be allocated pro rata by time or by another appropriate measure agreed contractually. The consumption price should be calculated on the basis of the kilowatt hours actually assigned to the tenancy.
### Who is the energy supplier's contractual partner?
#### An apartment with its own exclusively assigned main meter
Where the electricity of an apartment let is recorded by a meter assigned exclusively to that apartment, the contractual offer of the basic supplier contained in making the electricity available is addressed to the actual occupier of the apartment and not to the owner. By taking the electricity, an electricity supply contract can therefore arise with the tenant.
Where the landlord receives an invoice in such a case, they should not automatically pass the amount on to the tenant using this category. The following should first be checked:
* which user occupied the apartment during the supply period,
* to whom the supply point was registered,
* whether the energy supplier billed the right contractual partner,
* which meter readings were documented on moving in and moving out.
The invoice may have to be corrected with the supplier.
#### Individual rooms in a shared flat with only one shared meter
The position can be different with an apartment whose rooms are let under separate rental agreements but which has only one shared electricity meter. In 2025 the Federal Court of Justice held that in such circumstances the supplier's contractual offer can be addressed to the landlord. Without individual meters the consumption cannot be assigned to the respective room tenants, and a room tenant typically does not want to be liable for the total consumption of all the other occupants.
In such a letting model the rental agreement should clearly govern:
* whether electricity is included in the rent,
* whether a flat rate for electricity is charged,
* whether allocation is by person, room area or another measure,
* whether sub-meters are present,
* how changes of user during the settlement period are taken into account.
Without sub-meters, individual consumption cannot be asserted. The costs may then only be allocated by the measure effectively agreed and transparently presented.
### The contractual agreement
Where the tenant is to pay the landlord for electricity, the agreement should contain at least the following points:
* the exact consumption point,
* the start and end of the electricity supply,
* the electricity meter used,
* the unit price and basic price or the calculation method,
* the metering and other charges included,
* the reading and settlement period,
* the amount and calculation of the payments on account,
* the method of payment and when it falls due,
* provisions on price changes,
* the contract term and termination,
* the procedure on moving in and moving out,
* rights in the event of incorrect statements.
Where the landlord is treated as an electricity supplier under energy law, energy supply contracts have to be simple and understandable and contain, among other things, details of the consumption point, prices, contract duration, termination, method of payment, metering point operation, dispute resolution and changing supplier. For household customers outside the basic supply, the energy supply contract generally has to be in text form.
### Requirements for the electricity statement
Where the landlord is legally an electricity supplier, the invoice to the tenant has to be simple and understandable. The information provided for by law includes, among other things, the opening and closing meter readings, the consumption, the method of determining consumption, the applicable prices, contract and termination details and information about the metering point and grid operator.
A comprehensible statement should contain at least:
1. the tenancy and the consumption point,
2. the settlement period,
3. the meter number,
4. the opening and closing meter readings,
5. the difference in kilowatt hours,
6. the unit price per kilowatt hour,
7. the consumption costs,
8. the basic and metering price,
9. the allocation measure used, where applicable,
10. the total costs,
11. the payments on account made,
12. the credit balance or additional payment.
Energy consumption may be billed in settlement periods not exceeding one year. When the supply relationship ends, a final invoice has to be prepared. For energy suppliers, the Energy Industry Act generally provides for an invoicing period of six weeks after the end of the settlement period or of the supply relationship.
### Payments on account
Where monthly payments on account are agreed, these should be based on previous consumption or on the average consumption of comparable users. Where the household customer makes considerably lower consumption plausible, this is to be taken into account appropriately in the amount of the payments on account.
### Assignment
For the assignment select **"Tenancy"** and then the tenancy that actually consumed the electricity.
Direct assignment is important because these are not costs of the entire property. The amount may not be allocated to other tenants, vacant units or the entire building.
### Flat rates for electricity and all-inclusive rents
Where the electricity is settled by a fixed amount under the rental agreement, there is no passing on based on exact consumption. Such a flat rate may not be treated retrospectively like a metered electricity statement.
The contractual arrangement has to make clear:
* whether the flat rate is final,
* whether a later statement takes place,
* whether reasonable consumption is assumed,
* how exceptionally high consumption is dealt with,
* whether it is an independent electricity supply contract or an ancillary service of the tenancy.
### When this category should not be used
Do not enter the following here in particular:
* electricity for the stairwell, cellar and outdoor lighting,
* the operating electricity of the heating or hot water system,
* lift electricity,
* electricity for communal pumps or ventilation systems,
* electricity for the landlord's or property manager's office,
* the landlord's private electricity,
* the electricity of a vacant apartment with no assigned tenancy,
* another tenant's electricity costs,
* repairs to electrical systems,
* replacing or buying electricity meters,
* newly installing wiring or sub-distribution boards,
* the landlord's reminder and late payment costs,
* disconnection and reconnection costs caused by the landlord themselves,
* freely estimated or undocumented consumption quantities,
* photovoltaic tenant electricity without a proper tenant electricity contract.
For communal electricity use the category **"Communal electricity (recoverable from tenant)"**. The electricity of technical systems is assigned to the appropriate system category.
### Documents for the statement
Keep in particular:
* the contract with the external electricity supplier,
* the separate agreement with the tenant,
* the complete supplier invoices,
* meter and sub-meter numbers,
* evidence of calibration or conformity,
* move-in and move-out reports,
* photos of the meter readings,
* interim readings,
* the calculation of the basic price share,
* the split where there is a shared main meter,
* an overview of the payments on account,
* the electricity statement and proof of payment,
* documents on the customer installation or the tenant electricity model, where applicable.
Stairwell cleaning, cleaning the stairwell (recoverable from tenant)
Use this category for the **running costs of cleaning parts of the selected property used communally**.
The Operating Costs Ordinance expressly counts building cleaning among the recoverable operating costs. It covers the cleaning of parts of the building used jointly by the residents, in particular accesses, corridors, stairs, cellars, attics, laundry rooms and the car of a lift. Allocation requires an effective operating cost agreement in the rental agreement, which is taken into account accordingly in the Immodio rental agreement.
### What can be entered here?
Enter here in particular the regularly arising costs for:
* sweeping and mopping stairs and landings,
* cleaning house corridors and communal entrance areas,
* cleaning handrails and stair banisters,
* cleaning communal entrance doors,
* cleaning doormats and dirt trap zones,
* cleaning communal cellar and attic corridors,
* cleaning communal laundry rooms,
* cleaning the car of a lift,
* the regular cleaning of communal windows and glass surfaces,
* cleaning letterbox units, bell panels and other communal surfaces,
* the cleaning company's labour and travel costs that are directly necessary,
* cleaning materials consumed on a running basis, as far as they are part of the cleaning service.
{% hint style="info" %}
What matters is that the work concerns parts of the building used communally and is carried out on a running basis or recurrently according to plan.
{% endhint %}
### Which parts of the building are covered?
Typical areas used communally are:
* the house entrance and porch,
* the stairwell and intermediate landings,
* communal corridors,
* accesses to the cellar, attic or laundry room,
* communal cellar and attic rooms,
* the lift car,
* glass and door surfaces used communally.
It is not decisive whether every tenant uses every individual area daily. What matters first of all is whether the area belongs to the communal building installation or to the chosen billing unit.
Where the cleaning concerns only a spatially separate part of the building or a separate stairwell, on the other hand, in principle only the **tenancies** belonging to that area should be charged.
### Cleaning by the tenants or by a service provider
Before engaging a cleaning company, it should be checked what the rental agreement provides about cleaning.
#### 1. The landlord organises the cleaning
Where the rental agreement provides that the cleaning is organised by the landlord and billed through the operating costs, the running costs of a cleaning company can in principle be allocated to the tenants.
#### 2. The tenants are themselves obliged to clean
Where the rental agreement expressly obliges the tenants to clean the stairwell in turn, regular external cleaning costs should not be allocated to all tenants at the same time.
Where a cleaning company is to be used permanently in future, it has to be checked whether:
* the rental agreement already permits this change,
* a new agreement with the tenants is necessary,
* the external cleaning was engaged only because of a breach of duty by individual tenants,
* or the cleaning duty has to be effectively regulated anew.
### Assignment
For the assignment select **"Property"** and then the building whose communal areas were cleaned.
The costs are assigned to the property and allocated to the associated tenancies according to the share of the living space as part of the operating cost statement.
### Ground floor tenants and different use
With a property-wide allocation, ground floor tenants too are in principle included in the agreed allocation key. The statutory allocation by living space does not distinguish according to how often an individual resident actually uses the stairwell or particular floors.
The mere fact that an apartment is on the ground floor does not automatically lead to an exemption from all building cleaning costs.
### Mixed-use buildings
With buildings containing apartments and commercial units, it has to be checked whether the commercial use causes considerably higher cleaning costs.
That can be the case, for example, with:
* shops with heavy customer traffic,
* medical or therapy practices,
* restaurants,
* day nurseries,
* training or event rooms,
* businesses with frequent deliveries.
A prior deduction of the commercial share is particularly relevant where the commercial use leads to a significant additional burden on the residential tenants.
### Regular deep and special cleaning
Cleaning that is not carried out weekly can also be part of the running operating costs where it recurs according to plan.
The following come into consideration, for example:
* annual deep cleaning of the stairwell,
* the regular intensive cleaning of floor coverings,
* the regular cleaning of communal windows,
* the seasonal cleaning of entrance and dirt trap areas.
A one-off cleaning, on the other hand, is regularly not recoverable where it is carried out for a special reason not belonging to the ordinary operation of the building.
The following do not belong here, for example:
* final construction cleaning after a refurbishment,
* cleaning after painting or tradesmen's work,
* removing rubble and construction dust,
* cleaning after fire or water damage,
* cleaning an apartment that has been cleared,
* exceptional cleaning after an event held by the landlord,
* making good cleaning neglected for years,
* cleaning to prepare for a new letting.
{% hint style="info" %}
Such costs do not arise as ordinary running building cleaning or belong to the respective building, damage or administrative measure. Operating costs have to arise on a running basis; maintenance, repair and administrative costs are excluded.
{% endhint %}
### Exceptional soiling
Removing ordinary soiling that cannot be attributed to individual residents is part of the running building cleaning.
Where a particular tenant demonstrably causes exceptional soiling, on the other hand, for example through:
* spilled paint or oil,
* building rubble left behind,
* considerable soiling during a move,
* animal faeces,
* waste left improperly,
* damage and soiling after a private event,
the additional costs should not be allocated to all tenants across the board. A direct claim against the person responsible comes into consideration instead, provided their responsibility can be proved.
### Buying cleaning equipment
The following in particular should **not** be entered as running building cleaning:
* buying a cleaning machine,
* buying a vacuum cleaner,
* buying brooms, ladders or durable equipment,
* buying cleaning trolleys,
* replacing technical cleaning equipment.
Cleaning materials consumed on a running basis and low-value consumables, on the other hand, can be part of the cleaning service. Where durable equipment is used by the service provider, its business costs are regularly already included in the agreed cleaning price and may not additionally be allocated to the tenants as a separate purchase.
### The landlord's own work
Where the landlord or their own staff clean the stairwell, the materials and work can in principle be applied at the amount that would have arisen for an equivalent service from a third party company.
Notional VAT may not be applied where it did not actually arise.
**The following should be documented:**
* the areas cleaned,
* the type and scope of the work,
* the cleaning cycle,
* the period of the service,
* the comparison price used,
* the source of the comparison price,
* the material costs actually incurred.
The amount applied may not exceed the market costs of an equivalent service from a third party.
### The requirement of economic efficiency
The landlord has to observe the requirement of economic efficiency when choosing the cleaning service and the scope of the service. That does not mean the cheapest company necessarily has to be chosen. The price, scope of service, reliability and the building's requirements must, however, be in reasonable proportion.
Check in particular:
* whether the cleaning cycle matches the actual need,
* whether rarely used areas are cleaned unnecessarily often,
* whether services are included twice in the caretaking and cleaning contracts,
* whether exceptional additional services are necessary,
* whether price increases are comprehensible,
* whether comparative quotations make sense where costs rise considerably.
Building insurance (recoverable from tenant)
Use this category for the **running premiums of property and liability insurance** serving directly to protect the selected building, its systems and its residents and visitors.
The costs of such insurance are in principle recoverable operating costs. Passing them on to the tenants requires the allocation of operating costs to have been effectively agreed in the rental agreement, which is of course the case in the Immodio rental agreement. Section 2 no. 13 BetrKV expressly names building insurance against fire, storm, water and other natural hazards and glass, building liability, oil tank and lift liability insurance.
#### What can be entered here?
This can include in particular:
* residential building insurance,
* fire insurance for the building,
* insurance against water from pipes,
* storm and hail insurance,
* natural hazard insurance, for example against flooding, heavy rain, backflow, landslip or snow load, depending on the agreed scope of cover,
* building or building glass insurance,
* property owner's liability insurance,
* liability insurance for a heating oil or other oil tank,
* liability insurance for a passenger or goods lift,
* other property and liability insurance, as far as it specifically serves to protect the building, its systems, residents or visitors.
What is always decisive is that the insurance has a sufficient connection with the building and its intended use.
#### Assignment
For the assignment select **"Property"** and then the building to which the insurance premium relates.
Where a policy insures several buildings, split the invoice using the insurer's breakdown, the insured values or another appropriate and comprehensible measure.
#### Allocation to the tenants
Where no other effective allocation key was agreed, these costs are generally allocated in residential tenancies according to the share of the living space. Insurance premiums do not depend on an individual tenant's consumption.
#### Check package and collective insurance carefully
Insurance invoices frequently contain several modules. Only enter the components that actually concern recoverable building, property or liability insurance.
Where an invoice also contains **non-recoverable insurance**, those shares have to be deducted before the allocation. You can enter them in the category **"Insurance (not recoverable from tenant)"**.
That concerns, for example, policies in which further components are insured together with the building insurance:
* the landlord's private liability insurance,
* landlord's legal expenses insurance,
* contents insurance,
* financial loss liability insurance,
* insurance for an administrative office,
* other exclusively personal or economic risks of the landlord.
With a collective invoice, ask the insurer if possible for a breakdown of the individual insurance modules and the premiums attributable to them.
#### When this category should not be used
The following in particular do not belong here:
* the landlord's private liability insurance,
* contents insurance for their personal items,
* landlord's or land legal expenses insurance,
* insurance against general rent arrears,
* credit, loan or residual debt insurance,
* insurance for the property management or its staff,
* construction and builder's insurance for one-off construction projects,
* insurance for vehicles, photovoltaic or commercial installations with no direct connection to the communal use of the building,
* insurance protecting exclusively the owner's business or financial risk.
{% hint style="info" %}
Such costs are either not running operating costs or do not serve to protect the building, its residents and visitors. They can be entered in the category **"Insurance (not recoverable from tenant)"** for your own bookkeeping.
{% endhint %}
#### A special case: rent loss within the building insurance
Where a building insurance policy also covers rent loss for a limited time **as a result of insured damage to the building**, under the case law of the Federal Court of Justice that share of the premium does **not** have to be deducted. The whole premium can remain recoverable, because the insurance still serves to restore and secure the building after an insured event.
This has to be distinguished from independent rent loss or rent evasion insurance, which protects the landlord generally against rent payments not being made. That primarily protects their economic risk and should not be allocated to the tenants in this category.
#### Important: only enter insurance premiums
In principle only enter the **running insurance contributions including the running price components contained in the invoice** here.
The following in particular are not recoverable as insurance premiums:
* an excess paid in the event of a claim,
* costs of damage not covered by the insurer,
* repair and restoration costs,
* the costs of remedying damage,
* the landlord's expert or lawyer costs,
* damages payments,
* the administrative effort of processing an insurance claim.
Excesses and costs of damage are not regularly arising insurance premiums. Repair and restoration costs can also be maintenance or repair costs, which are expressly **not** operating costs.
#### Observe the requirement of economic efficiency
With insurance that is recoverable in principle too, the landlord has to observe the principle of economic efficiency. The insurance cover should match the building, its use and the risks present.
That does **not** mean the cheapest tariff necessarily has to be taken out. Unnecessary double insurance, obviously excessive cover or additional costs that cannot be objectively justified can, however, lead to objections from the tenants.
Check therefore:
* whether the building and the address are recorded correctly,
* whether the sum insured still matches the building,
* whether extensions, lifts, oil tanks or changes of use were reported,
* whether risks are insured twice,
* whether non-recoverable additional modules are included,
* whether cheaper comparable tariffs are available,
#### Documents for the statement
Keep in particular the following documents:
* the insurance policy,
* the contribution invoice,
* addenda to the insurance contract,
* a breakdown of the individual insurance modules,
* proof of payment,
* the calculation for policies covering several properties,
* evidence of non-recoverable shares deducted,
Tenants can ask to inspect the receipts underlying the operating cost statement. The documents should therefore show which property, which insurance period and which risks were insured.
Lift maintenance (recoverable from tenant)
Use this category for the **regularly arising maintenance, monitoring and inspection costs of a passenger or goods lift**. The Operating Costs Ordinance counts among these in particular the supervision, operation, monitoring and care of the installation, the regular checking of operational readiness and operational safety, necessary adjustments by a specialist and the cleaning of the lift installation.
Allocation requires the tenant to bear the lift or operating costs under the rental agreement, which is taken into account accordingly in Section 6 (2) of the Immodio rental agreement. Agreed advance payments have to be billed annually, observing the principle of economic efficiency.
#### What can be entered here?
The following in particular can be recorded here:
* regular maintenance and inspections,
* checking the drive, controls, doors and safety equipment,
* inspection and adjustment of the installation by specialist staff,
* lubrication, care and adjustment work,
* regular safety inspections by an approved monitoring body,
* main and intermediate inspections,
* cleaning the machine room, lift shaft and technical parts of the installation, as far as it is part of the lift maintenance,
* documented checks for obvious safety-relevant defects,
* labour and travel costs, as far as they are directly attributable to the recoverable maintenance or inspection.
{% hint style="info" %}
For lift installations subject to monitoring, the interval between main inspections may be at most two years. An intermediate inspection is also generally provided for in the middle of the inspection period.
{% endhint %}
#### Distinguishing statutory inspections and ordinary maintenance
The technical maintenance by the lift company and the statutory safety inspection by an approved monitoring body are different services. Both can, however, in principle be part of the lift's running operating costs.
Keep the inspection certificates. Among other things they have to show the installation, the inspection date, the scope of the inspection, the result and the date of the next inspection. A marking with the next inspection date and the inspecting body also has to be displayed in the lift car.
#### Assignment
For the assignment select **"Property"** and then the building in which the lift is located.
The costs are thereby assigned to the property concerned and allocated to the associated tenancies as part of the operating cost statement. Where no other effective allocation key was agreed, allocation for residential space is generally according to the share of the living space.
Where a maintenance contract concerns several lifts or buildings, the invoice has to be split appropriately, for example using:
* the service provider's breakdown,
* the number of lifts or
* the maintenance prices per installation.
#### Do ground floor tenants have to bear lift costs?
A ground floor tenant can also be made to contribute to the running lift costs on the basis of an agreement in the rental agreement. Under the case law of the Federal Court of Justice that applies in principle even where they do not need the lift and cannot reach either the cellar or the attic with it. An individual benefit from use is **not** strictly necessary for the allocation of costs under a standard form contract.
With multi-building complexes and separate parts of buildings, the specific structural and contractual assignment should be checked.
### Split full-service maintenance contracts precisely
With what are known as full maintenance or full-service contracts, the flat fee frequently covers not only the running maintenance but also repairs, spare parts and fault clearance.
Such an invoice may **not** be allocated to the tenants in full. With a maintenance contract too, a distinction has to be made between the remuneration attributable to recoverable operating services and that attributable to **non-recoverable repairs**.
Have the following shown separately if possible:
1. regular maintenance and inspection,
2. statutory safety inspections,
3. cleaning and care,
4. emergency call monitoring,
5. repair work,
6. spare parts and material,
7. replacing or renewing components.
Only the share comprehensibly attributable to the running maintenance and operating services belongs in this category.
#### What are not recoverable maintenance costs?
The following in particular do not belong in this category:
* repairs after a defect,
* fault clearance of a repair character,
* replacing defective controls, motors or door drives,
* replacing ropes, rollers, rails or car parts,
* spare parts and larger material costs,
* dealing with wear or ageing damage,
* renewing or modernising the installation,
* the initial installation of a lift,
* conversions for accessibility,
* remedying defects identified by the authorities, as far as this is a repair or renewal.
Maintenance and repair costs to remedy defects caused by wear, ageing or other effects are expressly not operating costs.
#### An example of a mixed invoice
Where an invoice contains the following services:
* annual maintenance: 1,200 euros,
* statutory inspection: 400 euros,
* replacing the door drive: 2,500 euros,
in principle only the maintenance and inspection costs of 1,600 euros in total (1,200 euros + 400 euros) can be taken into account in this category. Replacing the door drive is to be entered separately as a repair or maintenance expenditure in the category **"Maintenance, maintenance expenditure, tradesmen, repairs (subject to capitalisation, production costs close to acquisition)"**.
### The emergency call system and standby service
An emergency call standby service set up specifically for the passenger lift can be part of the recoverable operating costs. This requires it actually to serve the lift and to ensure a response to emergency calls and the necessary measures to free people.
A general emergency service flat rate for any faults in the building, for the heating, water, doors and electricity for example, is not covered. Such general availability does **not** become a lift operating cost item merely because it also includes lift faults.
### Economic efficiency and documentation
The landlord has to observe the requirement of economic efficiency in the statement. A comprehensive maintenance contract can make sense for reasons of safety and reliability, but non-recoverable repair and renewal components still have to be deducted.
Keep in particular:
* the maintenance contract and the description of the service,
* annual and individual invoices,
* inspection certificates,
* maintenance and inspection records,
* the split of full maintenance charges,
* evidence of repair shares deducted,
* a list where there are several lifts or properties.
Maintenance of your rental properties (recoverable from tenant)
Use this category for the **regularly arising maintenance, inspection, monitoring, cleaning and care costs of technical systems or communal facilities**, provided the costs are in principle recoverable as operating costs and there is no more suitable entry category in Immodio.
The category may not be used as a general catch-all account for all maintenance and tradesmen's invoices. Only costs that **arise on a running basis** from the ownership or the intended use of the building are operating costs. Administrative, maintenance and repair costs are expressly excluded.
### The legal classification
The term **"maintenance"** alone does not yet determine whether an invoice may be recovered from the tenants. What matters is which specific service was provided:
* A regular inspection, cleaning, adjustment or function check can be part of the operating costs.
* Remedying a defect that already exists is generally a repair or refurbishment and therefore **not** recoverable.
* The initial purchase, installation or fundamental renewal of a system is likewise **not** part of the operating costs.
The Federal Court of Justice has expressly held that recurring checks of the functionality and operational safety of a technical system can be operating costs. In the case decided, an inspection of an electrical system carried out on a four-year cycle was recoverable. What was decisive was that the inspection did not serve to remedy a defect that already existed.
### What can be entered here?
This general category comes into consideration in particular for maintenance and inspection costs that **cannot** be assigned to a category already existing in Immodio.
#### The regular inspection of the electrical system
The following might be entered here in certain circumstances, for example:
* the recurring safety inspection of the communal electrical system,
* checking main distribution boards and communal sub-distribution boards,
* checking fixed electrical systems in communal areas,
* measurements and function checks,
* preparing the inspection record,
* the necessary travel and labour costs of the inspection.
The Federal Court of Justice has expressly recognised the regularly recurring inspection of the operational safety of an electrical system as other operating costs that are recoverable in principle. An inspection cycle of several years can also be sufficient.
#### Maintaining fire protection and safety equipment
Depending on the building's features and the provisions of the rental agreement, the following, for example, might come into consideration in certain circumstances:
* maintaining and inspecting fire extinguishers,
* maintaining smoke and heat extraction systems,
* checking fire dampers,
* maintaining sprinkler or extinguishing systems,
* checking hold-open devices on fire doors,
* maintaining escape route and emergency lighting,
* checking other communal fire and safety equipment.
Only enter the regularly arising inspection, cleaning, adjustment and function check. Purchase, initial installation, repair, replacement and renewal are in principle **not** to be applied as operating costs.
Where a separate category already exists, such as **"Maintenance of smoke alarms, no repair or purchase (recoverable from tenant)"**, that category takes precedence.
#### Lightning protection systems
The following might come into consideration in certain circumstances:
* the recurring inspection of the external lightning protection system,
* function testing of the internal lightning and surge protection,
* visual and measurement checks,
* documenting the inspection results.
The initial construction of the system, renewing conductors, replacing damaged components and remedying defects found are not recoverable.
#### Automatic doors, gates and access systems
Depending on the rental agreement, the following might be entered in certain circumstances, for example:
* the regular function and safety inspection of automatic doors,
* maintaining communal garage or yard gates,
* checking barrier systems,
* cleaning, lubricating and adjusting moving parts,
* checking light barriers and safety equipment.
**Repairs** to the motor, controls, gate leaf, rails or other defective components do **not** belong in this category.
#### Ventilation and extract air systems
The following might come into consideration in certain circumstances:
* the regular cleaning and function testing of a communal ventilation system,
* checking and adjusting the system,
* cleaning accessible operational components,
* the regular inspection of fans and controls,
* documenting the maintenance.
Where the system is part of the central heating or hot water supply, its costs may have to be assigned to the **"heating or hot water costs"**. Repairs, replacing motors and fans and renewing ducts or controls are not to be allocated through this general maintenance category.
#### Other technical systems
Depending on the building, the contractual arrangement and the specialist categories available, recurring maintenance and inspection costs for the following facilities might also come into consideration in certain circumstances:
* communal lifting or pump systems,
* backflow protection,
* pressure boosting systems,
* facade access systems,
* communal emergency power or safety power systems,
* technical access systems,
* other communal facilities subject to regular inspection.
{% hint style="info" %}
With water, drainage, heating, hot water or lift systems, however, the types of operating cost expressly provided for them in Immodio are to be used first.
{% endhint %}
### Specific categories take precedence
Do not use this general category where Immodio already offers a more suitable type of cost, for example for:
* "Heating and hot water (recoverable from tenant)",
* Lift maintenance (recoverable from tenant)
* Maintenance of smoke alarms, no repair or purchase (recoverable from tenant),
* The costs of cleaning gutters,
* Caretaker, winter services, snow clearing (recoverable from tenant),
### Naming the operating costs in the rental agreement
For costs already expressly falling under Section 2 nos. 1 to 16 BetrKV, an effective agreement on the allocation of operating costs in accordance with the Operating Costs Ordinance is generally sufficient in a residential rental agreement.
The position is different with particular maintenance and inspection costs that only fall under **"other operating costs" under Section 2 no. 17 BetrKV**. These have to be **named specifically** in the rental agreement. A blanket reference to "other operating costs", "general maintenance costs" or "maintenance of the rental property" is generally not sufficient.
#### Newly arising maintenance costs
Where a new technical facility is installed during an ongoing tenancy, its later maintenance costs cannot be recovered from the tenant simply because they will arise regularly in future.
It has to be checked whether:
* the costs are operating costs by their nature at all,
* they are covered by a type of operating cost already agreed,
* there is an effective provision on operating costs newly arising in future,
* and whether a prior declaration to the tenant is necessary.
### What does "running" mean?
Maintenance does **not** have to take place every year. It is sufficient that it recurs according to plan and at comprehensible intervals.
The Federal Court of Justice regarded a four-year cycle for the inspection of an electrical system as sufficient.
Document therefore:
* the maintenance cycle provided for,
* the maintenance dates so far,
* the basis of the inspection,
* the building or system concerned.
### Distinguishing maintenance, inspection and repair
**Recoverable maintenance components might be, in certain circumstances**
* checking functionality,
* checking operational safety,
* visual checks,
* measurements,
* cleaning,
* lubrication,
* adjustment and calibration,
* documenting the inspection,
* the labour and travel costs directly necessary.
**Non-recoverable repair components are in particular**
* fault finding because of a specific malfunction,
* remedying a defect,
* replacing damaged or worn components,
* restoring a function that has failed,
* remedying damage caused by age or the weather,
* replacing a system that is technically worn out.
Maintenance and repair costs serve to remedy defects caused by wear, ageing or the weather. Under Section 1 (2) BetrKV they are expressly not operating costs.
#### Regularly replacing small parts
With prescribed regular replacement work, the distinction can be more difficult. The Federal Court of Justice left open whether the regular replacement of small electronic components of an existing system prescribed by a technical standard can exceptionally be treated as running maintenance expenditure.
Such material costs should therefore not be allocated automatically. Check in particular:
* whether the replacement is prescribed on a regular cycle independently of a defect,
* whether it really is only a low-value consumable or maintenance part,
* whether the costs are covered by the rental agreement,
* whether the invoice shows maintenance and spare parts separately.
With larger components or a replacement because of wear, non-recoverable refurbishment is regularly to be assumed.
### General emergency service flat rates
General standby availability for reports of burst water pipes, power failures, heating failures or other building faults is **not** recoverable maintenance. The Federal Court of Justice classifies receiving such fault reports and organising subsequent repairs as administrative costs.
This has to be distinguished from emergency call services necessary by law or technically for a particular installation, for example the lift emergency call standby. That is to be recorded in the specific category for the installation concerned.
### Assignment
For the assignment select **"Property"** and then the building whose technical system was maintained or inspected.
The costs are assigned to the property and allocated to the associated tenancies as part of the operating cost statement.
### Special features with commercial tenancies
With commercial premises the parties can agree a more extensive assumption of costs than with residential space. The agreement must, however, be specific or at least ascertainable.
Very broadly worded standard form clauses are problematic in commercial tenancy law too. The Federal Court of Justice objected to a clause imposing on a commercial tenant, without an appropriate limit, the maintenance and upkeep of all technical facilities and communal installations. Such a provision can burden the tenant with incalculable maintenance costs.
With commercial premises it therefore also has to be checked:
* which systems are specifically covered,
* whether only maintenance or also repair was transferred,
* whether communal installations are affected,
* whether a limit on the amount is necessary,
* whether it is an individually negotiated agreement or a standard form clause.
### The landlord's own work
Where the landlord carries out a recoverable maintenance or inspection service themselves, in principle the amount a suitable third party would charge for an equivalent service may be applied. Merely notional VAT may **not** be charged.
The following should be documented:
* the date and duration of the service,
* the specific system inspected or maintained,
* the scope of the work,
* the qualification or professional suitability,
* the comparison price used,
* the source of the comparison price,
* material costs, where applicable.
{% hint style="warning" %}
Inspections prescribed by law that are reserved to an approved or specially qualified specialist body generally **cannot** be replaced by own work.
{% endhint %}
### Economic efficiency and documents
Advance payments of operating costs have to be billed annually. The landlord has to observe the requirement of economic efficiency and, on request, allow the tenant to inspect the underlying receipts.
Keep in particular:
* the maintenance or inspection contract,
* a precise description of the service,
* the invoice and proof of payment,
* the maintenance and inspection record,
* the designation of the system concerned,
* evidence of the maintenance cycle,
* the split between maintenance and repair,
* the split where there are several buildings,
* the rental agreement with the type of cost agreed.
Maintenance of smoke alarms, no repair or purchase (recoverable from tenant)
Use this category exclusively for the **regularly arising costs of function testing and maintaining smoke alarms already installed**. These include services that check and ensure that the devices are properly fitted, undamaged and operational.
The Federal Court of Justice classifies the regular testing and ensuring of the operational readiness of smoke alarms as **other operating costs under Section 2 no. 17 BetrKV**. Such maintenance costs can therefore in principle be recovered from residential tenants, unlike the costs of buying, renting or replacing the devices.
{% hint style="warning" %}
The Federal Court of Justice has expressly held that the **rental costs of smoke alarms are not recoverable operating costs**. Economically, renting the devices takes the place of the purchase, which is likewise not recoverable, and may **not** become an operating cost simply because the landlord rents the devices instead of buying them. For renting or buying smoke alarms you can use the category **"Rental for smoke alarms"** for your own bookkeeping.
{% endhint %}
#### What can be entered here?
The costs of the following in particular can be entered:
* the regular visual and function testing of the smoke alarms,
* checking operational readiness and the alarm function,
* checking the intended mounting position,
* checking that the smoke inlet openings are clear and not painted over or covered,
* checking for identifiable damage or soiling,
* cleaning the alarm, as far as it is part of the regular maintenance,
* documenting the inspection carried out,
* the maintenance company's travel and labour costs,
* the costs of a permissible technical or radio-based inspection, as far as it actually checks operational readiness,
* running service costs, as far as they are clearly attributable to the maintenance and not to providing or renting the devices.
{% hint style="info" %}
The currently published **DIN 14676-1:2025-05** contains minimum requirements for the planning, installation, operation and upkeep of smoke alarms. The manufacturer's specifications and the applicable state law requirements should also be taken into account for the maintenance.
{% endhint %}
### The condition for recovering the costs from tenants
As maintaining smoke alarms is not expressly listed in numbers 1 to 16 of the Operating Costs Ordinance, these are **other operating costs**. The type of cost should therefore be agreed with sufficient specificity in the rental agreement, which is the case in the Immodio rental agreement.
### Who is responsible for the maintenance?
Responsibility under public law for ensuring operational readiness is governed differently in the building regulations of the federal states. Depending on the state, it can be assigned to the owner or the direct possessor (generally the tenant).
A state law provision under which the tenant is responsible for operational readiness does not, however, automatically prevent the landlord from organising uniform maintenance. This is often sensible for landlords, because it lets inspection intervals, the stock of devices and defects found be documented centrally. The specific responsibility should nevertheless be checked against the building regulations of the state concerned.
### Assignment
For the assignment select **"Property"** and then the building in which the smoke alarms maintained are located.
The costs are assigned to the property and allocated to the associated tenancies by living space as part of the operating cost statement. Alternatively, in the property's [**"Billing"**](/en/anleitung/immobilien/objekt/abrechnung-objekt.md#individual-allocation-keys) area you can create individual allocation keys, for the number of smoke alarms for example.
### Purchase and device rental are not recoverable
The following do not belong in this category:
* the initial purchase of the smoke alarms,
* the costs of the initial equipment,
* renting or leasing the smoke alarms,
* provision charges for the devices,
* the complete replacement of old or defective smoke alarms,
* buying additional devices,
* the installation costs of the initial fitting.
{% hint style="warning" %}
The Federal Court of Justice has expressly held that the **rental costs of smoke alarms are not recoverable operating costs**. Economically, renting the devices takes the place of the purchase, which is likewise not recoverable, and may **not** become an operating cost simply because the landlord rents the devices instead of buying them. For renting or buying smoke alarms, you can use the category **"Rental for smoke alarms"** for your own bookkeeping.
{% endhint %}
### Distinguishing repairs and spare parts
The following in particular likewise do not belong in this category:
* repairs to damaged smoke alarms,
* remedying technical defects,
* replacing defective devices,
* replacement because the service life has expired,
* replacing or newly installing mounting plates,
* costs resulting from damage or loss,
* work on a central fire alarm system, unless these are ordinary smoke alarms for apartments.
By law, maintenance and repair costs to remedy defects are **not** operating costs.
{% hint style="info" %}
A regular battery change can be part of a maintenance service, depending on the type of device, the contractual arrangement and the breakdown of the invoice. Where the complete device is replaced in the case of a smoke alarm with a permanently installed long-life battery, however, this is generally no longer mere maintenance.
{% endhint %}
### Mixed maintenance and rental contracts
Many service providers bill smoke alarms in an overall package, for example as:
* "rental and maintenance",
* "device service",
* "full-service flat rate",
* "provision, remote inspection and replacement".
Such overall invoices may not be entered in this category in full without being checked. Have the following shown separately if possible:
1. pure maintenance and inspection costs,
2. device rental or leasing,
3. new purchases and device replacement,
4. repairs,
5. additional administrative or portal fees.
Only the share comprehensibly attributable to the regular testing and ensuring of operational readiness should be recorded as recoverable maintenance. The separation is particularly important because maintenance costs can in principle be recoverable, whereas device rental costs are not under the case law of the Federal Court of Justice.
### Freehold apartments that are let
With a freehold apartment that is let, the owners' association can resolve on uniform installation, checking and maintenance by a specialist company. Under the case law of the Federal Court of Justice, such a resolution can also include apartments in which smoke alarms of their own are already present.
For the operating cost statement to the tenant it nevertheless has to be checked:
* which amount is attributable to the unit according to the WEG statement,
* whether maintenance and purchase were shown separately,
* whether device rental is included,
* whether the maintenance costs are agreed in the rental agreement,
* which allocation key is to be applied in the tenancy.
Allocation within the WEG does not automatically mean that every component charged there may also be recovered from the apartment's tenant.
### Documentation and receipts
Keep in particular the following documents:
* the maintenance contract,
* the invoice with the services shown separately,
* a list of the devices and apartments inspected,
* the date and result of each inspection,
* notes on defects found,
* evidence of the maintenance cycle,
* the split where there are several buildings,
* the calculation of the individual tenants' shares,
* the rental agreement with the type of operating cost agreed.
Advance payments of operating costs have to be billed annually. The tenant can also ask to inspect the underlying receipts.